










Horizon Reclaim auditors say Rs 6.25 crore provision creates H1 loss
Key highlights
- Joint auditors said a Rs 6.25 crore provision would turn Horizon Reclaim’s Rs 3.0898 crore H1 profit into a Rs 3.1469 crore loss.
- The land-sale agreement was extended seven times, with February 28, 2026 as the last mortgage-release date.
- Horizon Reclaim reported Rs 28.1798 crore of revenue from operations for the half year ended September 30, 2026.
- Cash and cash equivalents stood at Rs 16.4447 crore on September 30, 2026, compared with Rs 0.1503 crore on March 31, 2026.
powered by IRIS
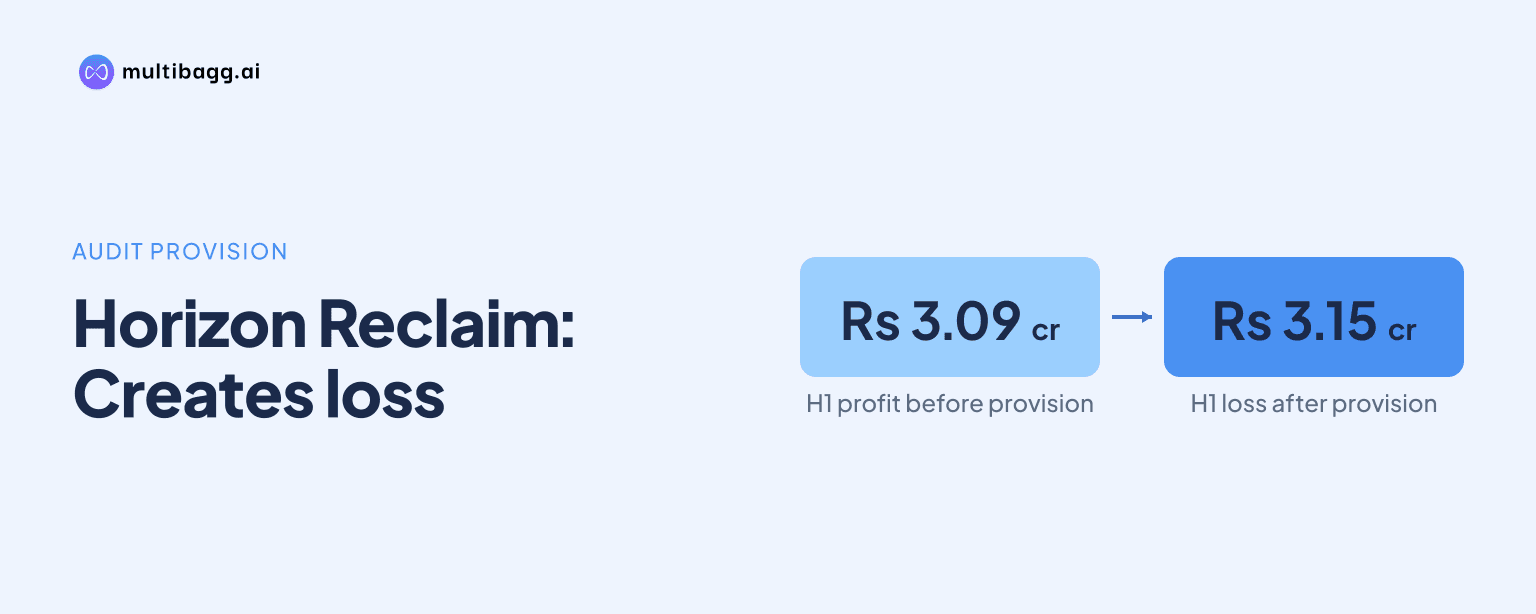
Horizon Reclaim (India) Limited’s joint auditors said a Rs 6.25 crore provision for a doubtful land-acquisition advance at September 30, 2026 would have changed its reported half-year profit of Rs 3.0898 crore into a Rs 3.1469 crore loss. The limited review therefore carried a qualified conclusion on this matter.
Know Horizon Reclaim (India) inside out
Results, valuation, peers and who's buying, in one view.
What caused the Horizon Reclaim audit qualification?
The qualification arose because the auditors considered recovery of a Rs 6.25 crore advance for land acquisition doubtful as of September 30, 2026. Horizon Reclaim paid the advance during financial year 2024-25 under an agreement to sell dated May 15, 2024, for land intended for capacity expansion.
Under the agreement, the seller was required to secure release of the property from the mortgage held by a consortium of banks by June 15, 2024, and execute the sale deed by June 30, 2024. The agreement also said that if the mortgage could not be cleared by December 31, 2024, the seller had to notify Horizon Reclaim in writing and the agreement would be treated as null and void.
The arrangement was extended seven times, with February 28, 2026 becoming the final date for release of the mortgage, according to the November 14, 2026 review report. The auditors said the mortgage remained unreleased at September 30, 2026 and the seller had not made the written communication required under the agreement.
If the agreement became null and void, its terms required the seller to refund the Rs 6.25 crore advance together with Rs 3 crore described as interest and penalty. The filing does not state that Horizon Reclaim had received either the advance or the additional Rs 3 crore by the September 30, 2026 reporting date.
How would the proposed provision change Horizon Reclaim’s H1 result?
A full provision would turn Horizon Reclaim’s reported Rs 3.0898 crore profit for the half year ended September 30, 2026 into a Rs 3.1469 crore loss, the auditors said. They stated that a provision against the advance should have been made under the principle of prudence because recovery was doubtful.
The movement from the reported profit to the auditor-stated loss is Rs 6.2367 crore. That is the arithmetic difference between the two stated results; the review report does not set out a separate reconciliation between that amount and the Rs 6.25 crore provision.
The reported September 2026 profit was also below the Rs 5.4045 crore profit reported for the half year ended March 31, 2026 and the Rs 4.5421 crore profit reported for the half year ended September 30, 2025. Those comparisons are based on the unadjusted accounts, as Horizon Reclaim did not record the provision identified in the qualified review.
Got a follow-up? Ask IRIS
Why did Horizon Reclaim not record the Rs 6.25 crore provision?
Horizon Reclaim did not record a provision because management said it expects to recover the advance along with Rs 3 crore of interest and penalty. The auditors also recorded management’s statement that Horizon Reclaim was pursuing completion of the land acquisition once the mortgage is released.
The advance remained within long-term loans and advances of Rs 6.25 crore on the September 30, 2026 unaudited balance sheet. That balance-sheet line was Rs 7.0907 crore at March 31, 2026, so the disputed amount represented most of the reported long-term advances at the later date.
The joint auditors did not say that the sale deed had been executed, the mortgage had been released or the seller had made a repayment by September 30, 2026. Their conclusion was qualified rather than adverse, stating that except for this matter, nothing had come to their attention indicating that the unaudited results failed to make the required disclosures or contained a material misstatement.
What do Horizon Reclaim’s half-year accounts show beyond the provision issue?
Horizon Reclaim reported revenue from operations of Rs 28.1798 crore for the half year ended September 30, 2026, compared with Rs 24.5025 crore for the half year ended March 31, 2026 and Rs 24.9182 crore a year earlier. Expenses were Rs 24.1335 crore in the latest half year, versus Rs 17.7549 crore in the March 2026 half year.
Raw-material consumption rose to Rs 19.547 crore in the September 2026 half year from Rs 15.991 crore in the preceding half year. Depreciation and amortisation increased to Rs 1.1511 crore from Rs 0.4866 crore over the same comparison, while reported profit before tax declined to Rs 4.1293 crore from Rs 7.2604 crore.
Cash and cash equivalents increased to Rs 16.4447 crore at September 30, 2026 from Rs 0.1503 crore at March 31, 2026. The cash-flow statement reported Rs 49.5099 crore of proceeds from issue of shares during the half year, alongside Rs 8.2561 crore of net cash used in investing activities and Rs 23.2424 crore of net repayment of borrowings.
Conclusion
The qualified review has a direct effect on how Horizon Reclaim’s half-year result is read: a Rs 6.25 crore advance remained on the September 30, 2026 balance sheet, while the auditors said providing for it would convert the reported Rs 3.0898 crore profit into a Rs 3.1469 crore loss. The issue is distinct from the company’s reported Rs 28.1798 crore of operating revenue for the period.
The next disclosed matter to watch is whether the seller releases the mortgage and completes the proposed acquisition that Horizon Reclaim says it is pursuing. The final extended mortgage-release date was February 28, 2026, yet no release or contractual written notice had been reported by September 30, 2026, leaving recovery of the Rs 6.25 crore advance unresolved.