










HPL C&I reaches 55% of revenue after 64% surge in Q2 FY27
Key highlights
- HPL’s C&I revenue rose 64.42% year on year to Rs 337.46 crore in Q2 FY27.
- C&I represented about 55% of HPL’s Q2 FY27 revenue, versus 47% in Q2 FY26.
- HPL’s Metering, Systems & Services revenue grew 18.17% to Rs 270.85 crore in Q2 FY27.
- HPL reported an order book of more than Rs 2,700 crore as of 2 November 2026.
powered by IRIS
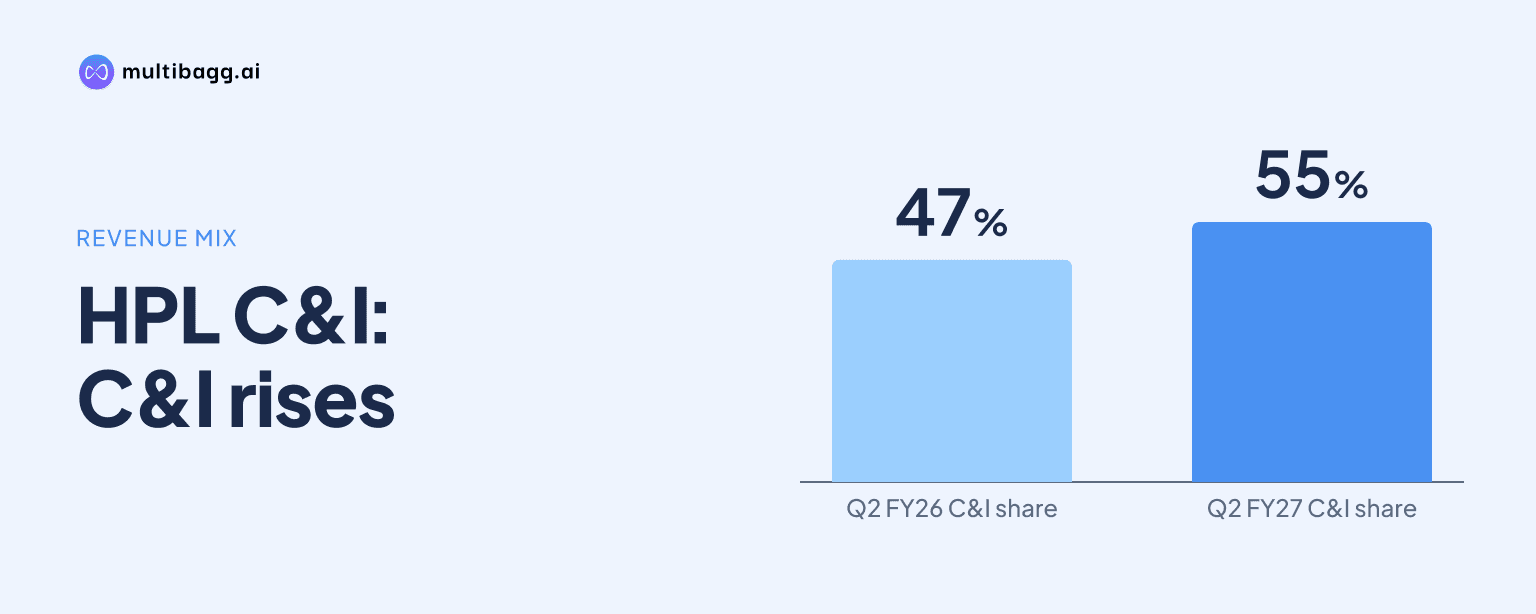
HPL’s Consumer & Industrial (C&I) business supplied about 55% of Q2 FY27 revenue after rising 64.42% year on year to Rs 337.46 crore, overtaking Metering, Systems & Services at Rs 270.85 crore. The shift accompanied HPL’s record quarterly revenue of Rs 608.31 crore, 40.02% above Q2 FY26.
Know HPL Electric & Power inside out
Results, valuation, peers and who's buying, in one view.
How did HPL’s revenue mix change in Q2 FY27?
HPL’s C&I segment became the larger revenue contributor in Q2 FY27, accounting for 55% of total revenue compared with 45% for Metering, Systems & Services. A year earlier, the positions were reversed: C&I contributed 47% and Metering, Systems & Services contributed 53% of Q2 FY26 revenue.
The change followed a faster increase in C&I sales than in the metering business. Total revenue increased from Rs 434.45 crore in Q2 FY26 to Rs 608.31 crore in Q2 FY27, while C&I revenue rose from Rs 205 crore to Rs 337 crore on the presentation’s like-for-like comparison. Metering, Systems & Services rose from Rs 229 crore to Rs 271 crore over the same periods.
What drove HPL’s Consumer & Industrial growth?
HPL’s C&I growth was broad-based across Wires & Cables, Lighting & Electronics and Domestic Switchgear in Q2 FY27. Wires & Cables revenue reached Rs 177.99 crore, Lighting & Electronics reached Rs 60.79 crore, up 59.43% year on year, and Domestic Switchgear reached Rs 33.33 crore, up 43.23%.
The presentation’s detailed Wires & Cables slide reports year-on-year growth of 159.46% for its Rs 177.99 crore Q2 FY27 revenue, based on a Rs 69 crore Q2 FY26 comparison. Its salient-highlights slide separately states 15.49% growth for the same revenue figure, so the disclosed year-on-year growth rates are inconsistent. Industrial Switchgear added Rs 65.34 crore in Q2 FY27 and rose 29.18% sequentially from Q1 FY27, against what HPL described as an exceptionally strong Q2 FY26 base.
The first-half figures indicate that the expansion was not confined to one quarter. C&I revenue was Rs 615.05 crore in H1 FY27, 60.03% above Rs 384 crore in H1 FY26, and HPL says the H1 FY27 amount had already exceeded the segment’s full-year FY24 revenue. Wires & Cables generated Rs 323.74 crore in H1 FY27, or about 95% of its Rs 340.74 crore full-year FY26 revenue.
How does HPL’s Consumer & Industrial business compare with Smart Metering?
HPL’s C&I business grew faster than Smart Metering in Q2 FY27, while Metering, Systems & Services remained a Rs 270.85 crore business with a stated long-cycle pipeline. Metering revenue increased 18.17% year on year and 13.97% sequentially, while C&I increased 64.42% year on year and 21.57% sequentially to Rs 337.46 crore.
For H1 FY27, Metering, Systems & Services delivered Rs 508.50 crore, up 17.40% from the corresponding prior-year period, compared with Rs 615.05 crore for C&I. HPL characterises metering as a maturing market with stable growth, whereas it describes C&I as faster-cycle and channel-led, supported by demand across its electrical product portfolio.
HPL reported an order book of more than Rs 2,700 crore as of 2 November 2026, with Metering, Systems & Services representing about 96% of that amount. The company says this pipeline covers roughly two and a half years of segment revenue at the current run rate and is linked to advanced metering infrastructure service provider, or AMISP, dispatch schedules. Those schedules can cause quarter-to-quarter revenue variation.
Got a follow-up? Ask IRIS
What did the revenue mix shift mean for HPL’s margins and earnings?
HPL’s revenue growth did not translate into proportionate operating-profit growth in Q2 FY27. Earnings before interest, tax, depreciation and amortisation, or EBITDA, rose 8.37% year on year to Rs 71.42 crore, while EBITDA margin declined to 11.74% from 15.14% in Q2 FY26. Gross profit increased 9.42% to Rs 173.79 crore as gross margin moved to 28.6% from 36.6%.
At the segment level, C&I earnings before interest and tax, or EBIT, margin was 8.90% in Q2 FY27, down from 10.98% in Q2 FY26. Metering, Systems & Services EBIT margin declined to 12.28% from 17.52%. HPL attributes the C&I decline to volatility in metals and industrial plastics amid geopolitical and commodity-market conditions.
Profit before tax increased 2.95% to Rs 31.39 crore, while profit after tax increased 4.68% to Rs 23.40 crore in Q2 FY27. For H1 FY27, profit after tax was Rs 42.10 crore, up 3.08% year on year, despite revenue from operations increasing 37.44% to Rs 1,123.55 crore. The larger C&I contribution coincided with lower reported group and segment margins in the period.
What is HPL planning for the second half of FY27?
HPL management’s stated FY27 focus is to scale both verticals while restoring margins, including extending pricing actions initiated in H1 FY27 across Wires & Cables, Lighting and Switchgear. The company expects the benefit of those actions to flow progressively from H2 FY27, rather than reporting an immediate margin recovery in Q2 FY27.
HPL says its two businesses allow it to serve the electrical value chain from the utility grid to the consumer socket through shared manufacturing scale, research and development, and distribution. In C&I, Wires & Cables demand is spread across five channels: real estate, industrial original equipment manufacturers, solar, telecom and 5G, and institutional customers. Its Rs 323.74 crore H1 FY27 revenue was described as volume-led rather than driven by commodity prices.
The metering order book remains the disclosed source of longer-term visibility, while C&I supplies the faster-cycle component of the mix. HPL reported more than Rs 2,700 crore of orders on 2 November 2026, but did not provide a separate C&I order-book figure. The pace of AMISP dispatches and the rollout of pricing actions are therefore the disclosed factors relevant to subsequent periods.
Conclusion
HPL’s Q2 FY27 results show a material change in revenue composition: C&I reached 55% of sales as its Rs 337.46 crore quarterly revenue expanded 64.42%, while Metering, Systems & Services grew 18.17% to Rs 270.85 crore. The result is a more balanced revenue base across channel-led electrical products and utility-linked metering, although both segment and group margins declined year on year.
The next results should indicate whether HPL’s H1 FY27 pricing actions lift C&I’s 8.90% EBIT margin progressively from H2 FY27, as management expects, and whether the more than Rs 2,700 crore order book as of 2 November 2026 converts according to AMISP dispatch schedules. The presentation also leaves unresolved the conflicting Wires & Cables year-on-year growth rates of 159.46% and 15.49% reported for Q2 FY27.