










HPL Q2 revenue reaches Rs 608 crore as Consumer & Industrial leads
Key highlights
- HPL Q2 FY27 revenue reached a record Rs 608.31 crore, up 40.02% year on year.
- Consumer & Industrial Q2 FY27 revenue grew 64.42% to Rs 337.46 crore, exceeding Metering revenue of Rs 270.85 crore.
- Wires & Cables Q2 FY27 revenue rose 159.46% year on year to Rs 177.99 crore.
- HPL reported an order book above Rs 2,700 crore as of 2 November 2026, with over 96% from Metering, Systems & Services.
powered by IRIS
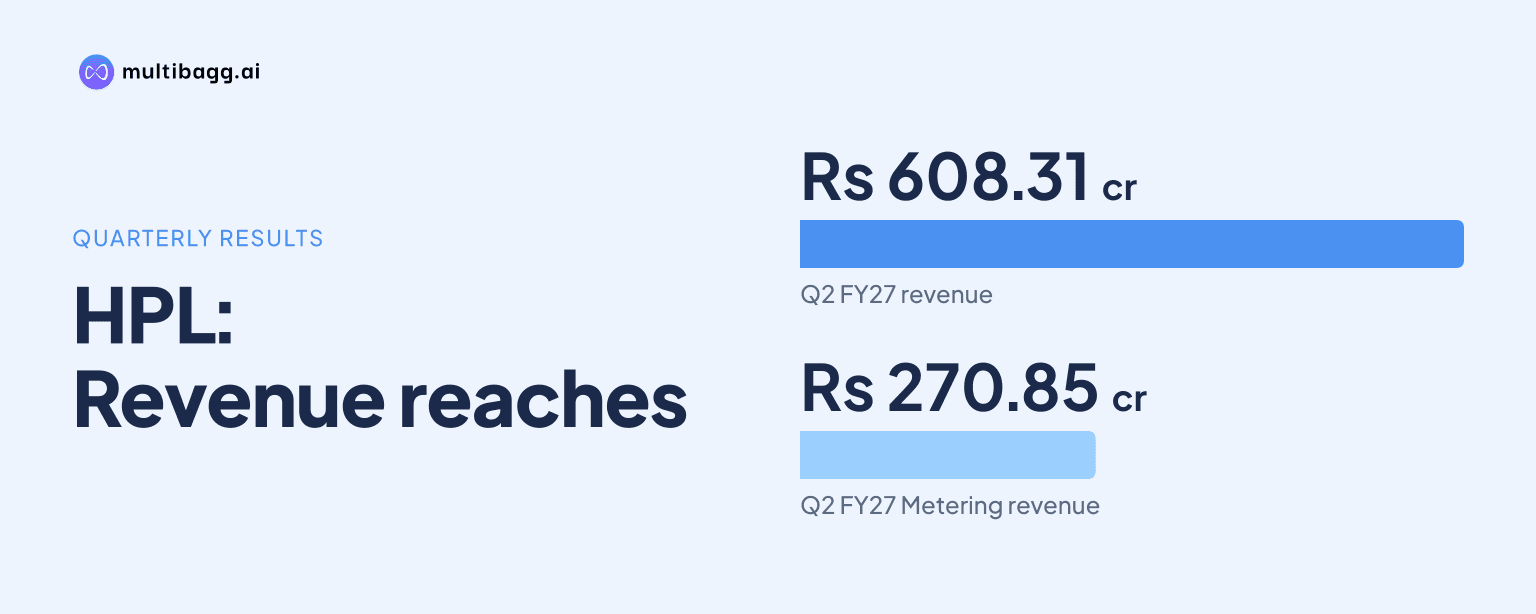
HPL Electric & Power Limited reported record Q2 FY27 revenue from operations of Rs 608.31 crore, up 40.02% year on year, as Consumer & Industrial revenue rose 64.42% to Rs 337.46 crore and moved ahead of Metering, Systems & Services at Rs 270.85 crore for the quarter ended 30 September 2026.
Know HPL Electric & Power inside out
Results, valuation, peers and who's buying, in one view.
What drove HPL's record Q2 FY27 revenue?
HPL's record revenue was driven chiefly by faster Consumer & Industrial growth, which contributed Rs 337.46 crore in Q2 FY27, compared with Rs 270.85 crore from Metering, Systems & Services. Total revenue crossed Rs 600 crore for the first time, while Consumer & Industrial growth of 64.42% was more than three times the 18.17% year-on-year increase reported by Metering, Systems & Services.
Wires & Cables was the largest specified Consumer & Industrial growth contributor, with Q2 FY27 revenue rising 159.46% year on year to Rs 177.99 crore. Lighting & Electronics revenue increased 59.43%, Domestic Switchgear rose 43.23%, and Industrial Switchgear grew 29.18% sequentially against what HPL described as a strong Q2 FY26 comparison base. The announcement reported broad-based growth across those product lines.
The first half showed the same growth pattern, with H1 FY27 revenue rising 37.44% to Rs 1,123.55 crore. Consumer & Industrial generated Rs 615.05 crore, up 60.03%, whereas Metering, Systems & Services generated Rs 508.50 crore, up 17.40%. Wires & Cables alone delivered Rs 323.74 crore in the half year, which HPL said was about 95% of its full-year FY26 revenue.
How did HPL's business mix change in Q2 FY27?
HPL's revenue mix shifted to 55% Consumer & Industrial and 45% Metering in Q2 FY27, reversing the 47% Consumer & Industrial and 53% Metering split in Q2 FY26. The change meant Consumer & Industrial produced Rs 66.61 crore more revenue than Metering, Systems & Services during the latest quarter.
The mix transition was also present over the six months ended 30 September 2026, with HPL stating that the same 55% Consumer & Industrial and 45% Metering balance applied for H1 FY27. Consumer & Industrial's Rs 615.05 crore first-half revenue exceeded Metering, Systems & Services' Rs 508.50 crore by Rs 106.55 crore, following growth in wires, lighting, domestic switchgear and industrial switchgear.
HPL's Consumer & Industrial platform includes domestic and industrial switchgear, wires and cables, lighting, fans and related products. Its disclosed distribution network comprises more than 90 branch and representative offices, more than 900 authorised dealers and more than 90,000 retailers. These channels serve residential, commercial, institutional and industrial customers, while Metering, Systems & Services is linked to utility programmes and smart-meter execution.
Got a follow-up? Ask IRIS
Why did HPL's profit growth lag revenue growth?
HPL's profitability grew in rupee terms in Q2 FY27, but management said margins reflected input-cost volatility and the changing revenue mix. Gross profit rose 9.42% to Rs 173.79 crore and earnings before interest, tax, depreciation and amortisation, or EBITDA, increased 8.37% to Rs 71.42 crore, both below the 40.02% revenue growth rate.
The Q2 FY27 gross margin was 28.57% and EBITDA margin was 11.74%. For H1 FY27, gross margin was 29.37% and EBITDA margin was 11.98%, alongside Rs 329.94 crore of gross profit and Rs 134.60 crore of EBITDA. Profit after tax, or PAT, increased 4.68% to Rs 23.40 crore in Q2 and 3.08% to Rs 42.10 crore in H1.
Segment earnings before interest and tax, or EBIT, margins fell in both businesses. Metering's Q2 EBIT margin declined to 12.28% from 17.59% in Q2 FY26, a reduction of 5.31 percentage points. Consumer & Industrial's EBIT margin declined to 8.90% from 11.11%, a reduction of 2.21 percentage points, even as its revenue grew 64.42% to Rs 337.46 crore.
Management said pricing and mix actions were under way entering the second half of FY27, with the stated aim of improving margin quality while scaling both businesses. The announcement did not quantify the planned pricing actions, their expected timing, or an EBITDA or EBIT margin target for FY27.
What supports HPL's metering revenue visibility?
HPL reported an order book of more than Rs 2,700 crore as of 2 November 2026, with over 96% tied to Metering, Systems & Services. The disclosed concentration gives the metering business longer-term visibility, although the company said quarterly revenue can vary with programme execution schedules.
Metering, Systems & Services revenue rose 18.17% year on year to Rs 270.85 crore in Q2 FY27 and 17.40% to Rs 508.50 crore in H1 FY27. HPL said quarterly growth is execution-led and can vary with Advanced Metering Infrastructure Service Provider, or AMISP, schedules. Management described a sequential pick-up as the smart-meter market moves towards a more mature execution phase.
The company disclosed seven manufacturing facilities, with annual capacity of about 11 million electronic meters, 26 million lighting units, 16 million switchgear units and 194 million metres of wires and cables. HPL also has two research and development centres with more than 100 engineers. Management identified disciplined execution, research and development-led differentiation, channel-partner expansion and conversion of capacity investments as its stated operational priorities.
Conclusion
HPL's Q2 FY27 results show that revenue growth has become more dependent on Consumer & Industrial products: the segment rose 64.42% to Rs 337.46 crore and overtook Metering, Systems & Services at Rs 270.85 crore. The resulting 55% Consumer & Industrial revenue mix helped lift consolidated revenue 40.02% to Rs 608.31 crore, while gross profit, EBITDA and PAT grew more slowly than sales.
The next disclosed issues to watch are HPL's pricing and mix actions during H2 FY27, their effect on the Q2 EBITDA margin of 11.74%, and delivery against the more than Rs 2,700 crore order book reported on 2 November 2026. Metering execution will remain subject to AMISP schedules, while management also plans to expand channel partners and convert existing capacity investments into earnings growth.