










IFGL Refractories Limited faces Rs 40.28 crore tax impact
Key highlights
- IFGL Refractories disclosed Rs 40.28 crore of tax impacts across three goodwill-depreciation disputes.
- The CIT(A) upheld the Rs 9.84 crore tax-impact disallowance for assessment year 2020-21 on November 4, 2026.
- IFGL Refractories' pending Section 10AA appeal involves Rs 8.32 crore at September 30, 2026.
- Standalone profit after tax rose to Rs 34.10 crore in the six months ended September 30, 2026, from Rs 29.60 crore a year earlier.
powered by IRIS
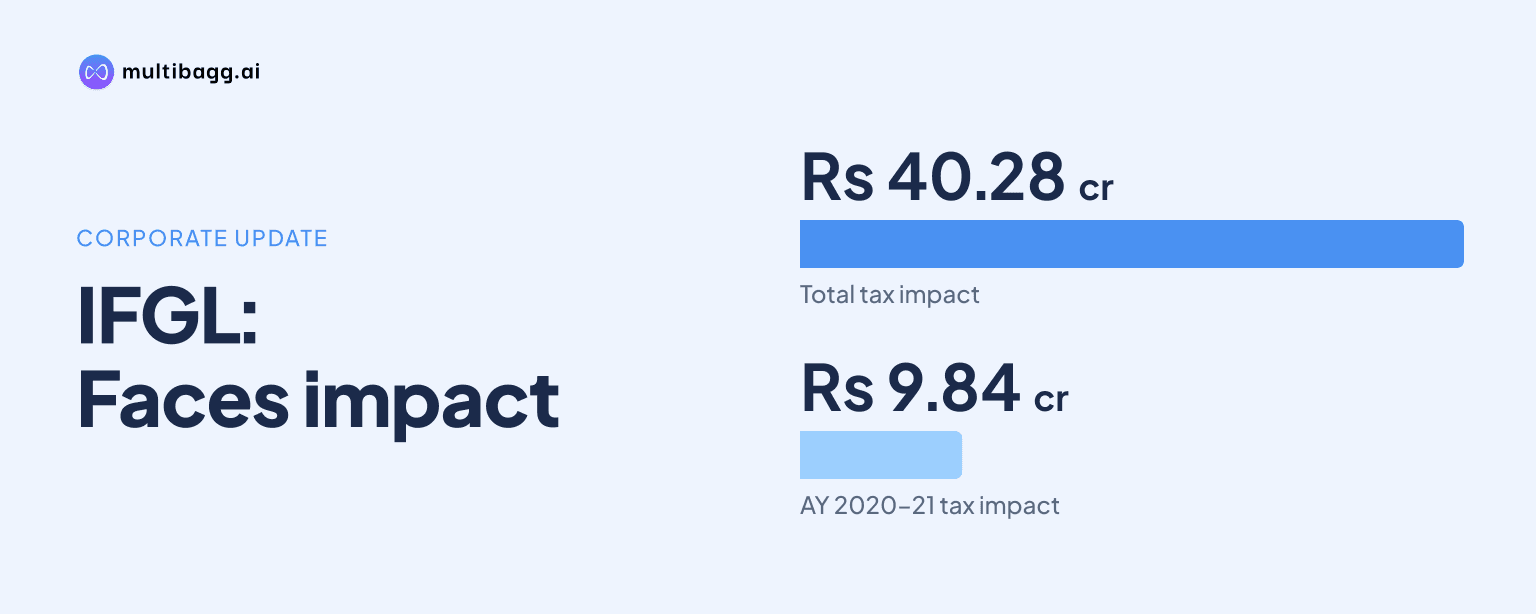
IFGL Refractories Limited disclosed tax impacts of Rs 40.28 crore across three goodwill-depreciation disputes as of September 30, 2026, including a Rs 9.84 crore claim disallowance upheld on November 4, 2026. IFGL Refractories also has a pending Section 10AA appeal involving Rs 8.32 crore.
Know IFGL Refractories inside out
Results, valuation, peers and who's buying, in one view.
What is IFGL Refractories' goodwill-depreciation tax dispute?
IFGL Refractories' goodwill-depreciation dispute concerns deductions claimed on goodwill arising from the April 1, 2016 amalgamation of erstwhile IFGL Refractories Ltd. with the company. The National Company Law Tribunal, Kolkata approved the amalgamation on August 3, 2017, and goodwill of Rs 266.99 crore arose under the purchase method defined in the former Accounting Standard 14.
IFGL Refractories estimated a 10-year useful life for that goodwill and amortised Rs 6.67 crore each quarter through the year ended March 31, 2026. Its carrying value became nil at that date, so no goodwill amortisation was charged in the quarters ended June 30, 2026 and September 30, 2026, or the six months ended September 30, 2026.
The absence of the goodwill charge coincided with standalone depreciation and amortisation expense of Rs 16.27 crore in the six months ended September 30, 2026, compared with Rs 28.79 crore a year earlier. The tax proceedings did not alter the reported half-year tax charge, because IFGL Refractories treated the identified goodwill-related exposure, including consequential interest if any, as contingent liabilities.
Which goodwill-depreciation claims are under challenge?
The three disputed goodwill-depreciation deductions total Rs 115.77 crore, with stated tax impacts of Rs 40.28 crore across assessment years 2018-19, 2019-20 and 2020-21. The largest disclosed tax impact is Rs 17.32 crore for assessment year 2018-19, followed by Rs 13.12 crore for 2019-20 and Rs 9.84 crore for 2020-21.
For assessment year 2020-21, tax authorities had disallowed the Rs 28.16 crore deduction in earlier assessment proceedings. The Commissioner of Income-tax (Appeals), or CIT(A), upheld that disallowance on November 4, 2026, and IFGL Refractories said it was evaluating further legal action, including contesting the order at an appropriate forum.
For assessment years 2018-19 and 2019-20, tax authorities issued notices under Section 148 of the Income-tax Act to reopen assessments, stating that the Rs 50.06 crore and Rs 37.55 crore claims had escaped assessment as income. IFGL Refractories filed writ petitions before the Calcutta High Court on May 21, 2024 and said legal opinion supports its view that the deductions remain sustainable on merit.
Got a follow-up? Ask IRIS
What is IFGL Refractories' Section 10AA appeal about?
IFGL Refractories is challenging the validity of the Explanation to Section 10AA(1) of the Income-tax Act, which applied from assessment years beginning April 1, 2018. The company said the Explanation denies the benefit intended under Section 10AA and filed a writ petition before the Calcutta High Court.
A single bench of the Calcutta High Court dismissed that petition in an earlier year, after which IFGL Refractories appealed to a division bench. The division bench admitted the appeal on January 10, 2024, but the November 13, 2026 filing gives no hearing date or expected timetable for a decision.
The tax amount involved was Rs 8.32 crore at September 30, 2026, unchanged from September 30, 2025, March 31, 2026 and June 30, 2026. IFGL Refractories considered the amount possible in nature based on legal opinion, while management said the outcome would not materially affect its financial position and results of operations.
How did the auditor address IFGL Refractories' tax uncertainty?
S.R. Batliboi & Co. LLP highlighted the pending Section 10AA appeal as an emphasis-of-matter item in its November 13, 2026 limited-review report. The auditor said no adjustment had been made in the standalone financial results pending a decision from the Calcutta High Court division bench, while leaving its review conclusion unmodified.
The auditor's standalone review covered the quarter and six months ended September 30, 2026 and stated that nothing had come to its attention indicating a material misstatement or inadequate required disclosure. The same Section 10AA uncertainty appeared as an emphasis-of-matter item in the consolidated review report, again without modification of the conclusion.
Standalone profit after tax was Rs 34.10 crore for the six months ended September 30, 2026, up from Rs 29.60 crore in the prior-year period, while revenue from operations rose to Rs 619.87 crore from Rs 562.26 crore. Those reported figures include no adjustment for the Rs 8.32 crore Section 10AA matter, consistent with the auditor's disclosure.
What should readers watch in IFGL Refractories' tax cases?
The immediate goodwill-related development to watch is whether IFGL Refractories challenges the November 4, 2026 CIT(A) order for assessment year 2020-21. That decision concerns the Rs 9.84 crore tax impact and is the only one of the three goodwill-depreciation matters for which the filing reports an adverse appellate outcome.
The other outstanding event is the division bench's decision in the Section 10AA appeal admitted on January 10, 2024. Until that ruling, IFGL Refractories has made no financial-results adjustment for the Rs 8.32 crore amount, which remained unchanged across four balance dates from September 30, 2025 through September 30, 2026.
Conclusion
IFGL Refractories disclosed two separate unresolved tax matters: Rs 40.28 crore of tax impacts across three goodwill-depreciation claims and Rs 8.32 crore linked to its Section 10AA challenge. The 2020-21 goodwill claim has reached an adverse CIT(A) decision, while the two reopened earlier assessments and the Section 10AA appeal remain unresolved.
Next, readers should watch for IFGL Refractories' decision on further legal action against the November 4, 2026 CIT(A) order and for the Calcutta High Court division bench's ruling on Section 10AA. The filing does not disclose a scheduled court date or a selected forum for the proposed 2020-21 challenge.