










Indo Borax Q2 FY27 Profit Falls 71% to ₹4.75 Crore
Key highlights
- Indo Borax reported Q2 FY27 consolidated net profit of ₹4.75 crore, down 70.79% year-on-year.
- The stated Q2 FY27 consolidated revenue was ₹58.94 crore, up 1.88% from ₹57.85 crore a year earlier.
- Q2 FY27 profit was 70.77% lower than the ₹16.25 crore reported in Q1 FY27.
- Indo Borax has guided for FY27 revenue of ₹250 crore to ₹260 crore and a 20% EBITDA margin.
powered by IRIS
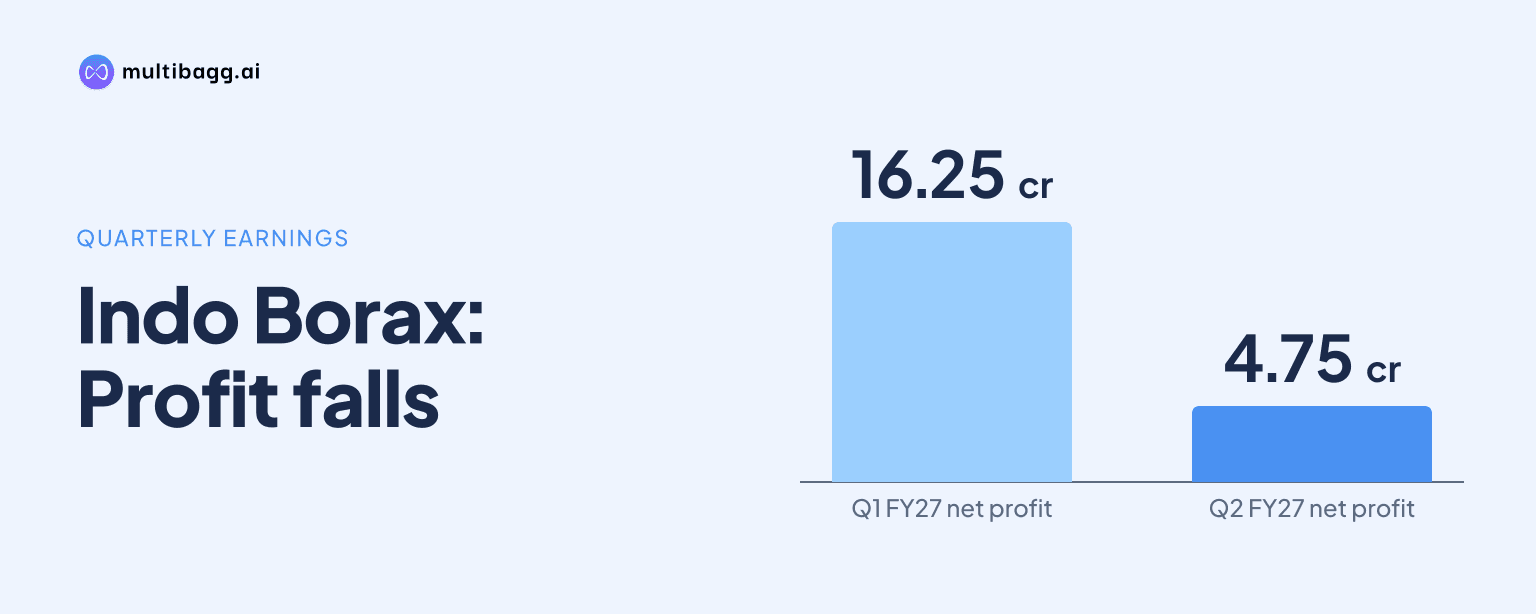
Indo Borax & Chemicals Ltd. reported consolidated net profit of ₹4.75 crore for Q2 FY27, down 70.79% year-on-year from ₹16.26 crore and 70.77% sequentially from ₹16.25 crore in Q1 FY27. The sharp fall reversed the stronger profitability reported in the June quarter and puts focus on the company's ability to meet its FY27 margin target.
Know Indo Borax & Chemicals inside out
Results, valuation, peers and who's buying, in one view.
What did Indo Borax report for Q2 FY27?
Indo Borax reported Q2 FY27 consolidated revenue of ₹58.94 crore for the quarter ended September 30, 2026, according to the supplied quarterly-results disclosure. Revenue was 1.88% higher than ₹57.85 crore in the year-earlier period, while net profit declined to ₹4.75 crore from ₹16.26 crore.
The Q2 result was declared on November 6, 2026. The reported period covers July to September 2026. The company had said earlier that its board would consider standalone and consolidated unaudited results for the quarter and half-year ended September 30 on that date.
A separate earnings summary in the supplied material lists Q2 revenue at ₹63.35 crore, or ₹633.5 million, and says revenue rose 9.5% from the prior-year quarter. That figure does not match the ₹58.94 crore revenue cited in the quarterly-results disclosure. Similarly, the supplied material cites a 7.5% profit margin in one summary and an 8.1% net profit margin in another. This report therefore uses ₹58.94 crore as the stated quarterly-results figure while noting the inconsistency.
How does the September-quarter result compare with Q1 FY27?
The September-quarter profit was substantially lower than Indo Borax's June-quarter profit of ₹16.25 crore. The sequential decline of 70.77% follows a Q1 FY27 in which the company had reported strong demand and improved operational efficiencies.
In Q1 FY27, Indo Borax recorded consolidated operating revenue of ₹70.36 crore, up 31.34% from ₹53.57 crore a year earlier. EBITDA rose 62.16% to ₹19.80 crore from ₹12.21 crore, and net profit increased 59.31% from ₹10.20 crore. Its Q1 EBITDA margin was 28.1%, compared with 22.8% in the corresponding prior-year quarter.
The company also reported a Q1 FY27 PAT margin of 22.3%, up from the prior-year period. Against that base, the Q2 net profit margin figures of 7.5% or 8.1% cited in the supplied data indicate a materially lower conversion of revenue into profit. The supplied information does not provide a detailed cost or product-level explanation for the Q2 margin change.
The contrast between the two quarters is important because Q1's performance was supported by strong demand, higher capacity utilisation and operational efficiencies, according to the company's August communication. Q2 revenue, based on the stated ₹58.94 crore figure, was also below Q1 revenue of ₹70.36 crore, while profit declined much more sharply.
Why does the Q2 margin decline matter for Indo Borax?
The margin decline matters because Indo Borax had set a FY27 EBITDA margin target of 20%. The company had guided for FY27 revenue of ₹250 crore to ₹260 crore, compared with ₹215 crore in the previous year, and indicated that the target implied absolute EBITDA growth of 11-12%.
Q1 FY27 began well above that margin objective, with EBITDA margin at 28.1%. But the Q2 profit outcome shows that quarterly earnings can vary considerably even when revenue is broadly stable on a year-on-year basis. A 1.88% increase in revenue, based on the quarterly-results disclosure, did not prevent a 70.79% fall in net profit.
For investors, the supplied data offers no confirmed breakdown of raw-material costs, selling prices, inventory movements, other income, finance costs or tax effects for Q2. It would therefore be premature to attribute the profit decline to a specific cause. The next detailed financial filing, earnings presentation or management discussion may provide greater clarity on whether the lower profitability was driven by operating costs, product mix or other items.
Got a follow-up? Ask IRIS
What is Indo Borax's FY27 operating plan?
Indo Borax's disclosed FY27 plan calls for revenue of ₹250 crore to ₹260 crore and a 20% EBITDA margin. The company also stated a target to reach DOT volume of 1,500 tonnes and outlined capital expenditure of ₹50 crore over two to three years.
The company is a manufacturer of boron-based chemicals in India. Its FY26 operating income was ₹215.45 crore and EBITDA was ₹44.16 crore, according to the supplied Q1 FY27 coverage. These figures provide the base from which it is pursuing the FY27 revenue and profitability targets.
The available disclosures also show that the company has published annual reports through FY26 and has made quarterly results, presentations and earnings-call transcripts available through its investor resources. The Q1 FY27 earnings call was held on September 2, 2026, following the release of results for the quarter ended June 30, 2026.
For the broader chemicals sector, the result underlines the importance of margins alongside top-line growth. Chemical manufacturers can report growth in revenue while profitability changes significantly, depending on the cost structure and the mix of products sold. In Indo Borax's case, the supplied figures establish the profit decline but do not establish the underlying reason.
What should investors monitor after the Q2 result?
Investors should monitor whether Indo Borax provides a reconciliation or clarification of the differing Q2 revenue and margin figures contained in the supplied material. The stated quarterly-results revenue is ₹58.94 crore, while another summary gives ₹63.35 crore, making a consistent assessment of quarterly growth more difficult without the underlying financial statements.
The next relevant indicators will be revenue progression, EBITDA margin and net profit relative to the company's FY27 guidance. The company's market capitalisation was stated at ₹1,367 crore in the supplied data, but no share-price movement or market reaction was provided. As a result, no conclusion can be drawn from the source about the stock's immediate response to the earnings release.
Investors may also compare future quarterly profitability with the Q1 FY27 EBITDA margin of 28.1% and the full-year EBITDA margin target of 20%. The company has not changed its FY27 guidance in the supplied information. Whether the September-quarter weakness affects that outlook will depend on information disclosed in subsequent results or management commentary.
Conclusion
Indo Borax's Q2 FY27 result marked a clear reversal from its strong June-quarter performance. Consolidated net profit fell to ₹4.75 crore, down 70.79% year-on-year and 70.77% from Q1 FY27, while reported revenue increased modestly on the quarterly-results basis. The decline in profit margin is the central financial development, although the supplied information does not identify its specific causes.
The next point to watch is management's disclosure on the path to its FY27 revenue target of ₹250 crore to ₹260 crore and 20% EBITDA margin goal. Investors will also need clarity on the conflicting Q2 revenue and margin figures and on the operating factors that led to the lower September-quarter profit.