










Influx cuts client count to pursue revenue productivity
Key highlights
- Influx said its quarterly client count was about 500, while its overall client base was more than 700.
- Management said Carbamide Forte had indicated a requirement for a 3-times capacity ramp-up.
- Influx said earlier capacity utilisation was about 85% to 90%, while growth reached around 25% to 27%.
- Management targeted commercial production at the new facility approximately in January, subject to a 3-to-4-week licence process.
powered by IRIS
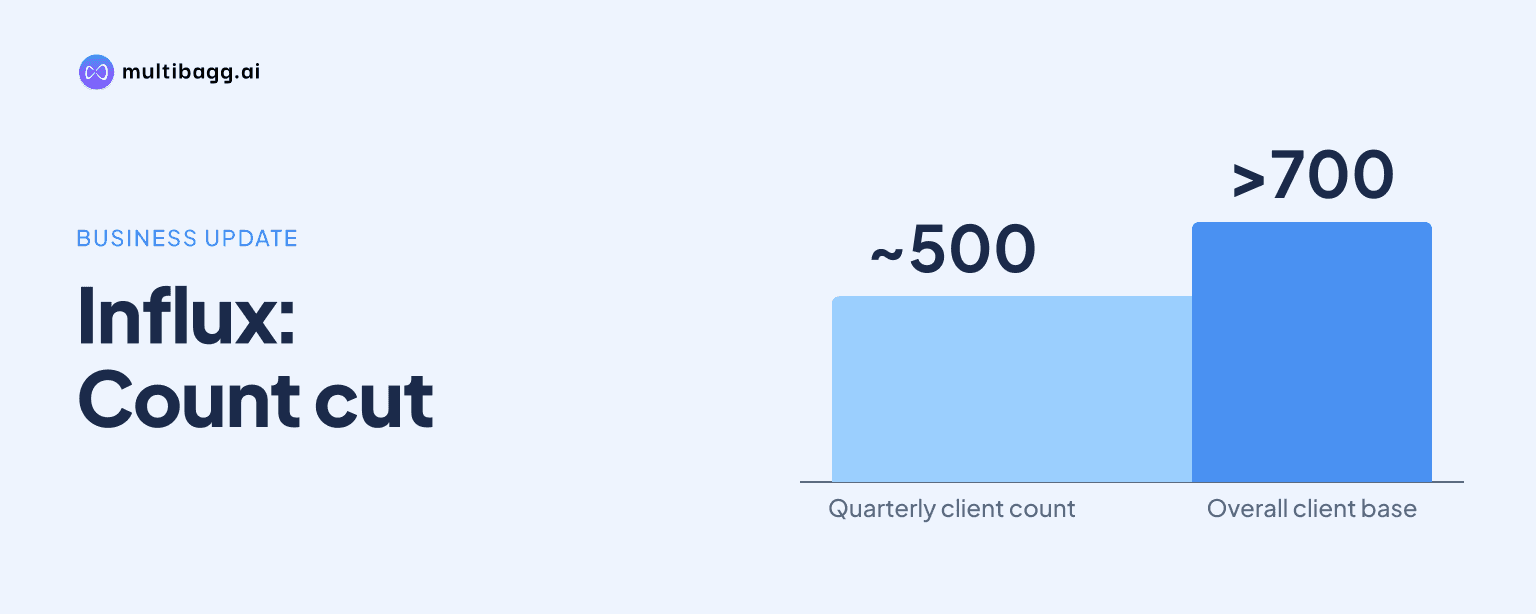
Influx Healthtech Limited reported about 500 clients in the quarter, compared with more than 700 clients overall, as management said it was concentrating on larger accounts to improve operational efficiency while retaining medium-scale customers that could become future large accounts. Management said the approach was not a decision to serve only large customers.
Know Influx Healthtech inside out
Results, valuation, peers and who's buying, in one view.
Why is Influx reducing the reported client count?
Influx is reducing the reported client count because management wants greater operational efficiency and more revenue from fewer, larger relationships. During the call, an analyst contrasted a prior-year client count of roughly 718 with 523, while management said the quarterly result reflected about 500 clients even though the company had more than 700 clients overall.
Management described the process as trimming its customer base and putting greater focus on bigger clients. It said the objective was for the business to perform better with fewer clients, rather than treating a lower count as evidence of a withdrawal from customer acquisition. Management did not identify the customer categories that had been trimmed or quantify sales from accounts no longer included in the quarterly count.
The change comes while Influx is adding production capacity and seeking to increase output from existing equipment. Management said earlier capacity utilisation had been about 85% to 90%, but the company had still achieved growth of around 25% to 27% after bringing additional machinery into use. The company said replacing old machines with higher-output equipment can also lift production at existing sites, subject to space and safety limits.
How will Influx allocate its new capacity among clients?
Influx expects the new facility to be more relevant to larger customers, while the existing plant can continue serving medium-scale clients. Management said the new capacity involves automation and machinery that may appeal more to bigger accounts, but it has not set a fixed allocation of production between customer sizes or between the two facilities.
Management said it wants a mixed customer base because five or 10 medium-scale clients can eventually develop into one major account. The older plant is already operational and is the intended base for medium-scale customers, while the new facility is expected to take larger accounts. However, management said it will assess actual capacity utilisation before making a final allocation decision.
Product economics will determine the mix as much as customer size. Management said the decision will depend on the product, the client and the margin available, rather than a rule that large clients must use the new site. It cited liquid-fill, quick-snap and aerosol technology as offerings with relatively few comparable suppliers, which management said could support its ability to balance business across large, medium and small customers.
The new plant still requires a licence before commercial production, which management was targeting approximately in January. Management said the licence process generally takes about three to four weeks after the plant is ready, although any regulatory queries could extend the timing. It also said the facility requires at least six months of operating records before an audit under the 21 CFR target can be considered.
Has Influx lost major customers while trimming accounts?
Influx said it has not seen any abrupt loss among its top 50 customers, although customer rankings within the top 10 can change. Management said the underlying customer group has remained broadly intact, but relative sales growth can move one client from second to third place or raise another customer into the leading group.
Management cited Medchain as an example of this movement. It said Medchain had not previously been among the leading accounts but had become Influx's number-two customer as its own sales increased, including through e-commerce channels. Management said this type of ranking change does not necessarily indicate that another top customer has stopped buying.
Existing customers are central to the additional-capacity plan. Management identified Carbamide Forte as its top client and said it had communicated a requirement for a three-times capacity ramp-up. Management also said Fast&Up had placed liquid-fill orders and was awaiting capacity expansion, indicating that some expected demand comes from current accounts rather than only new customer wins.
Influx also said it had signed an agreement with Aristo and completed product sampling. Management expects an order when market conditions allow a fish-oil product launch, but said fish-oil supply is currently short. The agreement and completed sampling show a potential large-client opportunity, although management did not present it as booked revenue or give an order value.
Got a follow-up? Ask IRIS
How does Influx plan to maintain margins with larger clients?
Influx said larger-client volume should not automatically reduce margins because it plans to balance those accounts with medium, small and technology-led customers. Asked whether Carbamide Forte's three-times capacity requirement could cause margin compression, management said it would manage the overall customer and product mix rather than allow one account to determine company-wide economics.
Management said it was maintaining margins by taking clients that accept its commercial terms, even if this takes a couple of months longer. It also said liquid-fill, quick-snap and aerosol offerings have limited direct comparability in the market, which may reduce simple rate-based comparisons. Management did not disclose a margin target or quantify the profitability of these product categories.
The company is also using existing locations to limit the effect of the new plant's delay. Management said tablet machinery originally planned for the new plant had been installed at the Olahey facility, where it is also planning beverage production. Management said this should generate revenue and help prevent a significant loss of business while the new site is delayed by a couple of months.
Management said it would try to deliver growth of 25% to 30% through March 2027, but this was an expression of intent rather than formal revenue guidance. It also declined to provide a current monthly exit run rate when asked. Earlier in the call, management said it believed the current run rate could enable it to meet targets of Rs 200 crore to Rs 210 crore, without giving a supporting monthly figure.
What does the customer strategy mean for future growth?
Influx's strategy is to lift revenue productivity by concentrating more capacity and management attention on larger accounts, while keeping medium-scale customers in the pipeline. The reported quarterly count of about 500 clients versus more than 700 overall is therefore a deliberate operating choice, according to management, not a stated plan to abandon the wider customer base.
The strategy also links client selection to manufacturing capability. The new facility is intended to support bigger accounts, while the existing plant and Olahey installation provide capacity for medium clients, tablet production and beverages. Management's examples of Carbamide Forte's three-times requirement, Fast&Up's liquid-fill orders and the Aristo agreement show that both existing and prospective customers are part of the capacity plan.
Conclusion
Influx is seeking more output and potentially more revenue per customer by trimming lower-priority accounts and focusing on larger relationships. Management's comments suggest that the client-count reduction is paired with a two-site model: larger customers may use the new plant, while medium customers remain important at existing facilities because they can develop into larger accounts over time.
The next points to watch are the licence timeline for commercial production around January, actual use of the new facility, and whether the six-month operating history allows the planned audit process. Management's stated aim of 25% to 30% growth through March 2027, Carbamide Forte's indicated three-times capacity need and the timing of Aristo's fish-oil launch will provide further evidence of how quickly the strategy converts into production and revenue.