










Antala FY26 profit more than doubled, but operating cash fell
Key highlights
- Antala’s FY26 revenue from operations rose to Rs 47.4047 crore from Rs 25.0221 crore in the preceding reported period.
- Antala’s FY26 profit after tax increased to Rs 4.2363 crore from Rs 1.5005 crore, although the periods were not comparable full-year periods.
- Inventory, receivables and advances consumed Rs 12.4650 crore of cash in FY26, against operating profit before working-capital changes of Rs 6.2752 crore.
- Cash and cash equivalents fell to Rs 46.51 lakh at September 30, 2026, despite positive six-month operating cash flow of Rs 1.1518 crore.
powered by IRIS
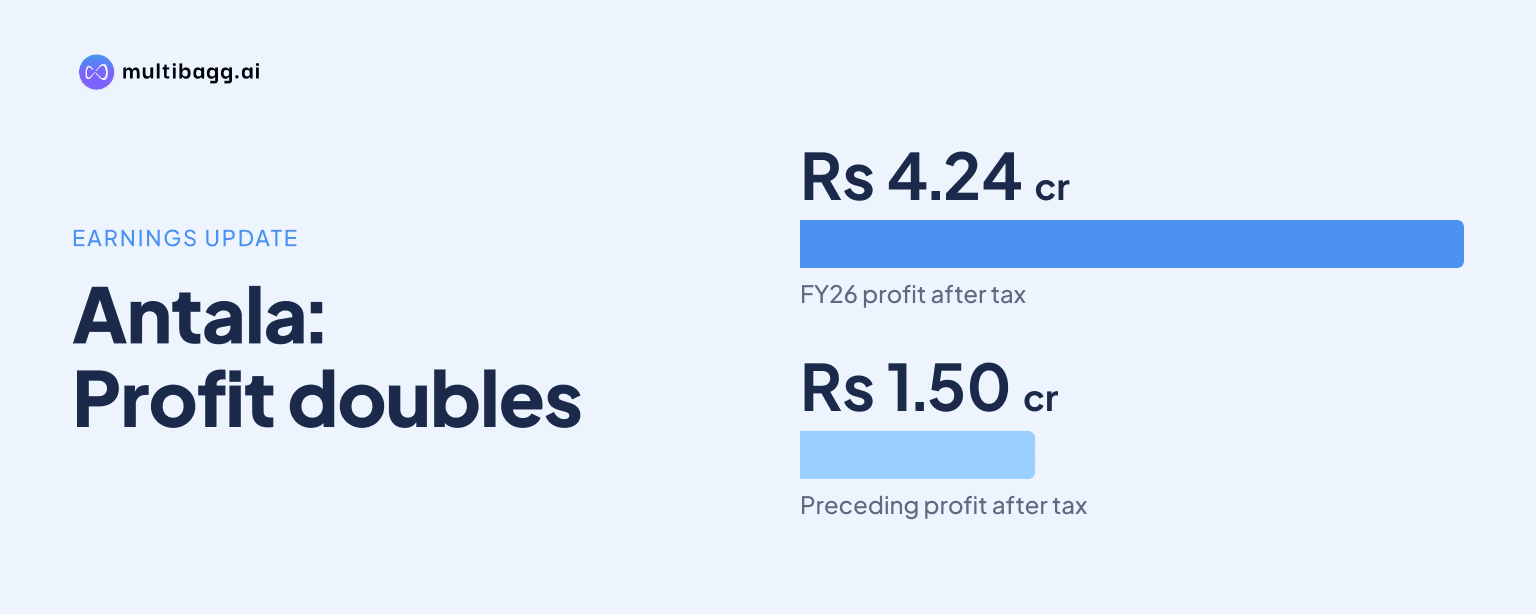
Antala Industries Limited reported restated profit after tax of Rs 4.2363 crore for the year ended March 31, 2026, more than twice Rs 1.5005 crore in the preceding reported period. Antala nevertheless recorded a Rs 4.8826 crore operating cash outflow in FY26 as inventory, receivables and advances absorbed more cash than operating profit generated.
Why did Antala FY26 profit rise while operating cash fell?
Antala’s FY26 profit rose because reported revenue and profit expanded, while operating cash fell because profit is calculated on an accrual basis before movements in working capital. Revenue from operations reached Rs 47.4047 crore in FY26, compared with Rs 25.0221 crore for the period from August 5, 2024 to March 31, 2025. Profit before tax increased to Rs 5.6610 crore from Rs 2.1456 crore, and profit after tax reached Rs 4.2363 crore after current tax of Rs 1.4282 crore and a deferred-tax benefit of Rs 3.40 lakh.
The comparison is not between two full financial years. FY26 covers the 12 months ended March 31, 2026, whereas the prior reported period covers August 5, 2024 to March 31, 2025. The restated statement also records profit after tax of Rs 88.57 lakh for the year ended March 31, 2024, before the company’s August 2024 conversion period.
Antala recognises sales on an accrual basis after goods are transferred and ownership and significant risk pass to the customer, provided revenue can be measured reliably and economic benefits are probable. Its FY26 operating profit before working-capital changes was Rs 6.2752 crore, including adjustments of Rs 39.73 lakh for depreciation and amortisation and Rs 30.09 lakh for finance cost. Cash flow from operations then reflects when operating assets and liabilities change, rather than solely when revenue is recognised.
What caused Antala’s Rs 4.8826 crore operating cash outflow?
Antala’s FY26 operating cash outflow was principally driven by inventory, short-term loans and advances, and trade receivables. Inventory used Rs 7.2182 crore of cash, movement in short-term loans and advances used Rs 3.5938 crore, and trade receivables used Rs 1.6530 crore. Together, those three movements consumed Rs 12.4650 crore, exceeding the Rs 6.2752 crore operating profit before working-capital changes.
Inventory was the largest individual cash use in FY26. Antala’s inventory balance rose from Rs 6.7050 crore at March 31, 2025 to Rs 13.9232 crore at March 31, 2026, while the cash-flow statement records a Rs 7.2182 crore outflow from inventories. Antala defines its operating cycle, the time between acquiring assets for processing and realising cash, as 12 months; inventories are classified as current assets under that policy.
Short-term loans and advances increased from Rs 1.3538 crore at March 31, 2025 to Rs 4.9476 crore at March 31, 2026. Trade receivables increased from Rs 3.5269 crore to Rs 5.1799 crore over the same dates. At March 31, 2026, the combined Rs 24.0507 crore balance of inventory, receivables and advances represented about 98% of Rs 24.4423 crore in current assets excluding cash and cash equivalents.
Got a follow-up? Ask IRIS
Did supplier credit offset Antala’s working-capital needs?
Higher supplier credit partly offset Antala’s working-capital cash demands, but it was insufficient to cover the three main operating-asset movements. Trade payables supplied Rs 1.4672 crore of FY26 operating cash, other current liabilities supplied Rs 6.96 lakh, and short-term provisions supplied Rs 2.70 lakh. These inflows were materially below the Rs 12.4650 crore cash use from inventory, receivables and advances.
Trade payables due to creditors other than micro enterprises and small enterprises rose from Rs 3.5111 crore at March 31, 2025 to Rs 4.9783 crore at March 31, 2026. Other current liabilities rose from Rs 16.13 lakh to Rs 23.09 lakh, while short-term provisions rose from Rs 50.54 lakh to Rs 1.9247 crore. The cash-flow statement separately includes Rs 1.16 lakh of income-tax and other adjustments in FY26.
The conversion from operating profit to operating cash quantifies the dependency on balance-sheet movements. From Rs 6.2752 crore of operating profit before working-capital changes, Antala moved to a Rs 4.8826 crore operating outflow after changes in operating assets, operating liabilities and tax-related adjustments. Positive operating cash at a similar level of operating profit would require smaller increases in inventory, receivables and advances, larger offsetting liability movements, or both.
How did Antala fund its FY26 cash deficit?
Antala funded its FY26 operating and investing cash deficit chiefly through financing inflows, although cash and cash equivalents declined by Rs 1.7050 crore. Financing activities generated Rs 4.9542 crore, comprising Rs 4.3507 crore of changes in equity and Rs 1.0498 crore from short-term borrowings. Those sources were reduced by Rs 14.54 lakh of long-term borrowing repayment and Rs 30.09 lakh of finance-cost payment.
Investing activities used Rs 1.7767 crore in FY26. The outflow included Rs 1.7715 crore for net purchase or sale of fixed assets and Rs 8.93 lakh for movement in long-term investments, partly offset by Rs 8.40 lakh of interest income. Cash and cash equivalents fell from Rs 2.5871 crore at the start of FY26 to Rs 88.21 lakh at March 31, 2026, comprising Rs 15.35 lakh in cash and Rs 72.86 lakh in current accounts.
The subsequent six-month period ended September 30, 2026 had a different financing profile. Antala generated Rs 1.1518 crore from operating activities but used Rs 1.5974 crore in financing activities, including a Rs 2.9046 crore reduction in short-term borrowings. Changes in equity added Rs 95.49 lakh and long-term borrowings increased by Rs 46.91 lakh, but cash and cash equivalents still declined to Rs 46.51 lakh.
What do the September 2026 figures show about cash conversion?
Antala reported positive operating cash flow of Rs 1.1518 crore for the six months ended September 30, 2026, but the result remained affected by working-capital movements. Operating profit before working-capital changes was Rs 5.8523 crore. Inventory used Rs 4.0415 crore and receivables used Rs 3.1936 crore, while trade payables supplied Rs 3.0491 crore and movement in short-term loans and advances supplied Rs 6.64 lakh.
The half-year result does not establish a full-year cash-conversion pattern. Inventory increased from Rs 13.9232 crore at March 31, 2026 to Rs 17.9647 crore at September 30, 2026, and trade receivables increased from Rs 5.1799 crore to Rs 8.3735 crore. Trade payables also increased from Rs 4.9783 crore to Rs 8.0275 crore, providing a significant offset to the cash tied up in operating assets.
Conclusion
Antala’s restated FY26 figures show a divergence between reported earnings and cash generation. Revenue from operations reached Rs 47.4047 crore and profit after tax was Rs 4.2363 crore, but operating cash flow was negative Rs 4.8826 crore because the Rs 12.4650 crore cash use from inventory, receivables and advances outweighed operating profit and supplier-credit inflows.
The next reported figures should show whether the September 30, 2026 operating inflow of Rs 1.1518 crore can persist while inventory and receivables remain elevated. Antala disclosed no separate working-capital reduction plan in the supplied financial information; inventory was Rs 17.9647 crore, receivables were Rs 8.3735 crore and cash and cash equivalents were Rs 46.51 lakh at September 30, 2026.