










M. K. Sons Fine Jewels Limited Restates Qualified 2024 Audit
Key highlights
- M. K. Sons Fine Jewels recorded an employee retirement-benefit provision under Ind AS 19 in its IPO restatement of the March 31, 2024 accounts.
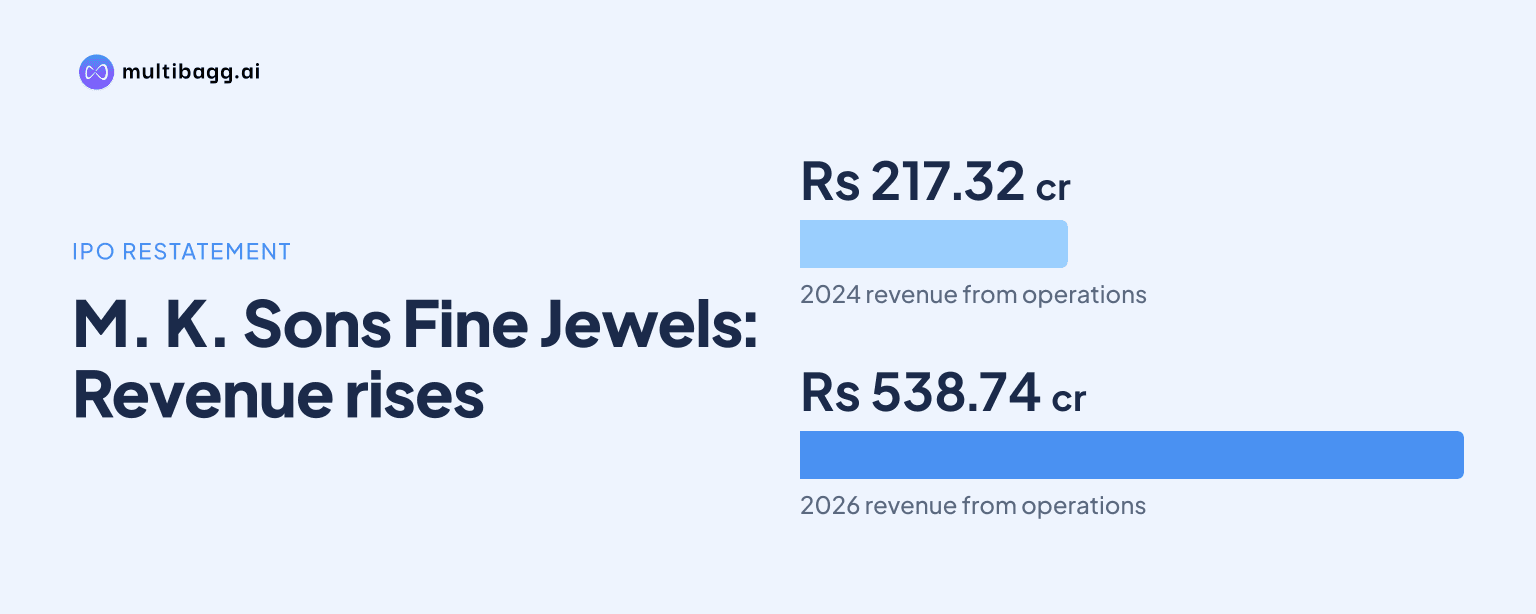
- Revenue from operations increased from Rs 217.323 crore in fiscal 2024 to Rs 538.736 crore in fiscal 2026.
- Restated profit after tax rose from Rs 8.167 crore in fiscal 2024 to Rs 51.799 crore in fiscal 2026.
- Total provisions increased from Rs 2.260 crore at March 31, 2024 to Rs 11.250 crore at March 31, 2026, although the retirement-benefit share was not identified.
powered by IRIS
M. K. Sons Fine Jewels Limited restated the matters behind its qualified March 31, 2024 audit by recording employee retirement-benefit provision under Indian Accounting Standard 19, or Ind AS 19. The earlier auditor did not quantify the missing provision or balance-related concerns, while the IPO restatement was examined on October 5, 2026.
Why was the 2024 audit qualified?
M. K. Sons Fine Jewels’ March 31, 2024 Indian generally accepted accounting principles, or Indian GAAP, audit was qualified because it had not made adequate provision for post-employment defined-benefit obligations. Parmar & Company, Chartered Accountants, issued the qualified opinion on September 29, 2024, identifying the omission as a departure from applicable accounting standards.
The retirement-benefit matter concerned obligations payable after employees leave service. The September 2024 audit report did not quantify the financial effect of the missing provision for the year ended March 31, 2024, so the disclosed information does not establish the amount by which original profit, provisions, liabilities or equity were affected.
The previous auditor also referred, without quantification, to outstanding balances of debtors, creditors, assets and liabilities. M. K. Sons Fine Jewels’ restated March 31, 2024 statement reports total assets of Rs 95.211 crore, total equity of Rs 22.290 crore and total liabilities of Rs 72.920 crore, but it does not allocate the effects of the qualified matters among those line items.
A qualified opinion differs from the later audit outcomes because the previous auditor identified a specific departure from standards in the March 2024 Indian GAAP accounts. The October 5, 2026 examination report states that the September 29, 2024 audit report remains authoritative for the underlying Indian GAAP financial statements and was not replaced or re-dated.
How did M. K. Sons Fine Jewels restate the qualified 2024 audit?
M. K. Sons Fine Jewels addressed the qualified 2024 audit by making appropriate provision for employee retirement benefits in its special-purpose restated Ind AS financial statements. The provision was included as an Ind AS adjustment under Ind AS 19, Employee Benefits, using accounting policies applied consistently with the three-month period ended June 30, 2026.
The work formed part of the conversion of the March 31, 2024 and March 31, 2025 audited Indian GAAP accounts into special-purpose restated Ind AS accounts for the proposed initial public offering, or IPO. Ind AS is the Indian Accounting Standards framework, while Indian GAAP in this disclosure refers to accounting standards notified under Section 133 of the Companies Act, 2013 that applied to the earlier accounts.
Paresh Rakesh & Associates LLP independently examined the conversion adjustments because Parmar & Company had not examined the Ind AS adjustments or issued an examination report on them. Its procedures included evaluating re-measurements and reclassifications, checking arithmetic accuracy, reconciling restated figures to audited Indian GAAP figures and obtaining management representations.
Paresh Rakesh & Associates LLP also verified that adjustments for the qualified matters had been incorporated where applicable. For the debtors, creditors, assets and liabilities cited by the previous auditor, the October 5, 2026 report says appropriateness was confirmed through alternate audit procedures, rather than stating that the underlying March 2024 accounts had been re-audited.
Got a follow-up? Ask IRIS
What do the restated figures show from 2024 to 2026?
M. K. Sons Fine Jewels’ restated statements show rising revenue and profit from March 2024 to March 2026, while separately presenting gratuity provisions in operating cash flow. Revenue from operations increased from Rs 217.323 crore in the year ended March 31, 2024 to Rs 538.736 crore in the year ended March 31, 2026, and restated profit after tax rose from Rs 8.167 crore to Rs 51.799 crore.
The cash-flow statement records gratuity provision of Rs 7.4 lakh for March 2024, Rs 10.8 lakh for March 2025 and Rs 27.3 lakh for March 2026. These figures cannot quantify the original qualification because the disclosure does not say they equal the previously unprovided retirement-benefit obligation or identify the full restatement effect.
M. K. Sons Fine Jewels’ total provisions rose from Rs 2.260 crore at March 31, 2024 to Rs 11.250 crore at March 31, 2026. The March 2024 balance comprised Rs 1.66 crore of non-current provisions and Rs 0.60 crore of current provisions, whereas the March 2026 balance comprised Rs 7.45 crore and Rs 3.80 crore respectively; neither statement identifies the retirement-benefit share.
What does the restatement not establish?
M. K. Sons Fine Jewels’ restatement does not make the original March 2024 audit opinion unqualified. The examiner reported that the restated financial information gave effect to matters causing the modification, but specifically said the report should not be construed as a reissuance, re-dating or new opinion on any previous audit report.
The October 5, 2026 report also does not reflect events occurring after the dates of the special-purpose interim and restated financial statements. Paresh Rakesh & Associates LLP stated that it had no responsibility to update its report for later events or circumstances, limiting its work to the information examined for the IPO document.
The underlying audit reports for the March 31, 2025 Indian GAAP financial statements, March 31, 2026 Ind AS financial statements and the three-month period ended June 30, 2026 special-purpose interim Ind AS financial statements were unmodified. That makes March 2024 the disclosed exception among the four presented reporting periods, but it does not supply a value for the original deficiency.
Why does the scope of the examination matter?
M. K. Sons Fine Jewels’ examination report was prepared for inclusion in the updated draft red herring prospectus or red herring prospectus in connection with the IPO. The report was issued under Section 26 of the Companies Act, 2013, the Securities and Exchange Board of India (Issue of Capital and Disclosure Requirements) Regulations, 2018, and the Institute of Chartered Accountants of India guidance note on reports in company prospectuses.
For March 2024 and March 2025, Paresh Rakesh & Associates LLP restricted its examination to Ind AS adjustments made to audited Indian GAAP accounts. This distinction matters because the firm took responsibility for the restated Ind AS information after independent procedures, while the original Indian GAAP audit reports dated September 29, 2024 and September 3, 2025 remained the authoritative reports for their respective underlying statements.
Conclusion
M. K. Sons Fine Jewels disclosed a defined response to the March 2024 qualified opinion: it recorded employee retirement-benefit provision under Ind AS 19, incorporated the relevant adjustments into restated financial information and used alternate procedures for specified outstanding balances. The remaining uncertainty is quantitative, because the original audit report did not state the amount of the missing provision or balance-related effects.
The next financial-reporting point is whether later disclosures continue to identify employee-benefit obligations and balance assessment under the accounting policies used for the June 30, 2026 period. The October 5, 2026 examination supports the IPO restatement for that stated purpose, while leaving the original March 2024 Indian GAAP audit report in force.