










IZMO Limited auditor flags balances and foreign-account reliance
Key highlights
- IZMO’s auditor said four balance categories were subject to confirmation and reconciliation at September 30, 2026.
- Foreign subsidiaries reported Rs 99.4382 crore of revenue through management-certified accounts for the half year ended September 30, 2026.
- IZMO reported consolidated half-year revenue of Rs 131.7337 crore and net profit after tax of Rs 24.6944 crore.
- Consolidated trade receivables rose by Rs 15.355 crore to Rs 144.4083 crore at September 30, 2026.
powered by IRIS
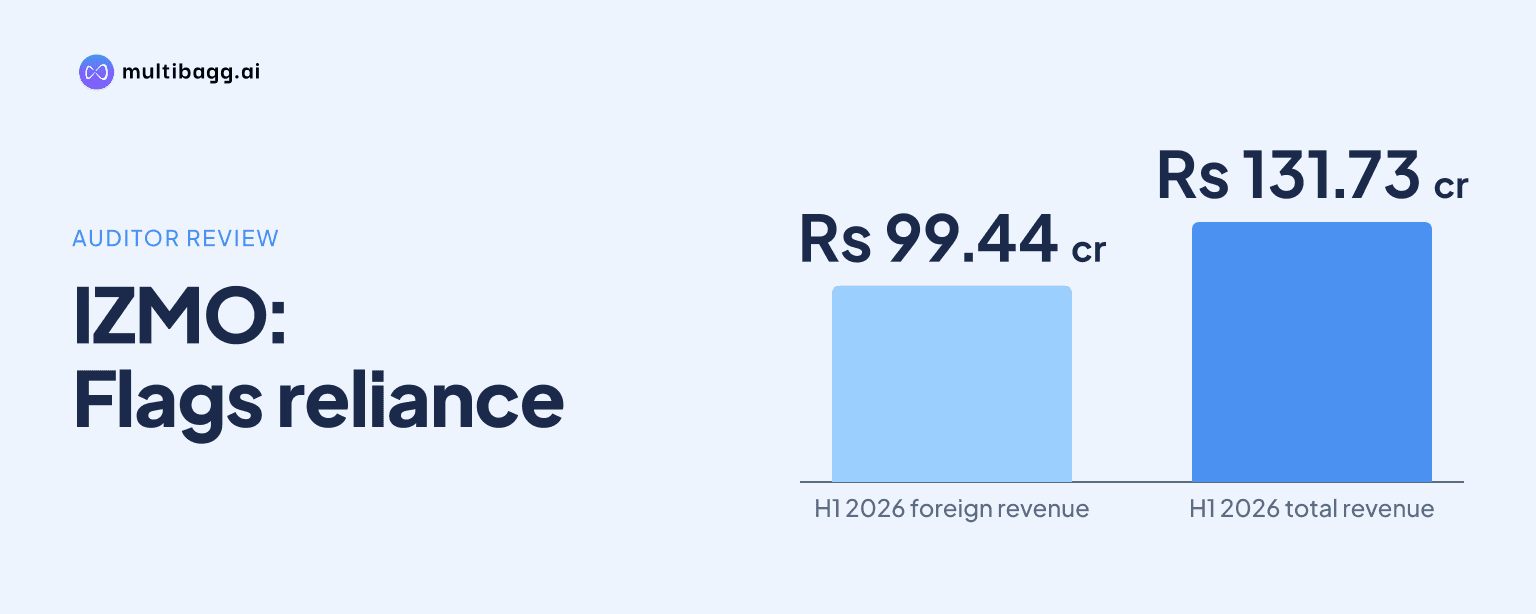
IZMO Limited’s auditor said four balance categories remained subject to confirmation and reconciliation at September 30, 2026, while foreign subsidiaries contributing Rs 99.4382 crore of half-year revenue were included through management-certified accounts. The November 13, 2026 limited-review reports nevertheless said nothing had come to the auditor’s attention indicating a material misstatement.
Know IZMO inside out
Results, valuation, peers and who's buying, in one view.
What did IZMO’s auditor flag in the limited review?
IZMO’s auditor flagged sundry debtors, inventories, loans and advances, and current liabilities as subject to confirmation and reconciliation in the standalone review for the quarter ended September 30, 2026. The consolidated review dated November 13, 2026 uses the same wording, placing the issue in both the standalone and group-level reporting.
The reports do not quantify the amount within any of the four categories that awaits confirmation or reconciliation. They also do not disclose a deadline for completing that work, a proposed accounting adjustment, or a specific counterparty connected with the balance-confirmation matter.
At the standalone level, trade receivables were Rs 33.8938 crore at September 30, 2026, compared with Rs 26.7194 crore at March 31, 2026. Standalone current liabilities were Rs 19.4099 crore, up from Rs 12.884 crore over the same six-month balance-sheet comparison.
The auditor did not describe the identified balances as errors, fraud, or a qualification to the results. In the November 13, 2026 standalone conclusion, the auditor said nothing had come to attention that suggested non-compliance with applicable Indian Accounting Standards, or Ind AS, required disclosures, or a material misstatement in the September-quarter statement.
How much of IZMO’s consolidated result relied on management-certified accounts?
IZMO’s consolidated results for April 1, 2026 to September 30, 2026 included foreign-subsidiary results based on management-certified accounts, with those subsidiaries reporting Rs 99.4382 crore of revenue and Rs 25.0063 crore of net profit after tax. The group reported consolidated revenue of Rs 131.7337 crore and net profit after tax of Rs 24.6944 crore for that half year.
The foreign-subsidiary revenue was lower than the group’s Rs 131.7337 crore revenue, whereas the foreign-subsidiary net profit after tax exceeded the group’s Rs 24.6944 crore result. The filing does not provide a line-by-line reconciliation between the foreign operations and the consolidated figures, including the effect of the parent, the Indian subsidiary, or consolidation eliminations.
The foreign-subsidiary list includes Izmo Europe BVBA, Izmo Inc, US, Midrange Software Pte Ltd., Izmo France SARL, Frog Data LLC, Groupe Izmo, Izmo Cars Ltd, Izmo Holdings UK Ltd, Izmo Digital and Izmo Technologies GmbH. The report also records that Izmo Consulting was dissolved on April 30, 2026, but gives no separate revenue, asset, liability or profit figure for that entity.
What assurance does IZMO’s limited review provide?
IZMO’s limited review provides moderate assurance rather than an audit opinion, because the auditor said the procedures were primarily inquiries of company personnel and analytical review procedures. The report cites Standard on Review Engagements 2410, covering a review of interim financial information by the independent auditor of the entity.
The auditor expressly stated that no audit had been performed for the quarter ended September 30, 2026 and therefore no audit opinion was expressed. That distinction applies to the standalone report and to the consolidated review issued on November 13, 2026.
For the consolidated results, the auditor said the foreign subsidiaries’ financial results and other financial information had not been subjected to review. The auditor added that the conclusion relating to those subsidiaries was based solely on the unaudited financial results and other unaudited information provided by management for the April-to-September 2026 period.
Despite those stated limitations, the consolidated limited-review conclusion said nothing had come to the auditor’s attention indicating that the results failed to meet applicable Ind AS or Regulation 33 disclosure requirements, or contained a material misstatement. This conclusion covers the consolidated half-year profit after tax of Rs 24.6944 crore, but does not amount to an independent audit of each foreign subsidiary’s records.
Got a follow-up? Ask IRIS
Which balance-sheet movements provide context for the confirmation issue?
IZMO’s consolidated trade receivables rose to Rs 144.4083 crore at September 30, 2026 from Rs 129.0533 crore at March 31, 2026, an increase of Rs 15.355 crore. Consolidated inventories increased to Rs 0.8617 crore from Rs 0.2959 crore during the same period.
Consolidated current liabilities increased to Rs 88.9597 crore at September 30, 2026 from Rs 75.1401 crore at March 31, 2026. Trade payables other than to micro and small enterprises rose to Rs 13.7244 crore from Rs 7.051 crore, while other current liabilities increased to Rs 64.1914 crore from Rs 54.2361 crore.
The reported movements give scale to the balance-sheet categories identified in the review, but the filing does not say that a specific increase is unreconciled or unconfirmed. The auditor did not attach a quantified adjustment to the Rs 532.3873 crore consolidated balance sheet as at September 30, 2026.
The consolidated cash-flow statement reported an Rs 15.355 crore increase in trade receivables and an Rs 25.8765 crore increase in short-term loans and advances for the half year ended September 30, 2026. It also recorded an Rs 13.8354 crore increase in current liabilities and provisions, while net cash from operating activities was Rs 7.3857 crore, compared with Rs 3.8719 crore a year earlier.
How did IZMO’s consolidated half-year performance change?
IZMO’s consolidated revenue from operations increased to Rs 131.7337 crore in the half year ended September 30, 2026 from Rs 116.6163 crore a year earlier. Consolidated net profit after tax increased to Rs 24.6944 crore from Rs 18.5632 crore in the corresponding half year.
The group’s total expenses rose to Rs 108.4949 crore from Rs 102.8596 crore, while employee benefit expense increased to Rs 58.2317 crore from Rs 55.9312 crore. Other expenses rose to Rs 36.6763 crore from Rs 34.1744 crore, and finance cost increased to Rs 0.9739 crore from Rs 0.8256 crore.
Profit before tax was Rs 25.3266 crore for the September 2026 half year, compared with Rs 19.1683 crore in the September 2025 half year. These consolidated performance figures include the foreign-subsidiary results for which the auditor relied on management-certified accounts.
Conclusion
The September 30, 2026 filing identifies two defined limitations in IZMO’s interim reporting: balances covering debtors, inventories, loans and advances, and current liabilities remained subject to confirmation and reconciliation, while foreign subsidiaries reporting Rs 99.4382 crore of revenue were consolidated from management-certified, unreviewed accounts. The auditor nevertheless issued an unmodified limited-review conclusion rather than an audit opinion.
What to watch next is whether IZMO discloses completion of the pending confirmations and reconciliations, or any related adjustment, in a subsequent filing. The November 13, 2026 reports set no timetable for resolving those matters, and the April 30, 2026 dissolution of Izmo Consulting remains the only disclosed change to the listed foreign-subsidiary structure.