










JD Cables Sets ₹400-500 Crore FY27 Outlook After EPC Exit
Key highlights
- JD Cables reported H1 FY27 total income of ₹167.89 crore, up 38.25% year on year.
- H1 FY27 profit after tax was ₹12.29 crore, up 3.08%, with a 7.32% net profit margin.
- JD Cables expects FY27 revenue of ₹400-500 crore after deciding not to take further EPC work.
- JD Cables proposes to raise up to ₹100 crore through a QIP or preferential issue, subject to approvals.
powered by IRIS
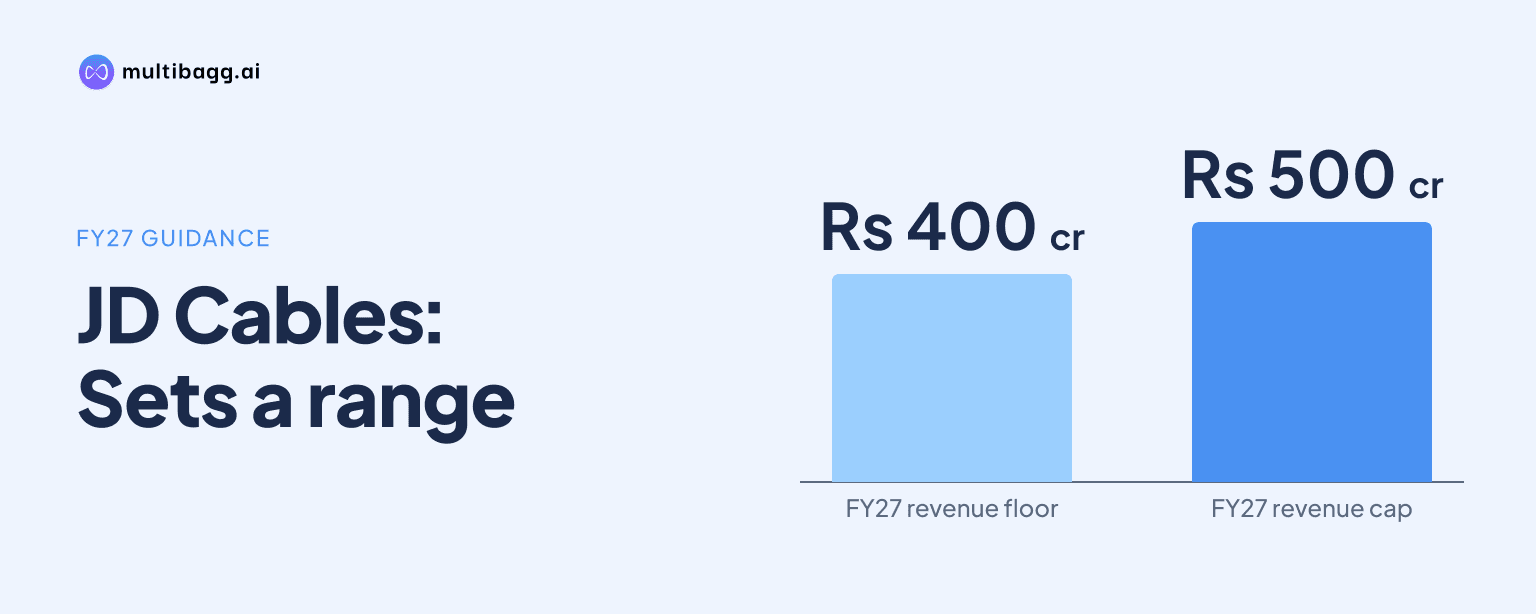
JD Cables Limited set a ₹400-500 crore FY27 revenue outlook after deciding to stop taking further EPC work, having reported H1 FY27 total income of ₹167.89 crore, up 38.25% year on year. The change puts the manufacturer’s focus on cables and conductors while it expands production capacity and considers raising up to ₹100 crore.
Know JD Cables inside out
Results, valuation, peers and who's buying, in one view.
Why is JD Cables exiting EPC work?
JD Cables said it has decided not to undertake further engineering, procurement and construction, or EPC, work. Management disclosed during its November 19 earnings call that it had booked around ₹60 crore of EPC revenue in the first half of FY27 and expected about ₹50 crore in the second half.
The decision marks a shift towards the company’s core manufacturing operations in cables and conductors. Management did not provide a detailed financial bridge for the effect of the EPC exit on margins or the precise mix of its full-year target. It did, however, cite ₹400 crore from cables and conductors in one response, within its broader FY27 guidance range of ₹400-500 crore.
The management commentary reflected demand opportunities in power transmission and distribution, but it was also cautious on profitability. It indicated that profit-after-tax margins in cables were around 8%-9%, while external commentary on the call noted expectations for margins to remain broadly flat to similar levels.
What were JD Cables' H1 FY27 financial results?
JD Cables reported total income of ₹167.89 crore for the six months ended September 2026, a 38.25% increase from a year earlier. Profit after tax was ₹12.29 crore, up 3.08%, resulting in a net profit margin of 7.32%.
The gap between income growth and profit growth was accompanied by a lower EBITDA margin. The investor-presentation summary reported EBITDA of ₹21.86 crore and an EBITDA margin of about 13.0%, compared with about 15.9% in H1 FY26. Reported increases in employee expenses, other expenses, finance costs and depreciation weighed on the pace of profit growth.
One third-party assessment of the call said debt had risen to approximately ₹118 crore and finance costs had more than doubled year on year. JD Cables did not provide those figures in the quoted management opening remarks. Investors should therefore rely on the company’s statutory financial statements and future disclosures for a fuller view of borrowings, interest costs and cash flow.
How is JD Cables expanding its manufacturing operations?
JD Cables acquired an industrial facility of approximately 1.18 lakh square feet at Dankuni, West Bengal, during H1 FY27. The company said the acquisition expanded its installed production capacity and would support larger customer requirements.
The company began its conductor division in July 2026 and its cable operations at the expanded facility in September 2026. Management said the business serves power utilities and infrastructure projects across more than 15 states and holds vendor approvals from various state electricity boards.
Its existing portfolio includes power cables, control cables, single-service wires and aluminium conductors, including AAC, AAAC and ACSR products. JD Cables also plans to broaden its offering with MVCC AL59 HTLS conductors and high-tension cables, which are intended for power transmission and distribution requirements.
Got a follow-up? Ask IRIS
What does the proposed ₹100 crore fundraise mean for investors?
JD Cables has proposed raising up to ₹100 crore through a qualified institutional placement or a preferential issue, subject to required approvals. Management said the proposed capital raise would position the company to address demand across transmission and distribution networks and support its enlarged manufacturing base.
The company did not specify the final route, timing, issue price, investor participation or a detailed allocation of proceeds during the quoted call remarks. These unresolved details are material because the chosen structure could affect shareholder dilution, while the deployment of capital will shape the financial contribution of the new facilities and product additions.
The proposal comes as the company scales capacity and shifts away from EPC projects. The simultaneous focus on manufacturing expansion and funding means execution, working-capital management and the pace of utilisation will remain relevant operating measures alongside reported revenue growth.
How does the strategy change affect JD Cables' FY27 outlook?
JD Cables' ₹400-500 crore FY27 guidance combines an H1 total income base of ₹167.89 crore with a manufacturing-led plan for the rest of the year. Management expects around ₹50 crore of EPC revenue in H2 but has ruled out additional EPC work thereafter.
The stated strategy places cables and conductors at the centre of future growth, supported by the Dankuni facility, new divisions and product expansion. Yet H1 figures show that higher income did not translate into a proportionate increase in net profit, with PAT rising 3.08% and EBITDA margin declining to about 13.0%.
For investors, the key reported factors are the company’s ability to execute its order book, ramp up the new capacity and maintain financial discipline as finance costs and depreciation rise. The available information does not establish a target for future margin improvement, and management’s commentary did not give a detailed profitability outlook.
Conclusion
JD Cables has reported stronger H1 FY27 income while resetting its operating model around manufacturing rather than new EPC contracts. The ₹167.89 crore half-year income, ₹12.29 crore profit after tax and ₹400-500 crore FY27 outlook show the scale of management’s growth plan, but the lower EBITDA margin and modest profit growth underline the importance of cost and execution performance.
The next points to watch are the expected H2 EPC revenue of around ₹50 crore, utilisation of the Dankuni capacity, progress in new conductor and cable products, and approvals and terms for the proposed fundraise of up to ₹100 crore. JD Cables has also indicated that it will focus on executing its order book and extending its supply presence across power transmission and distribution customers.