










K2 Infragen H1 revenue falls to Rs 63 crore, loss follows
Key highlights
- H1 FY'27 revenue was Rs 63 crore, compared with Rs 91 crore in H1 FY'26.
- H1 FY'27 EBITDA fell to Rs 1.3 crore from Rs 14 crore, and EBITDA margin was about 2%.
- K2 Infragen reported a Rs 4 crore H1 FY'27 net loss and finance cost of about Rs 6 crore.
- Unexecuted order book was about Rs 907 crore at September 2026, up 114% from March 2026.
powered by IRIS
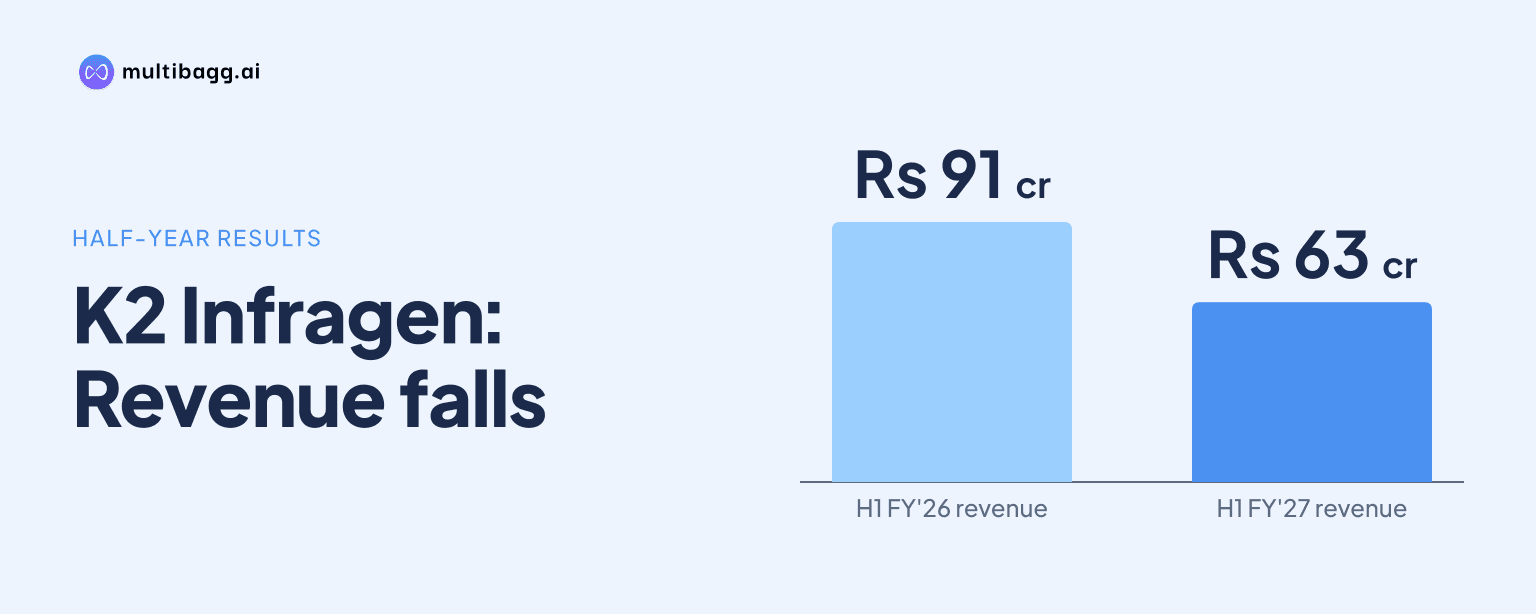
K2 Infragen Limited reported H1 FY'27 revenue of Rs 63 crore for the six months ended September 30, 2026, down from Rs 91 crore a year earlier, while EBITDA fell to Rs 1.3 crore and the company posted a Rs 4 crore net loss. Management attributed the decline to supply disruptions, delayed execution and higher input costs.
Know K2 Infragen inside out
Results, valuation, peers and who's buying, in one view.
Why did K2 Infragen's H1 FY'27 revenue fall?
K2 Infragen's H1 FY'27 revenue fell because supply-chain disruptions during the war delayed project execution and delivery, slowing revenue recognition. Revenue from operations declined by Rs 28 crore to Rs 63 crore in the six months ended September 30, 2026, from Rs 91 crore in H1 FY'26, a year-on-year reduction of about 31%.
Management said the disruption affected the pace of execution rather than pointing to a shortage of work. K2 Infragen had 11 ongoing projects across its railway infrastructure, power transmission, roads and bridges, water supply, civil infrastructure and renewable-energy verticals, and operates across 10 states. Its fleet of more than 70 construction machines did not prevent delivery delays from affecting H1 FY'27 revenue recognition.
The revenue decline came while new direct orders were at an early stage of execution. Management said these projects could contribute to later-period revenue once work gathers momentum, but it did not provide a revenue target for H2 FY'27. The company reported an on-time delivery rate of 83% in FY'26, providing a historical measure of execution before the H1 FY'27 disruption.
How much did K2 Infragen's profitability decline?
K2 Infragen's earnings before interest, tax, depreciation and amortisation, or EBITDA, fell to Rs 1.3 crore in H1 FY'27 from Rs 14 crore in H1 FY'26, with EBITDA margin at about 2%. Management attributed the Rs 12.7 crore operating-profit decline to lower execution volumes and raw-material costs rising faster than the contractual escalation mechanism.
The company said its project contracts use a wholesale price index, or WPI, linked escalation mechanism, while actual raw-material inflation had been substantially higher than the escalation received. Management said the government was reevaluating the mechanism because of this gap and that it expects applicable benefits in a coming period. It did not disclose the potential value or timing of any recovery.
Below EBITDA, finance cost was about Rs 6 crore in H1 FY'27, reflecting use of working-capital facilities for project requirements. Management said low operating performance and higher finance cost resulted in the Rs 4 crore first-half loss. Depreciation and amortisation were broadly in line with earlier periods, reflecting investment in construction equipment used across the project portfolio.
An investor also asked about other expenses of Rs 4.4 crore during the November 16, 2026 call. Management said the category included taxes, business-development spending, rentals, enterprise resource planning software expenses, corporate social responsibility costs and royalty payments to joint-venture partners. It also said it had made a provision of about Rs 1.5 crore for trade receivables on a prudent basis.
Got a follow-up? Ask IRIS
What does K2 Infragen's higher debt show about working capital?
K2 Infragen reported total debt of Rs 129 crore and net worth of about Rs 86 crore as of September 2026, producing a debt-to-equity ratio of about 1.5 times. Management said borrowings increased mainly because working-capital needs rose with project execution, rather than identifying a separate acquisition or expansion transaction.
Part of the higher borrowing funded vendor advances for transformers needed in railway infrastructure work. Management said transformer deliveries were expected over the next three months of FY'27, after which the related revenue could be recognised when delivery and project-progress criteria are met. That sequence leaves cash committed before equipment delivery can support execution and billing.
During the call, an investor cited debtor days of nearly 230 days. Management said debtor days had reduced compared with an earlier period, but did not give a comparable figure. It said railway and transmission work requires advance payments for specialised equipment, with a three-to-four-month gap before material is delivered and converted into a letter of credit, or LC.
K2 Infragen said it has begun seeking customer advances and using non-fund-based bank guarantees on direct orders, after relying less on such arrangements for earlier indirect orders. It reported receiving one advance and said more could be obtained as approvals, right-of-way clearances and ground clearances are completed. Acuite Ratings & Research assigned ACUITE BBB- with a stable outlook to long-term facilities and ACUITE A3 to short-term facilities covering about Rs 200 crore.
Can K2 Infragen's order book support H2 FY'27 recovery?
Management expects H2 FY'27 financial performance to improve if newly secured projects progress into active execution, but this remains management's expectation rather than reported performance. K2 Infragen's unexecuted order book was about Rs 907 crore as of September 2026, up 114% from March 2026, while its live roads and railways bid pipeline was about Rs 560 crore.
The company said awards since March 2026 totalled about Rs 606 crore across roads, railways and power transmission. These included a Rs 390.91 crore Telangana project to construct, upgrade, strengthen and maintain selected rural roads under the Hybrid Annuity Model, or HAM, and a Rs 158.58 crore Konkan Railway electric-traction upgrade order, including goods and services tax.
Management told an investor that the Rs 907 crore order book generally has to be completed within a maximum of 36 months, while some railway and transmission projects have 24-month deadlines. Railway and transmission account for about 38% of the order book, according to management. The company has appointed a senior vice-president for railway and transmission projects to lead that specialised activity.
K2 Infragen is also evaluating battery energy storage systems, or BESS, and build-operate-transfer opportunities. Management said it has bid for three to four BESS projects in Rajasthan and signed a memorandum of understanding with Map Power for product pricing. These activities are prospective opportunities, not secured revenue, and management gave no value or timetable for their contribution.
Conclusion
K2 Infragen's H1 FY'27 outcome reflects the combined effect of delayed project execution, input-cost escalation and higher financing needs. Revenue fell by Rs 28 crore year on year, EBITDA fell by Rs 12.7 crore and finance cost reached about Rs 6 crore, while transformer advances and broader project working-capital needs lifted total debt to Rs 129 crore.
The next disclosed checkpoints are transformer deliveries over the following three months of FY'27, conversion of early-stage direct awards into execution, and progress toward management's expected H2 FY'27 improvement. Investors can also watch for any outcome from the government review of WPI-linked escalation and developments in the income-tax proceeding following the August 13 notice and K2 Infragen's October 10 block tax-return filing.