










Kaynes Technology restates FY26 results and borrowing balances
Key highlights
- Kaynes Technology restated consolidated FY26 profit to Rs 391.517 crore from Rs 363.890 crore.
- Consolidated FY26 revenue increased by Rs 54.582 crore to Rs 3,680.936 crore after restatement.
- Short-term borrowings at 31 March 2026 were restated up by Rs 466.909 crore to Rs 1,004.850 crore.
- Standalone FY26 profit was restated down by Rs 72.132 crore to Rs 181.974 crore.
powered by IRIS
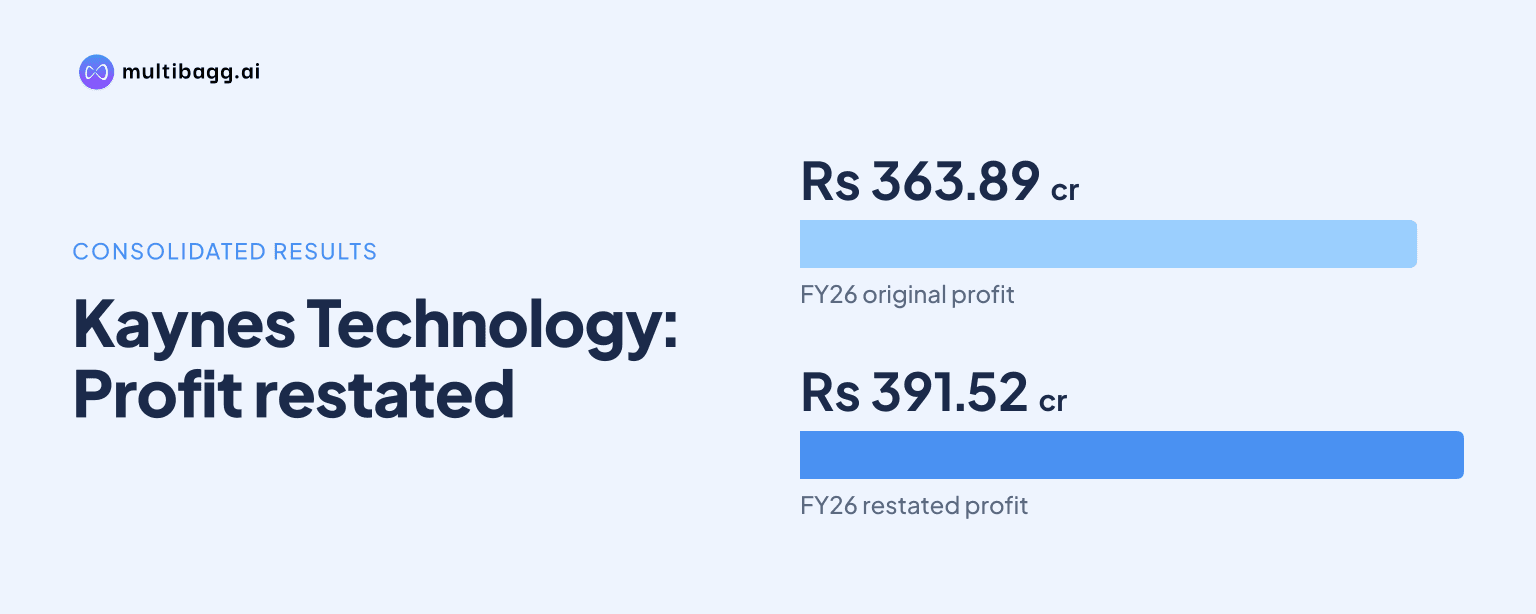
Kaynes Technology India Limited restated FY26 consolidated profit to Rs 391.517 crore from Rs 363.890 crore and short-term borrowings at 31 March 2026 to Rs 1,004.850 crore from Rs 537.941 crore after identifying material prior-period accounting errors. The corrections were disclosed on 14 November 2026 under Indian Accounting Standard 8, or Ind AS 8.
Know Kaynes Technology India inside out
Results, valuation, peers and who's buying, in one view.
What did Kaynes Technology restate in its accounts?
Kaynes Technology retrospectively restated comparative standalone and consolidated information for the quarter ended 30 June 2026, the quarter and six months ended 30 September 2025, the year ended 31 March 2026 and opening balances at 1 April 2025. The company said the corrections addressed material prior-period errors in accordance with Ind AS 8, which covers accounting policies, changes in estimates and errors.
The changes extended beyond reclassification. Kaynes Technology reversed revenue on certain sales where customer control had not transferred by the reporting date, corrected excess overheads capitalised in inventory, recorded provisions for slow-moving and non-moving stock, and recognised expected credit-loss provisions against certain receivables. It also reclassified Rs 262.578 crore of consolidated with-recourse bill discounting arrangements at 31 March 2026 from trade receivables to current borrowings.
The profit effect differed between the standalone company and the group. Standalone FY26 profit was reduced by Rs 72.132 crore to Rs 181.974 crore from Rs 254.106 crore, while consolidated FY26 profit increased by Rs 27.627 crore to Rs 391.517 crore. Consolidated adjustments included group-specific corrections involving associates, acquisitions, foreign-subsidiary translation, service concession accounting and lease accounting.
How did the restatement change FY26 profit and revenue?
Kaynes Technology's consolidated FY26 revenue from operations increased by Rs 54.582 crore to Rs 3,680.936 crore, while profit for the year increased by Rs 27.627 crore to Rs 391.517 crore. The revenue correction included sales for which control had not passed at the earlier reporting date, with revenue and related costs recognised in the periods that Kaynes Technology determined were appropriate.
The higher consolidated profit followed a different movement above and below tax. Profit before tax declined by Rs 16.013 crore to Rs 488.301 crore, but total tax expense declined by Rs 43.640 crore to Rs 96.784 crore. Finance cost was restated down by Rs 38.026 crore to Rs 78.901 crore after Kaynes Technology corrected the elimination of interest income and finance cost on holding-company loans to subsidiaries.
The six months ended 30 September 2025 show that the restatement did not have the same effect in each period. Consolidated revenue for that period rose by Rs 31.234 crore to Rs 1,610.918 crore, whereas profit fell by Rs 13.579 crore to Rs 182.447 crore. The period included revised revenue and cost timing, a Rs 5.236 crore share of associate loss and tax adjustments.
Got a follow-up? Ask IRIS
How did receivables, inventory and borrowings change?
Kaynes Technology's consolidated total assets at 31 March 2026 increased by Rs 509.188 crore to Rs 7,403.203 crore, while total equity increased by Rs 63.095 crore to Rs 4,825.583 crore. The asset changes included a Rs 371.468 crore increase in current trade receivables, a Rs 112.775 crore increase in goodwill and a Rs 65.426 crore balance for investments accounted for using the equity method.
Short-term borrowings were restated up by Rs 466.909 crore to Rs 1,004.850 crore at 31 March 2026. The amount included Rs 262.578 crore of with-recourse bill discounting, Rs 139.122 crore of supplier-finance arrangements, Rs 29.864 crore of current maturities of long-term borrowings and Rs 12.203 crore of term loans previously set off against contract assets. Kaynes Technology classified these arrangements as obligations of a borrowing nature.
Inventories fell by Rs 44.754 crore to Rs 1,058.473 crore after Kaynes Technology reversed excess overheads capitalised into inventory and recognised provisions for slow-moving and non-moving items. Current trade receivables increased to Rs 1,899.083 crore from Rs 1,527.615 crore, reflecting, among other entries, reversal of previous set-offs, revenue-timing corrections and balances associated with the reassessed service concession arrangement.
Which accounting errors were corrected by Kaynes Technology?
Kaynes Technology said revenue had been recognised on certain transactions before control of goods transferred to customers. It reversed revenue, trade receivables, inventory and cost of materials consumed in the initially reported periods, then recognised revenue and costs in the periods it considered correct. In consolidated FY26, cost of materials consumed rose by Rs 32.406 crore to Rs 2,574.628 crore following the full set of cost adjustments.
The group also reassessed a revenue contract under Appendix D of Ind AS 115, relating to service concession arrangements. Kaynes Technology derecognised property, plant and equipment previously recorded for that contract and reversed related depreciation, with effects on retained earnings at 1 April 2025, receivables, revenue, finance income, depreciation and cost of goods sold in the comparative periods.
Other consolidated corrections included accounting for an associate under Ind AS 28, foreign-exchange and non-controlling-interest calculations at subsidiaries, goodwill and capital-reserve treatment in acquisitions, acquisition costs recorded as prepaid expenses and leases under Ind AS 116. Kaynes Technology also corrected an excess deferred-consideration liability for an FY26 acquisition after identifying an incorrect working-capital settlement adjustment, which had overstated goodwill.
The cash-flow statements were restated as well. For the six months ended 30 September 2025, consolidated net cash used in operating activities was restated to Rs 404.183 crore from Rs 217.828 crore, net cash used in investing activities to Rs 1,466.495 crore from Rs 1,269.942 crore, and financing cash inflow to Rs 1,688.803 crore from Rs 1,496.265 crore.
Conclusion
The restatement changes Kaynes Technology's historical earnings, asset and financing baseline rather than only moving balances between headings. Consolidated FY26 profit is now Rs 391.517 crore, but current borrowings are also now Rs 1,004.850 crore after obligations previously presented against receivables, payables or contract assets were classified as borrowings.
The next disclosed corporate steps to watch are the proposed display-module joint venture, in which Kaynes Technology is intended to hold 90%, and the proposed strike-off of non-operational Kaynes Embedded Systems Private Limited. Kaynes Technology said the strike-off is expected on or before 31 March 2027, subject to required approvals.