










Kennametal India Limited revenue rises 86% to Rs 551.7 crore
Key highlights
- Kennametal India Limited reported Q1 FY27 revenue of Rs 551.7 crore, up 86.4% from Rs 296 crore a year earlier.
- KIL’s profit before tax rose to Rs 142.7 crore from Rs 43.4 crore in the September 2025 quarter.
- KIL’s Hard Metal and Hard Metal Products generated Rs 519.8 crore of quarterly revenue and Rs 163 crore of segment result.
- KIL’s Machining Solutions reported a Rs 5.5 crore segment loss on revenue of Rs 31.9 crore.
powered by IRIS
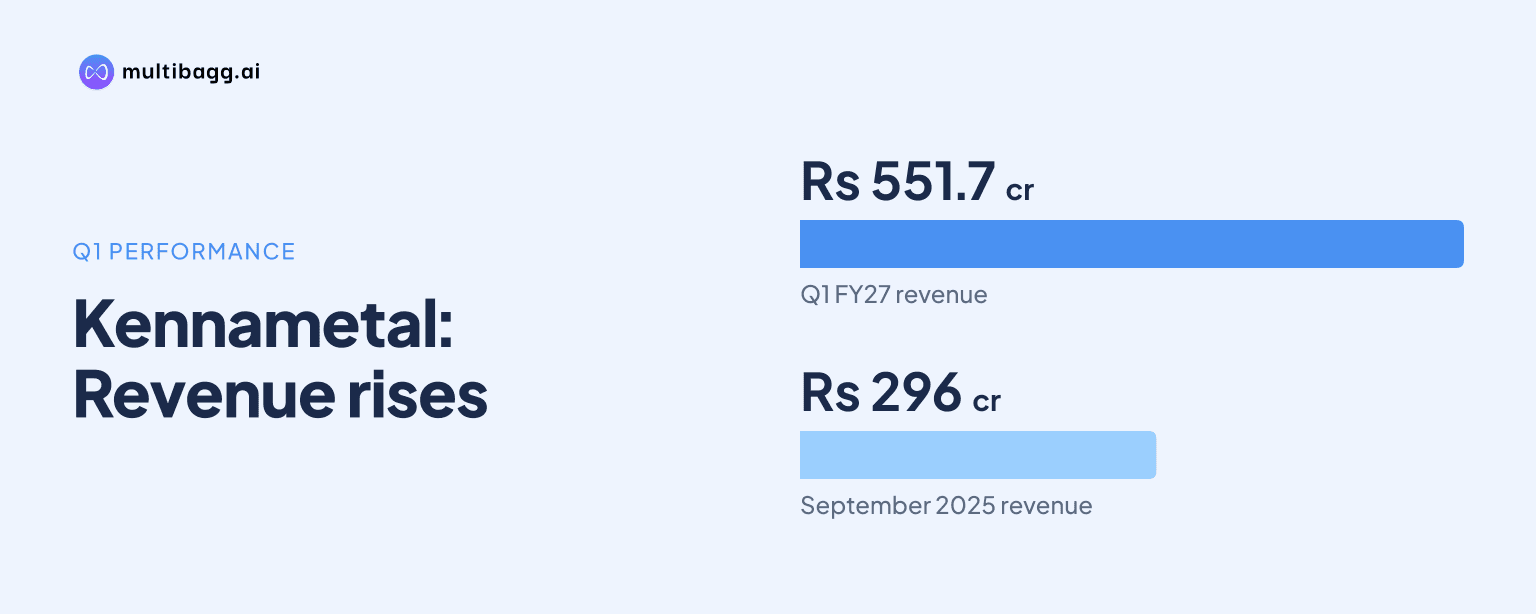
Kennametal India Limited reported Q1 FY27 revenue of Rs 551.7 crore, up 86.4% year on year, and profit before tax of Rs 142.7 crore versus Rs 43.4 crore, as favourable raw-material pricing timing and higher Hard Metal volumes lifted results for the quarter ended September 30, 2026.
Know Kennametal India inside out
Results, valuation, peers and who's buying, in one view.
How did KIL’s Q1 FY27 revenue and profit change?
KIL’s revenue from operations rose from Rs 296 crore in the quarter ended September 30, 2025 to Rs 551.7 crore in the quarter ended September 30, 2026. Total income increased from Rs 298.4 crore to Rs 552.6 crore over the same comparison, while profit before tax increased by Rs 99.3 crore to Rs 142.7 crore. The reported revenue growth rate was 86.4% year on year.
Net profit for the September 2026 quarter was Rs 106.7 crore, compared with Rs 31.4 crore a year earlier. Basic and diluted earnings per share, not annualised, were Rs 48.54, against Rs 14.30 in the September 2025 quarter. Total tax expense rose to Rs 36 crore from Rs 12 crore, comprising Rs 36.9 crore of current tax, a Rs 20 lakh adjustment relating to earlier years and a Rs 70 lakh deferred-tax credit.
On a sequential basis, revenue increased by Rs 74.1 crore from Rs 477.6 crore in the quarter ended June 30, 2026, while profit before tax rose by Rs 24.3 crore from Rs 118.4 crore. Net profit increased by Rs 17.9 crore from Rs 88.8 crore. The June 2026 quarterly figures were balancing figures between the audited full-year result and the previously published year-to-date figures, according to KIL’s notes.
What drove KIL’s Q1 FY27 earnings increase?
KIL said its September 2026 financial results were primarily driven by the favourable timing of raw material-related pricing compared with costs. In its November 12, 2026 release, management also cited stronger volume growth from the Hard Metal business and sustained demand across end-use segments as contributors to revenue growth. These disclosed factors identify pricing timing and Hard Metal volumes, rather than sales growth alone, as drivers of the quarter’s profitability.
Material consumption rose to Rs 319.5 crore from Rs 91.4 crore a year earlier, while purchases of stock-in-trade increased to Rs 178.3 crore from Rs 93.2 crore. At the same time, changes in inventories of finished goods, work-in-progress and stock-in-trade were negative Rs 213.5 crore, compared with negative Rs 30.4 crore in the September 2025 quarter. Total expenses rose by Rs 154.9 crore to Rs 409.9 crore, less than the Rs 254.2 crore increase in total income.
As a calculation from the reported figures, profit before tax represented about 25.8% of total income in the September 2026 quarter, compared with about 14.5% a year earlier. Employee-benefit expense increased to Rs 45.1 crore from Rs 38.6 crore, depreciation and amortisation was broadly stable at Rs 11.9 crore against Rs 11.7 crore, and other expenses rose to Rs 67.3 crore from Rs 50.5 crore. These movements occurred alongside the raw-material pricing effect described by KIL.
Got a follow-up? Ask IRIS
Which KIL segment produced the revenue growth?
KIL’s Hard Metal and Hard Metal Products segment produced Rs 519.8 crore of revenue in the September 2026 quarter, up from Rs 263.9 crore a year earlier. Its Machining Solutions segment recorded Rs 31.9 crore of revenue, marginally below Rs 32.1 crore in the September 2025 quarter. Consequently, the Hard Metal segment accounted for nearly all of the Rs 255.7 crore year-on-year increase in company revenue.
Hard Metal and Hard Metal Products segment result increased to Rs 163 crore from Rs 49.8 crore year on year and from Rs 138.5 crore in the June 2026 quarter. Machining Solutions reported a segment loss of Rs 5.5 crore in September 2026, compared with a Rs 1.5 crore profit a year earlier, although the loss narrowed from Rs 9.2 crore in the preceding quarter. Segment results are reported before interest, unallocable income and unallocable expenditure.
KIL reported Hard Metal and Hard Metal Products segment assets of Rs 1,410.6 crore at September 30, 2026, compared with Rs 660.4 crore a year earlier. Machining Solutions segment assets declined to Rs 94.7 crore from Rs 128.5 crore. Total assets rose to Rs 1,599.9 crore from Rs 974.8 crore, while total liabilities increased to Rs 639.5 crore from Rs 195.5 crore over that period.
What risks and accounting matters did KIL disclose?
KIL management said the operating environment continued to be shaped by geopolitical uncertainties and historically high tungsten prices in its November 12, 2026 commentary. Management said its business model, execution and customer-focused approach position KIL to navigate these conditions and capture growth opportunities across key markets. The release did not quantify any expected financial effect from tungsten prices or geopolitical developments.
KIL also said it would continue to monitor finalisation of central and state rules and further government clarification on the Labour Code. The company’s assessment resulted in nil increase in gratuity liability arising from past service cost during the September 2026 quarter. Any additional accounting impact will be recorded as required, according to KIL.
The Board approved the unaudited results on November 12, 2026 after review by its Audit Committee. Price Waterhouse & Co Chartered Accountants LLP conducted a limited review and stated that nothing had come to its attention to indicate a material misstatement or non-compliance with the applicable reporting framework. KIL also reported that it had no subsidiary, associate or joint-venture entities for the periods presented.
Conclusion
KIL’s September 2026 quarterly result combined an 86.4% increase in revenue to Rs 551.7 crore with a rise in profit before tax to Rs 142.7 crore from Rs 43.4 crore. The disclosed explanation centres on favourable timing between raw-material pricing and costs, together with higher Hard Metal volumes; the segment supplied Rs 519.8 crore of revenue and Rs 163 crore of segment result, while Machining Solutions remained loss-making.
The next reported period will show whether revenue can build on the Rs 74.1 crore sequential increase from June 2026 and whether the favourable raw-material pricing timing persists. Investors can also watch KIL’s stated monitoring of Labour Code rules, as well as management’s comments on historically high tungsten prices and geopolitical uncertainties, neither of which had a quantified September-quarter financial effect in the filing.