










Kirloskar Pneumatic starts delayed precision-order dispatch
Key highlights
- KPCL said its delayed Precision Engineering order has begun dispatch and should be completed across Q3 and Q4 FY27.
- PED represented about 13% to 14% of KPCL’s more than Rs 2,040 crore order book on 1 October 2026.
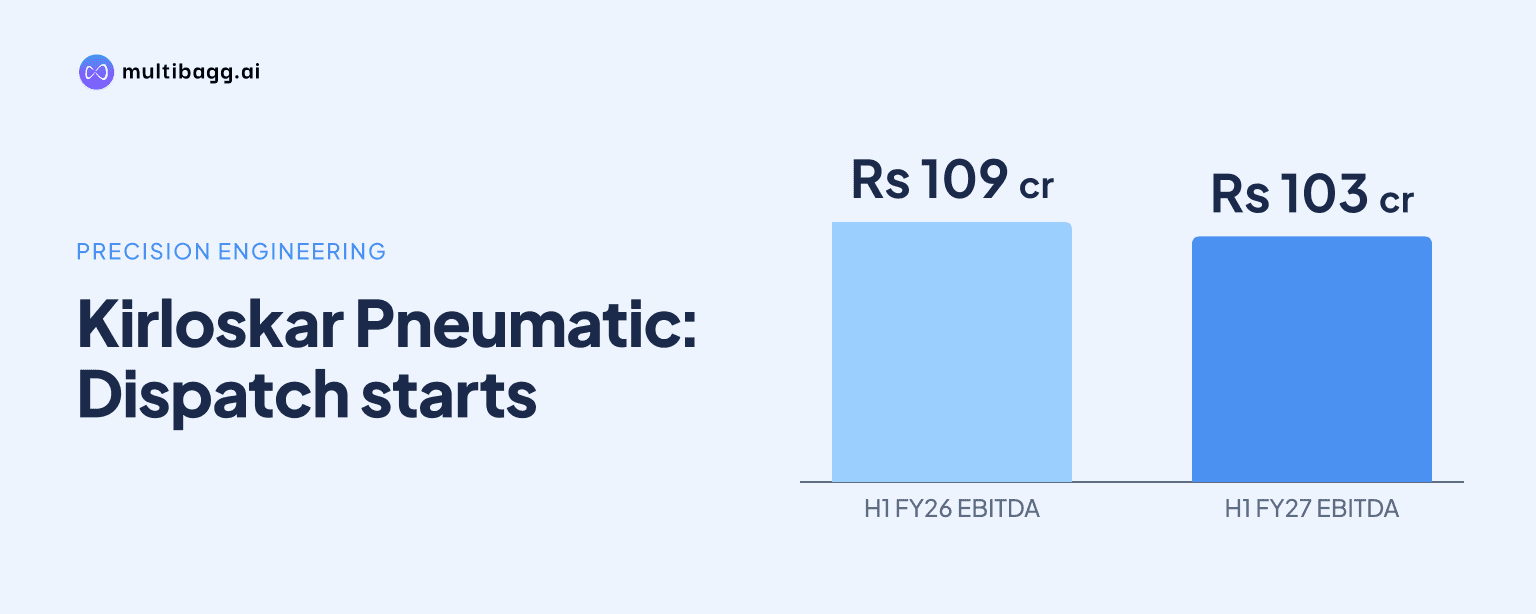
- H1 FY27 EBITDA was Rs 103 crore, down from Rs 109 crore in H1 FY26, while margin was 16.2%.
- Equipment accounted for 78% of H1 FY27 business, up from 65% in H1 FY26.
powered by IRIS
Kirloskar Pneumatic said its delayed Precision Engineering division, or PED, order has begun dispatch and is expected to be executed through Q3 and Q4 FY27 after documentation compiled over several decades held back work planned for H1. KPCL said PED represented about 13% to 14% of its more than Rs 2,040 crore order book on 1 October 2026.
Know Kirloskar Pneumatic Company inside out
Results, valuation, peers and who's buying, in one view.
What delayed KPCL’s Precision Engineering order?
KPCL said rigorous documentation delayed the PED order because the records for the equipment were a mix of documents developed over several decades. Management described the equipment as highly critical but relatively low value, a combination that resulted in extensive documentation requirements despite KPCL having supplied the equipment for many years.
The order was unusual because one of this scale had not materialised previously for the equipment, according to management. It said the documentation should probably have been rectified when the order was accepted, but added that the issue has now been corrected and equipment dispatches have started.
KPCL did not disclose the order’s exact value. When an analyst referred to a Rs 450 crore to Rs 500 crore figure, management said it had not provided that figure and that the actual amount was lower, without disclosing an alternative value.
When will KPCL execute the delayed order?
KPCL expects almost the entire delayed PED order to be executed from Q3 FY27 and completed in Q4 FY27. Management said it had expected a large portion of the order to be executed in the first six months of FY27, but that did not materialise because the documentation issue delayed dispatches.
The revised schedule shifts work expected in H1 FY27 into the second half. Management said PED dispatches had not picked up so far in FY27, while air compressors traditionally contribute about 15% to 20% of business, process gas 30% to 40%, and refrigeration 30% to 40%.
PED accounted for about 13% to 14% of KPCL’s more than Rs 2,040 crore order book as of 1 October 2026, based on management’s previously stated estimate. KPCL said it did not have an exact figure for new PED order booking within that order book and indicated that the amount would not be substantial.
How did the delay coincide with KPCL’s H1 FY27 results?
KPCL’s H1 FY27 operating measures were lower than in H1 FY26, while profit after tax increased because of exceptional income. Earnings before interest, tax, depreciation and amortisation, or EBITDA, declined to Rs 103 crore from Rs 109 crore, and the EBITDA margin moved to 16.2% from 16.4%.
Profit before tax before exceptional items was Rs 85.1 crore in H1 FY27, compared with Rs 93.8 crore in H1 FY26. Profit after tax rose to Rs 74 crore from Rs 71.3 crore because KPCL recognised Rs 11 crore of exceptional income after surrendering 1.77 acres of its 160-acre Nashik land for a state road infrastructure project.
KPCL’s H1 revenue mix also changed: equipment represented 78% of total business, up from 65% in H1 FY26, while package business declined to 22% from 35%. Management attributed material cost falling to 44.3% of sales from 50% to a better product mix and backward integration in manufacturing.
Got a follow-up? Ask IRIS
Can KPCL repeat Precision Engineering business beyond this order?
KPCL said the repeatability of PED revenue is not yet established, which is why it has not given detailed disclosures for the division. Management said it needs to determine whether the business is sustainable year after year before providing more information on PED revenue or order contribution.
KPCL has development orders for PED products, but management characterised them as small orders intended to demonstrate the company’s capability rather than major commercial contracts. Its stated sequence is to execute those development orders before pursuing larger orders, leaving future PED order flow beyond the FY27 project unresolved.
KPCL’s overall order book increased to more than Rs 2,040 crore on 1 October 2026 from Rs 1,863 crore at the beginning of the year. Management said the increase largely came from compressed natural gas and refrigeration equipment, with smaller growth in niche compressors for syngas and biogas applications rather than from PED.
What is KPCL expecting for H2 FY27?
Management said KPCL is targeting an 18% to 20% full-year EBITDA margin and remains confident of strong double-digit revenue growth in FY27. It described 20% annual growth as aspirational, saying top-line growth looked more challenging but bottom-line growth could be somewhat above 20%.
H2 FY27 is also expected to include package deliveries, which typically take 12 to 18 months from order booking. Management said many large package orders were booked in the second half of the previous year, limiting package dispatches in H1 FY27, while refrigeration equipment has a seasonal sales element.
Exports were less than 10% of KPCL’s sales in the previous year and were expected to remain at a similar level in FY27. Management said conflict-related difficulty dispatching to parts of the Middle East affected the quarter and deferred some orders, but maintained its expectation of double-digit full-year revenue growth.
Conclusion
The documentation failure moved a material PED execution task from H1 into Q3 and Q4 FY27 rather than cancelling it. The shift comes alongside H1 EBITDA falling to Rs 103 crore from Rs 109 crore, even as equipment represented 78% of business and the order book increased to more than Rs 2,040 crore.
The next disclosed milestone is completion of the delayed PED order by Q4 FY27. Management’s plan also calls for executing small PED development orders before pursuing larger contracts, while package deliveries, the 18% to 20% EBITDA-margin target and Middle East dispatch conditions remain factors to watch in H2.