










Kirloskar Pneumatic H1 sales fell as dispatches slipped
Key highlights
- KPCL reported H1 FY27 sales of Rs 620 crore, down from Rs 650 crore in H1 FY26.
- KPCL's order book exceeded Rs 2,040 crore on October 1, 2026, compared with Rs 1,863 crore at the start of FY27.
- Equipment contributed 78% of H1 FY27 business, up from 65% in H1 FY26.
- H1 FY27 profit after tax was Rs 74 crore, including Rs 11 crore of exceptional income.
powered by IRIS
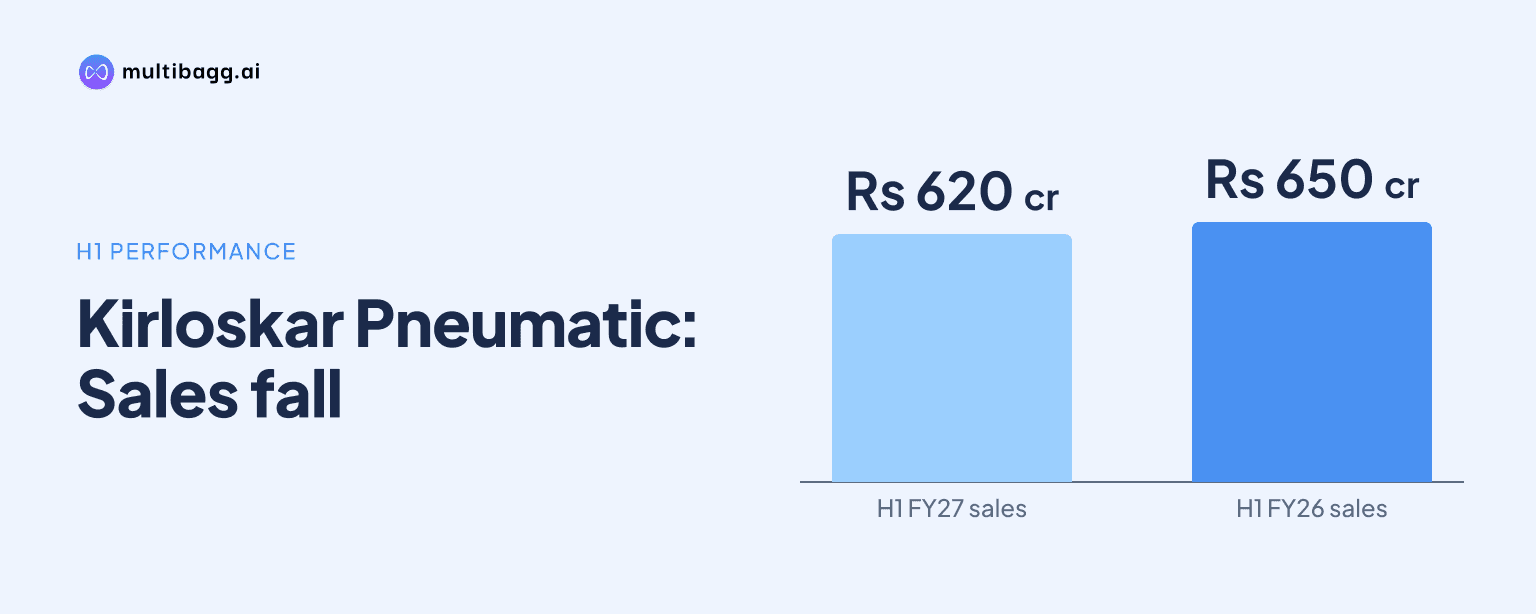
Kirloskar Pneumatic Company Limited reported H1 FY27 sales of Rs 620 crore, Rs 30 crore below H1 FY26, after delayed Precision Engineering Division dispatches and package shipments to the Middle East reduced execution. KPCL said dispatches began in Q3 FY27 and expects CNG, refrigeration and package deliveries to improve second-half activity.
Know Kirloskar Pneumatic Company inside out
Results, valuation, peers and who's buying, in one view.
Why did KPCL's H1 FY27 sales decline?
KPCL's H1 FY27 sales declined because package shipments to the Middle East were delayed and the Precision Engineering Division, or PED, executed dispatches later than planned. Management described Q2 FY27 as challenging for order booking, sales and execution, with H1 sales lower year on year for the second time in two years.
Q2 FY27 sales were Rs 320 crore, down from Rs 378 crore in Q2 FY26, because no large domestic package dispatches were scheduled during the quarter. The equipment business therefore carried more of the quarter's revenue, while the chief financial officer also cited timing differences and delayed export consignments amid global uncertainty.
Management said PED delays had a larger effect than freight costs. The relevant order required extensive documentation for equipment described as highly critical but relatively low value, and KPCL said documents built up through multiple historical product iterations had to be corrected. Management said that process was completed and PED dispatches had started during Q3 FY27.
How did KPCL's business mix and order book change?
KPCL's H1 FY27 mix moved towards equipment, which accounted for 78% of business compared with 65% in H1 FY26, while package business fell to 22% from 35%. The 13-percentage-point shift reflected the low level of package dispatches in H1 FY27 rather than a disclosed fall in the package-order opportunity pipeline.
The order book exceeded Rs 2,040 crore on October 1, 2026, compared with Rs 1,863 crore at the beginning of FY27. Management attributed the increase mainly to renewed compressed natural gas, or CNG, demand and refrigeration equipment orders, while noting that large package orders take longer to finalize because customers have their own approval processes.
Export sales rose to Rs 64 crore in H1 FY27 from Rs 31 crore a year earlier, despite shipment disruption in parts of the Middle East. Management said exports represented less than 10% of sales in FY26 and should remain at a similar proportion in FY27, limiting their expected impact on the full year even though deferred Middle East deliveries affected Q2.
Refrigeration demand was uneven across end markets in H1 FY27: packaging remained slow, while food processing and cold storage were active. KPCL booked orders for Khione, KC/KCX and Tyche equipment, and said ammonia reciprocating compressors saw demand from food processors; its Zephyros range was commercialized in Q2 FY27, although the first external unit had not yet been commissioned.
How did KPCL's H1 FY27 earnings compare with last year?
KPCL reported earnings before interest, tax, depreciation and amortisation, or EBITDA, of Rs 103 crore in H1 FY27, down from Rs 109 crore in H1 FY26, while the margin moved to 16.2% from 16.4%. Lower sales were partly offset by material costs falling to 44.3% of sales from 50.0%, which management attributed to product mix and backward integration.
Employee expense rose to Rs 109 crore from Rs 97.4 crore as KPCL added headcount and expanded activity at Nashik, Saswad and Hadapsar. Manufacturing other expenses increased to Rs 149.3 crore from Rs 133.5 crore, reflecting the full-period impact of Nashik operations and higher activity in the service business.
Profit after tax rose to Rs 74 crore from Rs 71.3 crore because KPCL recorded Rs 11 crore of exceptional income in Q2 and H1 FY27. The income followed the surrender of 1.77 acres from its 160-acre Nashik landholding for a state road project; management said the plant expansion had been positioned away from the proposed road alignment and operations were unaffected.
Got a follow-up? Ask IRIS
What does KPCL expect in H2 FY27?
KPCL expects Q3 FY27 to be strong and Q4 FY27 to be stronger, driven by PED dispatches, large packages and standard equipment sales. Management said a large portion of PED execution had originally been expected in the first six months, but nearly the whole order would instead be dispatched during Q3 and completed in the following quarter.
CNG and refrigeration orders are expected to support the recovery in H2 FY27. Management said CNG demand had revived after several years of stagnation, while refrigeration orders were supported by food processing; the gas-systems opportunity pipeline also looked substantial, though finalisation was taking time and management expected some package orders in the current quarter.
Large package deliveries typically take 12 to 18 months, and management said many relevant orders were booked in the second half of FY26. That booking pattern left limited package revenue for H1 FY27 but creates potential deliveries in H2 FY27. Management described 20% annual growth as an aspiration and said full-year top-line growth should be double digit, while acknowledging that the target had become more challenging.
Which businesses and spending plans could affect execution?
KPCL's process-gas business dispatched India's first 1,000-bar hydrogen refuelling station in the preceding quarter and managed more than 1,060 CNG stations across India as of H1 FY27, after adding 90 stations. Its partnership with Kobe Compressors is intended to address downstream petrochemical applications requiring API 617 and API 618 compressors and larger requirements in petrochemicals, green ammonia and steel.
Systems and Components reported H1 FY27 revenue of Rs 9 crore, while its order book increased to Rs 22 crore from Rs 4.1 crore at the start of FY27. Management said the larger order book provided confidence for coming quarters, but did not provide a conversion timetable or revenue target for the subsidiary.
KPCL was debt-free and held net cash and cash equivalents of Rs 513.7 crore on October 1, 2026. It incurred about Rs 34 crore of capital expenditure and paid Rs 57 crore in dividends during H1 FY27; depreciation increased to Rs 17.9 crore from Rs 14.9 crore after previous spending at the Nashik and Saswad facilities.
Conclusion
KPCL entered H2 FY27 with sales and EBITDA below the prior-year first half but with an order book above Rs 2,040 crore and a greater equipment contribution. The reported sales decline resulted from delayed PED and package execution, while the rise in H1 profit after tax was driven by Rs 11 crore of exceptional land-surrender income rather than operating growth.
The next disclosed test is whether PED dispatches continue through Q3 FY27 and are completed in Q4 FY27, alongside CNG, refrigeration and large-package deliveries. Management also expects some package order finalisations in the current quarter and continues to target an 18% to 20% full-year EBITDA margin, making execution and conversion of the order pipeline the key matters to watch.