










Kwality Pharmaceuticals lifts FY27 outlook to Rs 720 crore-plus
Key highlights
- KPL raised FY27 revenue guidance to Rs 720 crore-plus from Rs 700 crore.
- KPL reported Q2 FY27 consolidated revenue of Rs 181 crore, up 63% year on year.
- KPL's Q2 FY27 PAT doubled year on year to Rs 50 crore.
- KPL's cash conversion cycle improved to 130 days from 170 days in FY26.
powered by IRIS
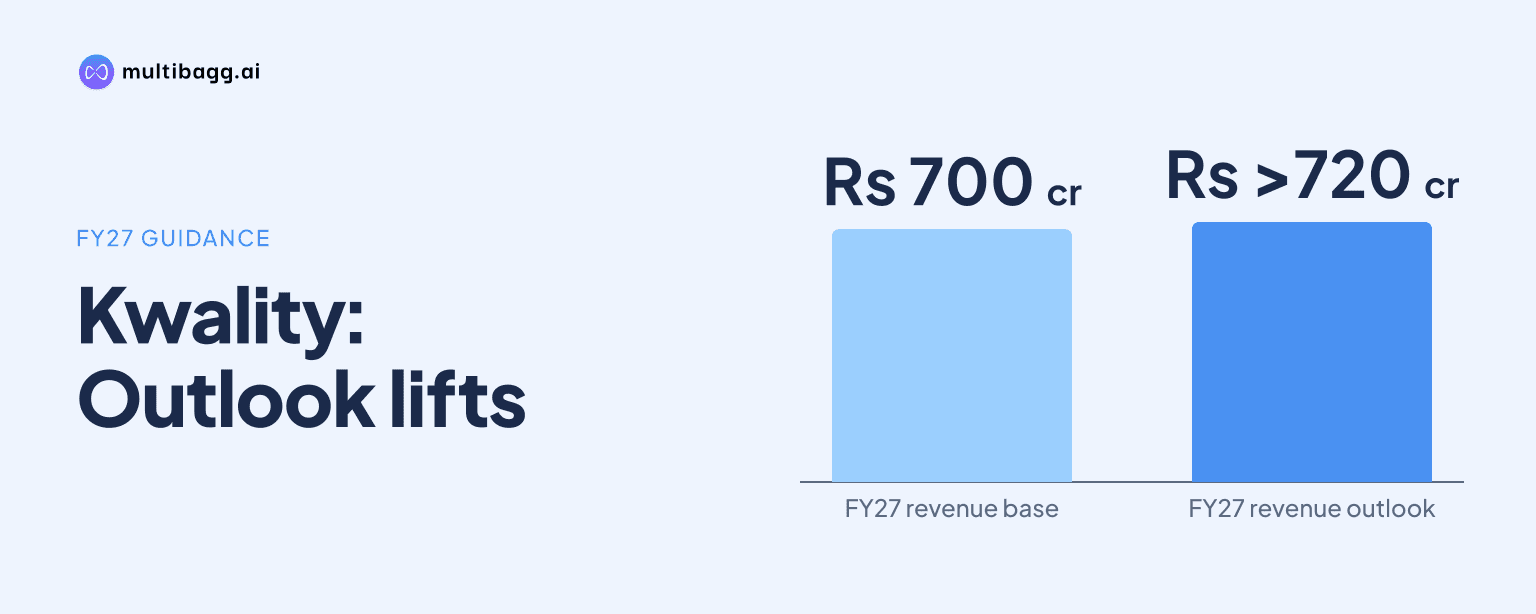
Kwality Pharmaceuticals Limited raised FY27 revenue guidance to Rs 720 crore-plus from Rs 700 crore after Q2 FY27 consolidated revenue rose 63% year on year to Rs 181 crore and profit after tax doubled to Rs 50 crore. KPL attributed the higher outlook to new product registrations and the conversion of its regulatory pipeline into commercial opportunities.
Know Kwality Pharmaceuticals inside out
Results, valuation, peers and who's buying, in one view.
Why did KPL raise its FY27 revenue guidance?
KPL raised its FY27 revenue guidance to Rs 720 crore-plus from its earlier guidance of Rs 700 crore. Management said the revision reflects an improving business outlook, faster product registrations across key international markets and a growing contribution from newly registered products.
The upgraded forecast indicates that management expects regulatory registrations to contribute to sales during the remaining FY27 period. The filing does not provide a quarterly revenue target for the second half, a country-wise revenue split or a profit-after-tax target.
KPL said 19 products in its 40-molecule bioequivalence, or BE, programme have completed studies and are ready for regulatory filings across international markets. Management linked the broader product pipeline and new registrations with sustained growth and wider market penetration.
How did KPL perform in Q2 FY27?
KPL reported consolidated revenue of Rs 181 crore in Q2 FY27, up 63% from Rs 111 crore in Q2 FY26 and 11.7% from Rs 162 crore in Q1 FY27. Consolidated revenue for H1 FY27, the six months ended September 30, 2026, was Rs 343 crore.
The year-on-year comparison represents an increase of Rs 70 crore in quarterly revenue, while the sequential increase was Rs 19 crore. The H1 FY27 total incorporates the first two quarters of the financial year, with Q2 contributing Rs 181 crore.
KPL reported Q2 FY27 PAT of Rs 50 crore, compared with Rs 25 crore in Q2 FY26. Earnings before interest, tax, depreciation and amortisation, or EBITDA, margin increased to 27.5% from 23.4%, which management attributed to improved operating leverage and a favourable product mix.
PAT margin rose to 16% in Q2 FY27 from 13% a year earlier and 15.7% in Q1 FY27. The filing does not quantify the contribution of individual products, markets or cost items to the reported margin changes.
Got a follow-up? Ask IRIS
What manufacturing and regulatory projects is KPL pursuing?
KPL acquired 4 acres adjacent to its Amritsar manufacturing campus during Q2 FY27 for Unit 7, a proposed general manufacturing facility. The planned fully automated complex is envisaged to have 4-plus injectable lines and 6-plus oral solid dosage, or OSD, lines.
Unit 7 is intended to add capacity across multiple dosage forms for KPL's longer-term requirements. The filing does not disclose either a capital-expenditure amount or a completion date for the proposed facility.
KPL said its oncology manufacturing expansion is progressing as scheduled, with completion anticipated by June 2027. Construction of its Hormone manufacturing facility has been completed, and the company has begun the process for its manufacturing-licence audit.
In ophthalmics, KPL underwent SGS audits towards International Organization for Standardization 13485, or ISO 13485, and CE Medical Device Regulation, or CE MDR, certification. The company also launched five new products from its ophthalmic eye-drop manufacturing facility during the period.
KPL received European Union Good Manufacturing Practice, or EU-GMP, certification from Hungary for its Cephalosporin and Oncology manufacturing facilities. Management identified Hungary as a Class 1 European regulatory jurisdiction and said the certification advances its access to regulated markets and complex pharmaceutical segments.
Has KPL's working-capital position changed?
KPL reported a cash conversion cycle of 130 days, compared with 170 days in FY26 and 297 days in FY23. Management attributed the 167-day improvement from FY23 to tighter inventory management and improved receivables discipline.
Debtor days improved to 77 days from 111 days, while payable days stood at 126 days compared with 144 days in FY26. The filing does not provide inventory-days figures, but it links the reduced cash conversion cycle to cash generation and funding business requirements.
KPL's board approved unaudited standalone and consolidated results for the quarter and half year ended September 30, 2026, at its November 12, 2026 meeting. Vijay Mehra & Co., the outgoing statutory auditor, issued a limited review report dated November 12, 2026.
The board also took note of Vijay Mehra & Co.'s resignation effective November 12, 2026 and appointed B S R & Co. LLP to fill the casual vacancy. The appointment requires shareholder approval at a general meeting to be convened within three months of the board's recommendation, and KPL said no management concerns were raised by the resigning auditor.
Conclusion
KPL's move to Rs 720 crore-plus FY27 revenue guidance follows a Q2 in which consolidated revenue reached Rs 181 crore and PAT reached Rs 50 crore. Compared with Q2 FY26, revenue increased by Rs 70 crore, EBITDA margin rose by 4.1 percentage points to 27.5%, and PAT margin increased by 3 percentage points to 16%.
The disclosed milestones to watch are the planned June 2027 completion of the oncology expansion, the Hormone facility's manufacturing-licence audit and filings for the 19 BE-completed products. KPL may also provide further details on Unit 7's proposed 4-plus injectable and 6-plus OSD lines, while B S R & Co. LLP's appointment remains subject to shareholder approval within three months of the November 12, 2026 recommendation.