










LCC Projects Limited Q2 profit rises 58% as EBITDA margin reaches 15.5%
Key highlights
- LCC Projects' Q2FY27 PAT rose 58% year on year to Rs 76.9 crore, while revenue increased 34% to Rs 885.7 crore.
- Q2FY27 EBITDA rose 46% to Rs 136.9 crore, with EBITDA margin expanding 130 basis points to 15.5%.
- LCC Projects' H1FY27 revenue increased 5% to Rs 1,688.3 crore, while PAT rose 13% to Rs 142.7 crore.
- The company reported H1FY27 order booking of Rs 2,229.1 crore and an order book of Rs 8,146.6 crore as of September 30, 2026.
powered by IRIS
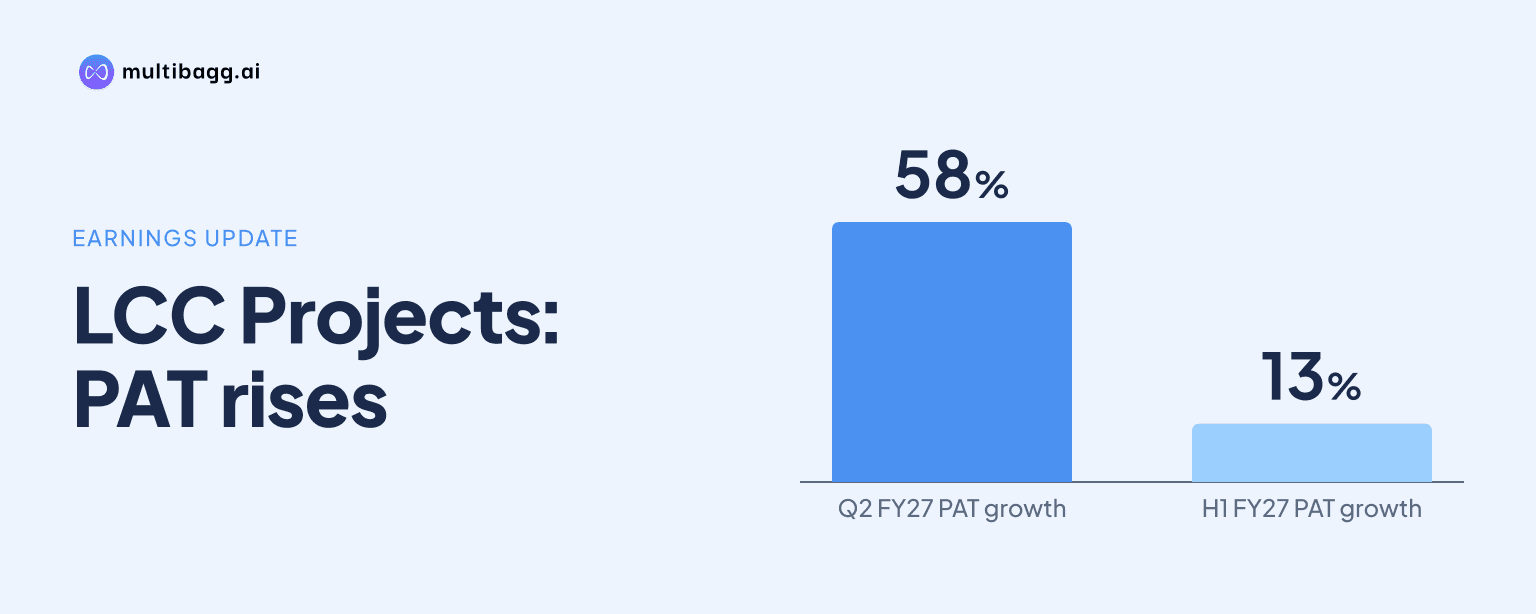
LCC Projects reported consolidated profit after tax of Rs 76.9 crore in the second quarter of financial year 2027 (Q2FY27), up 58% year on year, while revenue rose 34% to Rs 885.7 crore. Earnings before interest, tax, depreciation and amortisation (EBITDA) margin increased to 15.5% from 14.2%, helping profit grow faster than revenue.
Know LCC Projects inside out
Results, valuation, peers and who's buying, in one view.
Why did LCC Projects' Q2FY27 profit grow faster than revenue?
LCC Projects' profit after tax (PAT) increased 58% year on year to Rs 76.9 crore in Q2FY27, compared with a 34% increase in revenue from operations to Rs 885.7 crore. EBITDA rose 46% to Rs 136.9 crore, while earnings before interest and tax (EBIT) increased 52% to Rs 130.3 crore. The reported growth rates show that each of these profit measures rose faster than revenue during the quarter.
The Q2FY27 result compares with revenue of Rs 661.3 crore, EBITDA of Rs 93.8 crore, EBIT of Rs 85.6 crore and PAT of Rs 48.6 crore in Q2FY26. EBITDA increased by Rs 43.1 crore over the year-earlier quarter, while PAT increased by Rs 28.3 crore. The difference between revenue growth and profit growth coincided with higher reported operating, EBIT and PAT margins.
Management attributed the Q2FY27 margin expansion to improved project mix, operational efficiencies and stringent cost controls. It also cited timely project delivery, efficient resource utilisation and disciplined project management as factors behind higher execution and profitability. These are management explanations in the results release rather than separately quantified cost or project-mix disclosures.
How did LCC Projects' Q2FY27 margins change?
LCC Projects expanded all three reported profitability margins in Q2FY27 compared with Q2FY26. EBITDA margin increased to 15.5% from 14.2%, EBIT margin rose to 14.6% from 12.8%, and PAT margin reached 8.6% from 7.3%. The respective changes were 130 basis points, 180 basis points and 130 basis points, with one basis point equal to one-hundredth of a percentage point.
The 15.5% EBITDA margin in Q2FY27 was also above the 13.4% EBITDA margin reported for the full financial year 2026 (FY26). Q2FY27 EBIT margin of 14.6% exceeded the FY26 level of 13.1%, while PAT margin of 8.6% was above the FY26 figure of 7.9%. This comparison places a single quarter alongside the preceding full year and is not a forecast of future margins.
Management said it would continue to evaluate projects selectively, focusing on opportunities aligned with its execution strengths and profitability objectives. The release did not provide a numerical margin target, project-level cost data or a breakdown of the improved project mix behind the 15.5% Q2FY27 EBITDA margin.
Got a follow-up? Ask IRIS
How did LCC Projects' first-half performance compare?
LCC Projects reported revenue from operations of Rs 1,688.3 crore for the first half of financial year 2027 (H1FY27), up 5% from Rs 1,606.8 crore in H1FY26. H1FY27 EBITDA increased 16% to Rs 256.4 crore and EBIT rose 18% to Rs 246.4 crore, both growing faster than revenue. PAT increased 13% to Rs 142.7 crore from Rs 126.4 crore in the comparable first half.
First-half margins improved from H1FY26, although they were below the Q2FY27 levels. H1FY27 EBITDA margin was 15.2%, compared with 13.8% a year earlier and 15.5% in Q2FY27. EBIT margin was 14.5% in H1FY27, against 12.9% in H1FY26 and 14.6% in Q2FY27, while PAT margin was 8.4%, compared with 7.8% and 8.6%, respectively.
The comparison indicates that profitability improved across both reported periods, but revenue growth differed substantially. Q2FY27 revenue grew 34% year on year to Rs 885.7 crore, whereas H1FY27 revenue rose 5% to Rs 1,688.3 crore. Management linked the quarter's performance to project execution and operating measures, but the release did not separately explain the difference between quarterly and first-half revenue growth.
What order book and debt did LCC Projects report?
LCC Projects reported an order book of Rs 8,146.6 crore as of September 30, 2026, and disclosed H1FY27 order booking of Rs 2,229.1 crore. Public-sector accounts represented about 75% of the order book, while private-sector accounts accounted for about 25%. The company describes its operating focus as complex irrigation and water-supply projects.
Gross debt stood at Rs 884.5 crore as of September 30, 2026, with gross debt-to-equity of 0.70 times. The release did not provide a prior-period gross-debt or debt-to-equity figure, so it does not show the direction of leverage from this document alone. It also did not disclose order-book execution timing or a value split between irrigation and water-supply projects.
Management said the order book and bid pipeline supported its confidence in execution momentum over coming quarters. Its stated approach is to assess new projects selectively, with an emphasis on timely delivery, disciplined project management and profitability objectives. The release gives no quantified bid-pipeline value or order-book conversion target.
Conclusion
LCC Projects' Q2FY27 performance shows that the 58% increase in PAT to Rs 76.9 crore was accompanied by a 34% rise in revenue to Rs 885.7 crore and broader margin expansion. EBITDA, EBIT and PAT all increased faster than revenue, while EBITDA margin rose by 130 basis points to 15.5%. H1FY27 also showed higher margins, with EBITDA margin at 15.2% versus 13.8% in H1FY26.
The next disclosed issue to watch is execution against the Rs 8,146.6 crore order book reported on September 30, 2026, alongside management's plan to pursue projects selectively. Management cited improved project mix, operating efficiencies and cost controls in Q2FY27, but gave no margin target or order-book conversion schedule. Its comments on future execution and bidding remain forward-looking statements subject to the uncertainties described in the release.