










Marico lifts FY27 EBITDA growth outlook to mid-20s on mix
Key highlights
- Marico raised its FY27 EBITDA growth outlook to the mid-20s from about 20%.
- First-half FY27 revenue, EBITDA and PAT increased 18%, 26% and 28%, respectively.
- Q2 FY27 Parachute volume grew 13% and its volume market share reached 60%.
- Marico expects FY27 revenue to comfortably exceed Rs 15,000 crore.
powered by IRIS
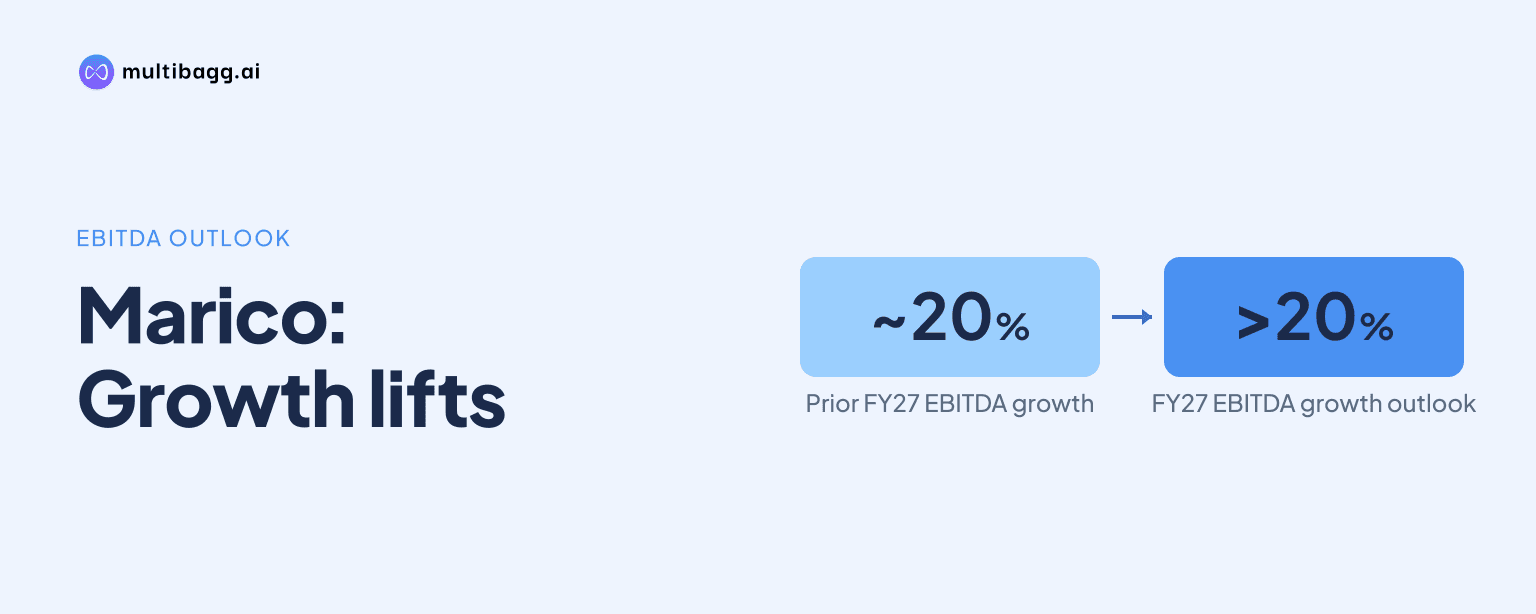
Marico Limited raised its financial year 2027 (FY27) earnings before interest, tax, depreciation and amortisation (EBITDA) growth outlook to the mid-20s from about 20% on November 2, 2026, after first-half EBITDA rose 26% and management cited mix, procurement, Parachute volumes and diversification profitability.
Know Marico inside out
Results, valuation, peers and who's buying, in one view.
Why did Marico raise its FY27 EBITDA outlook?
Marico said the upgraded FY27 EBITDA outlook reflects a combination of portfolio mix, procurement efficiency, unexpectedly high Parachute volume growth, improving diversification profitability and cost management. Management had previously estimated EBITDA growth at around 20%, but now expects growth in the mid-20s after gaining better visibility on the full year. The company also said it is removing offerings that are not profitable over the long term, including selected low-margin variants in Saffola Edible Oil.
Procurement was a specific factor in the upgrade because management said consumption costs can differ from market prices depending on buying efficiency and held positions. Copra prices remained rangebound at about 35% below the previous year's peak, although crude-linked derivatives and vegetable oils rose on geopolitical developments and weather concerns. Marico said it would use brand pricing power, softer copra and an aggressive cost-management programme to cushion crude-linked inflation rather than attributing the higher profit outlook solely to commodity costs.
How did Marico perform in Q2 and the first half?
Marico delivered 27% EBITDA growth in Q2 FY27, compared with 13% consolidated revenue growth and 31% growth in profit after tax (PAT). Gross margin expanded by about 600 basis points year on year, where one basis point equals one-hundredth of a percentage point, while EBITDA margin increased 200 basis points to 18.2%. The company increased advertising and promotion spending by 44% during the quarter, indicating that the margin expansion occurred alongside higher brand investment.
For the first half of FY27, Marico reported revenue growth of 18%, EBITDA growth of 26% and PAT growth of 28%. The Q2 revenue result was driven by 10% volume growth in India and 13% constant-currency growth in international business. This represented a broader contribution than a single commodity-led recovery: management said India Core, Foods, Premium Personal Care, digital-first brands and international operations all contributed to first-half growth.
Which businesses are supporting Marico's profit outlook?
Marico said Parachute exceeded its initial expectations, delivering 13% volume growth in Q2 FY27, its highest rate in 22 quarters, and gaining about 570 basis points of volume market share to reach 60%. Management cited one selective price reduction in loyalty packs, rapid execution through Project SETU and a thin trade pipeline. It nevertheless reiterated a medium-term Parachute volume-growth expectation of 4% to 6%, distinguishing the current year's result from its normal planning range.
Value-Added Hair Oil recorded 21% value growth and gained 80 basis points of value market share on a moving annual total basis. Marico said mid and premium segments grew in the mid-teens and are both growth- and margin-accretive. In Saffola Edible Oil, revenue rose 6% despite a high single-digit volume decline caused by the withdrawal of select low-margin variants; management expects that reset to be completed over the next two or three quarters while premium products such as cold-pressed oils and Saffola Total grow ahead of the broader franchise.
Got a follow-up? Ask IRIS
How are newer businesses contributing to Marico's mix?
Marico's Foods business grew 45% and crossed an annualised revenue run rate (ARR) of Rs 1,500 crore, while Premium Personal Care crossed Rs 500 crore of ARR. Saffola Foods grew in the early teens, led by oats, muesli and soya chunks, and management said it is generating platform synergies to improve margins across Foods. Premium Personal Care was led by Livon Serums and Parachute Advanced Protein shampoo, which management expects to cross Rs 100 crore of ARR in FY27.
Digital-first personal care had reached about Rs 1,150 crore in ARR, with Beardo expected to cross Rs 400 crore in FY27. Management said Beardo had expanded more than sixfold since Marico took leadership of the brand in 2020 and its profitability had improved by 1,900 basis points. These businesses are relevant to the guidance upgrade because management explicitly identified improved profitability in its diversification portfolio as one of the factors supporting the revised EBITDA outlook.
What is Marico's FY27 revenue and volume outlook?
Marico expects revenue growth in the teens in FY27 and said it should comfortably exceed Rs 15,000 crore of revenue. It also expects India business volume growth to reach double digits for the full year. The Q2 result already included 10% India volume growth, while Parachute's 13% volume growth was supported by selective price cuts in larger loyalty packs rather than additional volume in price-point packs.
International operations provide another growth engine, with Q2 constant-currency growth of 13% and rupee growth of 23%. Vietnam grew 22% in constant currency, while Middle East and North Africa and South Africa each grew 15%, and New Country Development and Exports grew 17%. Bangladesh grew 5% in constant currency amid inflation and softer demand, but management expects gradual improvement in subsequent quarters through consumer activation and a Project SETU-led route-to-market transformation.
Conclusion
Marico's move from about 20% to mid-20s FY27 EBITDA growth guidance was based on operating developments across its portfolio: a 26% first-half EBITDA increase, Parachute's 13% volume growth, premiumisation in hair oils, and greater scale and profitability in Foods and personal care. The company also maintained higher advertising and promotion spending, up 44% in Q2, while reporting a 200-basis-point increase in EBITDA margin to 18.2%.
The next points to watch are the completion of the Saffola Edible Oil portfolio reset over the next two or three quarters, the ability to sustain double-digit India volume growth, and movements in crude-linked inputs and vegetable oils. Management also said it aspires to reach its Rs 20,000 crore revenue target by 2029, one year ahead of its FY30 vision, without a major inorganic component.