










MGFL Mediclaim Disbursements Top FY26 Throughout H1 FY27
Key highlights
- MGFL disbursed Rs 482.9 crore in mediclaim financing in H1 FY27, compared with Rs 333.4 crore in H1 FY26.
- Every monthly mediclaim disbursement from April through September FY27 exceeded the corresponding FY26 level.
- MGFL disbursed 93,392 mediclaim loans in H1 FY27, versus 69,680 loans in H1 FY26.
- MGFL reported a Q2 FY27 average mediclaim ticket size of Rs 50,428 and an internal-rate-of-return yield range of 18% to 24%.
powered by IRIS
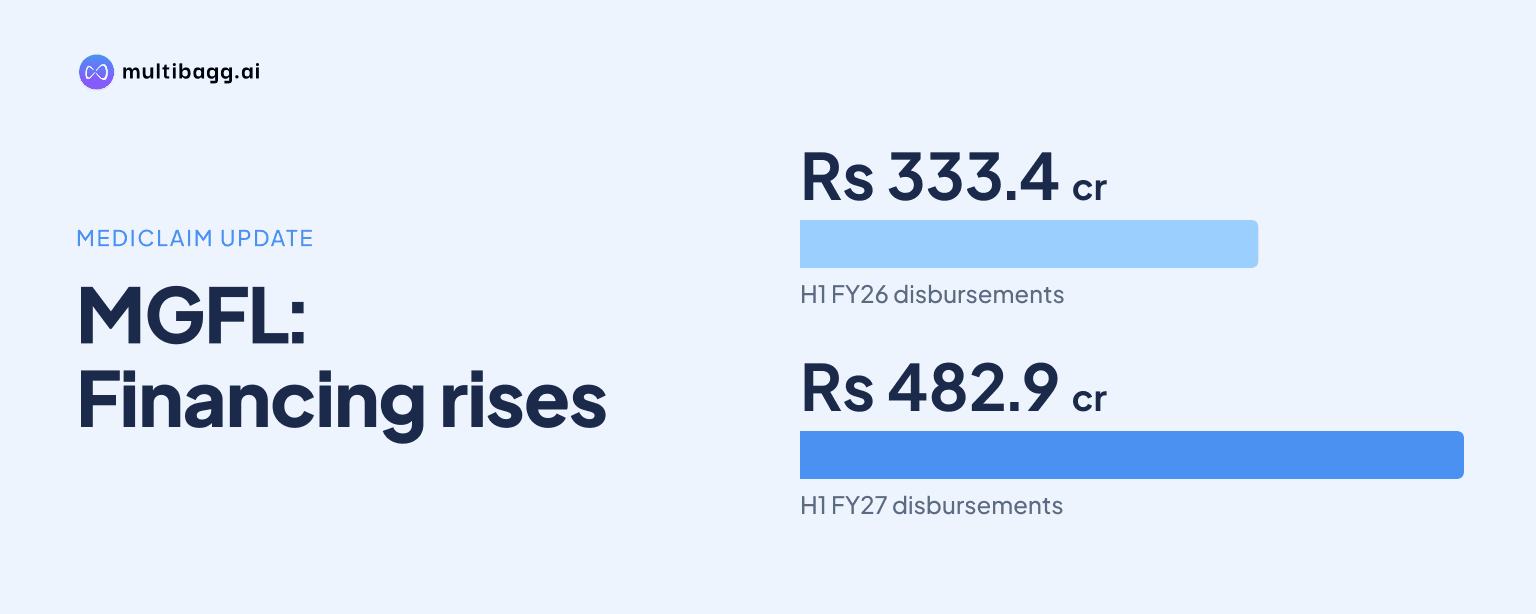
Mufin Green Finance Limited disbursed Rs 482.9 crore in mediclaim financing during H1 FY27, Rs 149.5 crore above Rs 333.4 crore in H1 FY26, with each monthly total from April through September exceeding its corresponding prior-year level. The largest monthly FY27 disbursement was Rs 88.8 crore in both June and July.
Know Mufin Green Finance inside out
Results, valuation, peers and who's buying, in one view.
Did MGFL's mediclaim disbursements exceed FY26 in every H1 FY27 month?
Yes. MGFL reported a higher mediclaim-financing disbursement value in every corresponding month of H1 FY27, from Rs 71.5 crore in August to Rs 88.8 crore in June and July. April disbursements were Rs 75.2 crore against Rs 68.9 crore a year earlier, while May reached Rs 83.1 crore compared with Rs 41.5 crore in FY26.
The largest year-on-year monthly increases came in May and June, at Rs 41.6 crore and Rs 41.0 crore respectively. July maintained the Rs 88.8 crore level, Rs 29.1 crore above the FY26 comparator, before the gap narrowed to Rs 13.0 crore in August and rose to Rs 18.5 crore in September. The six monthly increases together produced the Rs 149.5 crore H1 difference.
How many mediclaim loans did MGFL disburse in H1 FY27?
MGFL disbursed 93,392 mediclaim loans in H1 FY27, compared with 69,680 loans in H1 FY26, an increase of 23,712 loans. Monthly loan counts also exceeded the prior-year comparison in all six months, matching the direction of the disbursement-value trend. June was the peak month, with 17,638 loans disbursed against 10,105 in June FY26.
June also recorded the largest increase in loan count, at 7,533 loans, followed by May with 6,714 and July with 4,648. The smaller increases were 1,467 loans in April, 1,811 in August and 1,539 in September. The presentation therefore shows that higher H1 disbursement value coincided with a greater number of financed policies.
Got a follow-up? Ask IRIS
How does MGFL's mediclaim financing product work?
MGFL pays the full health-policy premium upfront to the insurer after a customer buys a policy at an insurer checkout or partner hospital, and the customer repays MGFL in equated monthly instalments. The process gives the insurer cash on the first day, while MGFL describes collections as fully digital. Its product-process diagram states a repayment period of two to 36 months.
For Q2 FY27, MGFL reported an average mediclaim-financing ticket size of Rs 50,428 and a tenure range of two to 60 months. The presentation does not explain the difference between the two-to-36-month process description and the two-to-60-month tenure metric. MGFL also reported a yield of 18% to 24%, measured as internal rate of return, and more than 10 insurer partners.
The Q2 FY27 unit-economics disclosure includes a CRISIL pool rating of A+ (SO) and a CRISIL loss-given-default measure of 1% plus or minus 0.25%. These are pool-level metrics supplied alongside the product information rather than reported H1 FY27 delinquency, collection-efficiency or actual credit-loss figures. The presentation does not provide mediclaim assets under management or a disbursement split by insurer partner.
What market conditions does MGFL cite for mediclaim financing?
MGFL cites 31% year-on-year growth in retail health premiums in April 2026 as market context for premium financing. It also cites a Policybazaar figure, reported through Outlook Business, that 40% to 45% of first-time health-policy buyers choose monthly payment. Those figures concern the health-insurance market and customer payment preferences, rather than MGFL's own loan performance.
MGFL further cites an industry estimate of 20% to 25% annual growth in premium financing. The presentation notes that goods and services tax on individual health policies has been 0% since September 2025 and says this widened the buyer base. These external figures are market references in MGFL's presentation, not company guidance for disbursements, customer volumes or yields.
MGFL's reported monthly results measure funded health-policy premiums rather than retail health premiums across the market. Its highest reported FY27 monthly disbursement was Rs 88.8 crore in June and July, while August declined to Rs 71.5 crore. Despite that month-on-month decline, August FY27 remained Rs 13.0 crore above August FY26.
Conclusion
MGFL's mediclaim data show growth across both reported measures in H1 FY27: Rs 482.9 crore of disbursements and 93,392 loans, compared with Rs 333.4 crore and 69,680 loans in H1 FY26. The monthly comparison is notable because each of the six FY27 disbursement totals was above its corresponding FY26 amount, rather than the increase being concentrated in one month.
The next disclosures to watch are mediclaim-specific collection efficiency, delinquencies, actual credit losses and assets under management, which the presentation does not report. Further clarity would also be useful on the difference between the two-to-36-month repayment process and the two-to-60-month tenure range disclosed for Q2 FY27.