










Mishtann Foods faces Rs 206.84 crore GST demand, provision query
Key highlights
- Mishtann Foods disclosed a Rs 206.84 crore GST demand that includes interest and penalties.
- Mishtann Foods disclosed a separate Rs 117.44 crore disputed income-tax liability.
- The auditor could not assess provision adequacy for the Rs 206.84 crore GST matter in the September 30, 2026 standalone review.
- The two separate disputed tax matters total Rs 324.28 crore.
powered by IRIS
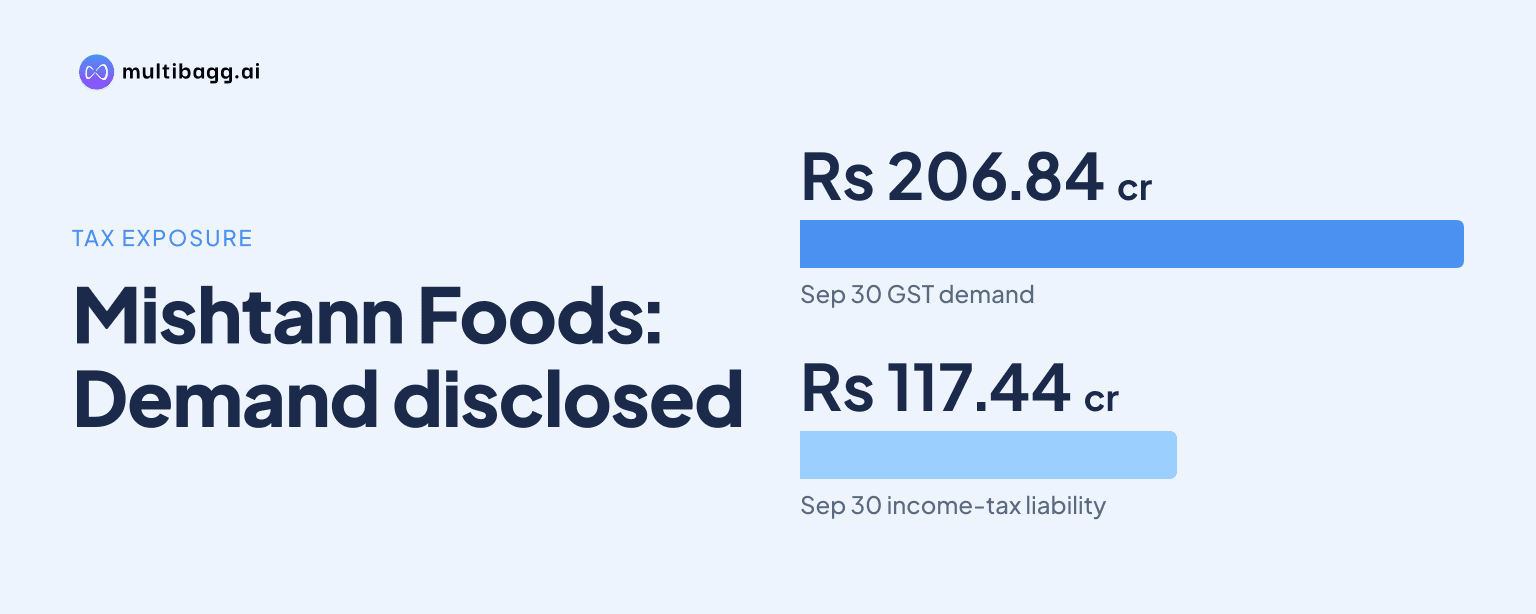
For the quarter ended September 30, 2026, Mishtann Foods Limited disclosed a Rs 206.84 crore goods and services tax demand, including interest and penalties, for which its auditor could not assess the adequacy of the company’s provision, alongside a Rs 117.44 crore disputed income-tax liability.
Know Mishtann Foods inside out
Results, valuation, peers and who's buying, in one view.
What tax demands has Mishtann Foods disclosed?
Mishtann Foods disclosed a Rs 206.84 crore demand under goods and services tax, or GST, provisions, including interest and penalties, and a separate Rs 117.44 crore disputed income-tax liability. The GST matter was included in Annexure-A to the qualified limited-review disclosure accompanying the standalone financial results for the quarter ended September 30, 2026.
The two matters amount to Rs 324.28 crore when added together, although they arise under separate tax laws and are disclosed at different stages of challenge. The GST demand is Rs 89.40 crore higher than the income-tax liability, making it the larger of the two tax exposures identified in the November 4, 2026 filing.
For the Rs 206.84 crore GST demand, Mishtann Foods said it had filed a writ petition before the High Court. The company disputed the demand and said that it had not made a provision for the amount while the petition remained pending.
The Rs 117.44 crore income-tax item is described in the filing as a disputed liability connected with income-tax provisions. Mishtann Foods said it was assessing the liability, considered it doubtful and was taking all possible steps to legally contest the challenge.
Why did the auditor question the GST provision?
The auditor said it was unable to comment on the adequacy of the provision for the Rs 206.84 crore GST demand because the outcome of the High Court writ petition remained pending. The observation was included in the qualified review of Mishtann Foods’ standalone results for the quarter ended September 30, 2026.
This was an unquantified qualification, not an auditor-calculated adjustment to profit, assets or liabilities. The statement on the impact of audit qualifications, dated November 4, 2026, says management was unable to estimate the impact and directs readers to Annexure-A for the reasons and the auditor’s comments.
Mishtann Foods’ stated position was that it had a case in the GST proceedings and therefore had not provided for the Rs 206.84 crore demand. The auditor did not state that the full amount must be paid, but said the available information did not allow it to comment on whether the accounting treatment was adequate.
The question is therefore narrower than the ultimate legal outcome of the GST case. It concerns whether the absence of a provision for a Rs 206.84 crore disputed demand appropriately reflects the potential financial effect in the September 30, 2026 standalone financial statements.
Got a follow-up? Ask IRIS
How does the GST dispute differ from the income-tax matter?
The GST dispute differs because the filing specifically identifies a High Court writ petition for the Rs 206.84 crore demand, which includes interest and penalties. The auditor’s stated inability to assess provision adequacy is also expressly linked to this GST matter in the September 30, 2026 standalone review.
For income tax, Mishtann Foods referred to provisions as at March 31, 2026 in relation to a Rs 117.44 crore disputed liability for financial year 2024-25. Management said it considered the liability doubtful, but the filing does not disclose a court date, settlement date or quantified accounting effect if the challenge is unsuccessful.
The disclosures therefore span two reporting points: the income-tax provision discussion is measured at March 31, 2026, while the GST accounting qualification accompanies the September 30, 2026 results. The filing does not state that either tax matter was resolved, paid or converted into a final liability by November 4, 2026.
Mishtann Foods also said it had the necessary financial resilience to meet the Rs 117.44 crore income-tax liability if required. That management statement does not settle the disputed amount, and the auditor’s disclosed provision-related concern remains focused on the separate Rs 206.84 crore GST demand.
What does the qualification mean for reported results?
The qualification means the auditor did not quantify what effect a provision for the Rs 206.84 crore GST demand could have on Mishtann Foods’ standalone financial position or profit for the quarter ended September 30, 2026. It does not state that the company’s results include a quantified misstatement or that the entire GST amount is immediately payable.
The filing presents an unresolved accounting assessment while the High Court petition remains pending. Until there is a legal outcome or a revised accounting estimate, the Rs 206.84 crore demand remains a disputed matter for which the auditor could not assess the adequacy of Mishtann Foods’ provisioning.
The Rs 117.44 crore income-tax liability carries a different disclosure: management had recorded provisions as at March 31, 2026 while continuing to dispute the liability. The source does not provide a comparable auditor conclusion that quantifies an impact from that direct-tax matter on the September 2026 standalone results.
What should readers watch in Mishtann Foods’ next disclosures?
Readers should watch for an update on the High Court writ petition over the Rs 206.84 crore GST demand, because its outcome could affect both the legal dispute and the accounting assessment. Mishtann Foods disclosed the petition in the November 4, 2026 filing but did not provide a scheduled date for a decision.
Readers should also watch whether Mishtann Foods changes the provision treatment for either the Rs 206.84 crore GST matter or the Rs 117.44 crore income-tax liability. A legal order, revised provision, payment or further auditor comment in financial statements after September 30, 2026 would provide additional information on the two disputed tax items.
Conclusion
Mishtann Foods has disclosed Rs 324.28 crore in two separate disputed tax matters, led by a Rs 206.84 crore GST demand that includes interest and penalties. The central reporting issue is the auditor’s inability to assess whether Mishtann Foods’ non-provision for the GST demand is adequate, rather than a conclusion that the demand has become payable.
The next disclosure to watch is progress in the High Court writ petition on the GST matter and any resulting revision to the September 30, 2026 accounting treatment. Mishtann Foods has also said it is pursuing legal remedies for the Rs 117.44 crore income-tax liability, but the filing gives no timetable for resolution of either dispute.