










Modi Naturals Limited doubles ethanol capacity to 600 KLPD
Key highlights
- Modi Naturals expanded ethanol capacity from 282 to 600 kilolitres per day.
- Modi Naturals secured first-cycle ethanol orders for 7.8 crore litres worth about Rs 494 crore.
- By-products could raise the revenue opportunity linked to first-cycle orders to roughly Rs 600 crore.
- Ethanol reported H1 FY27 revenue of Rs 193.7 crore and EBITDA of Rs 34.9 crore.
powered by IRIS
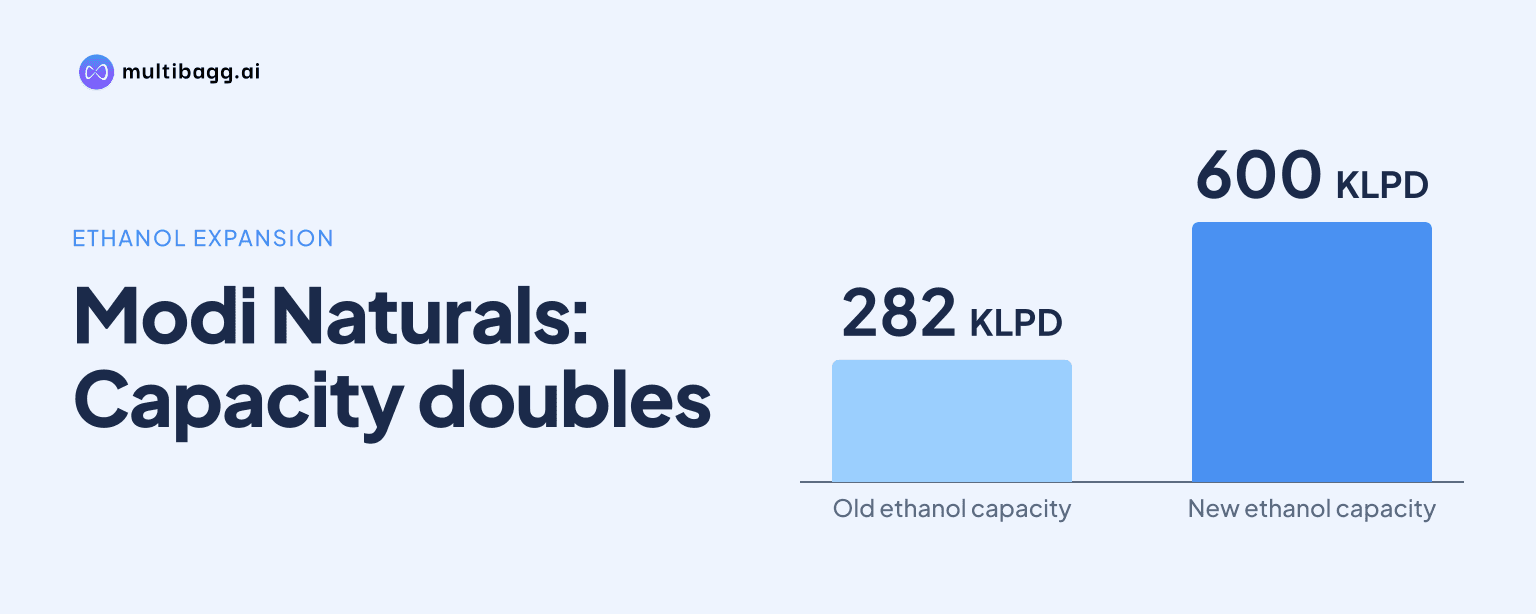
Modi Naturals Limited expanded ethanol capacity from 282 kilolitres per day to 600 kilolitres per day in FY27 and secured first-cycle oil marketing company orders for 7.8 crore litres worth about Rs 494 crore. Management said associated by-product sales could raise the revenue opportunity from those orders to roughly Rs 600 crore.
Know Modi Naturals inside out
Results, valuation, peers and who's buying, in one view.
How much ethanol capacity has Modi Naturals added?
Modi Naturals has added 318 kilolitres per day of ethanol capacity, taking its platform from 282 kilolitres per day to 600 kilolitres per day. Management said the expanded facilities became fully operational around August 2026, so Q2 FY27 included only a partial contribution from the additional capacity.
Management estimated the broad capital expenditure for the ethanol expansion at about Rs 300 crore, while saying it would provide detailed figures separately. Its stated priorities are now to ramp operations, improve capacity utilisation and execute the oil marketing company orders, as grain-based feedstocks such as maize and rice become more prominent in the FY27 ethanol supply cycle.
The timing of commissioning explains why management did not treat Q2 FY27 as a full run-rate quarter for the new capacity. In response to an investor query, it said capacity was fully operational only around August, while Q3 FY27 should reflect the enlarged base for a full quarter and there had been no order slippage.
Management did not disclose a percentage utilisation target for the coming two or three quarters. Instead, it pointed to confirmed volume of 7.8 crore litres for the ethanol supply year from November 1, 2026 to October 30, 2027 as the more relevant measure of expected production and offtake.
What revenue do Modi Naturals' confirmed ethanol orders support?
Modi Naturals' first-cycle oil marketing company orders cover 7.8 crore litres and carry ethanol revenue potential of about Rs 494 crore. Management rounded the ethanol-order opportunity to roughly Rs 500 crore and said by-product sales could take the related revenue potential to about Rs 600 crore.
The Rs 494 crore value covers confirmed first-cycle orders rather than the full potential order book for the ethanol supply year. Management said further tender cycles may occur during the year and that it expects to receive more orders, but no incremental volume or value has been confirmed.
By-products currently account for 18% to 20% of ethanol-division revenue, according to management. Management also confirmed that it had completed development of a higher-nutrition DDGS by-product, which is relevant because the roughly Rs 600 crore opportunity includes sales beyond the contracted ethanol value.
The first-cycle award provides a larger revenue reference point than the division's reported H1 FY27 revenue because the order extends across the ethanol supply year ending October 30, 2027. Management also said some supply timelines had been extended, while maintaining that the company was on track to fulfil existing commitments.
Got a follow-up? Ask IRIS
How did Modi Naturals' ethanol business compare with other divisions?
Modi Naturals' ethanol division was its largest business by both revenue and EBITDA in H1 FY27, reporting Rs 193.7 crore of revenue and Rs 34.9 crore of EBITDA. This exceeded the consumer division's Rs 87.4 crore revenue and Rs 4.9 crore EBITDA, as well as the bulk division's Rs 80.8 crore revenue and Rs 0.7 crore EBITDA.
At company level, H1 FY27 revenue rose 19.3% year on year to Rs 361.9 crore, while EBITDA increased 25.1% to Rs 40.8 crore and profit after tax rose 14.4% to Rs 23.5 crore. Ethanol accounted for more than half of H1 revenue and most of EBITDA, although the first half included only part of the period after full commissioning around August 2026.
In Q2 FY27, Modi Naturals reported revenue from operations of Rs 204.9 crore, up 38.9% year on year, EBITDA of Rs 18.6 crore, up 23.2%, and an EBITDA margin of 9.1%. Management said bulk-division revenue growth in the quarter was largely driven by higher commodity-price realisations, which it expects to moderate as commodity prices correct.
The consumer division faced a different revenue dynamic in H1 FY27. Management said lower olive-oil prices had affected reported sales, while food products were gaining distribution and availability; it expects this growth momentum to become more visible in future revenue.
What could shape Modi Naturals' margins and FY27 execution?
Grain costs, the mix of feedstocks and by-product realisations could shape Modi Naturals' ethanol margins as it ramps 600 kilolitres per day of capacity. Management described 12% to 15% EBITDA as the ethanol division's long-term margin profile, compared with higher margins in recent quarters when grain prices were lower and by-product realisations were better.
Management said elevated grain prices had affected ethanol profitability but that some input-cost moderation had begun to emerge. In discussing the FY27 outlook, it said a higher proportion of FCI rice ethanol could provide fixed pricing and margin structures, reducing dependence on maize economics.
For the consumer division, an analyst cited a sequential raw-material price increase of approximately 52% in Q2 FY27. Management said commodity costs had already improved sequentially in Q3 and could take another quarter to normalise; it expects the division to return to its stated 8% to 9% EBITDA range in a quarter or two.
Management described the bulk division as cyclical and cited a long-term EBITDA range of 5% to 8%, while its H1 FY27 EBITDA was Rs 0.7 crore. It said procurement planning and a leaner inventory model are intended to improve response times to commodity-price changes and working-capital management.
Management reaffirmed confidence in FY27 revenue guidance of about Rs 925 crore to Rs 965 crore, despite H1 FY27 revenue of Rs 361.9 crore. It cited a seasonally heavier second half, progressive ethanol-capacity ramp-up, consumer growth and a more favourable bulk input-cost environment; debt to equity stood at 0.85 times and net working-capital days were 60 as of September 30, 2026.
Conclusion
The expansion to 600 kilolitres per day makes ethanol Modi Naturals' largest reported division and gives the company a larger production platform for the 7.8 crore-litre first-cycle order award. H1 FY27 ethanol revenue of Rs 193.7 crore and EBITDA of Rs 34.9 crore show the division's weight in group results before the expanded capacity had contributed for a full quarter.
The next measures to watch are Q3 FY27 production from the fully operational capacity, the award of any later ethanol tender cycles and grain-cost movement against management's 12% to 15% long-term ethanol EBITDA range. Management also expects new Oleev snacking, grocery and high-protein products within two to three months and continues to target FY27 revenue of Rs 925 crore to Rs 965 crore.