










Mold-Tek Technologies H1 profit rises 4.8 times as revenue rises 64%
Key highlights
- MTTL reported H1 FY 26-27 consolidated PAT of Rs 18.6231 crore, up 4.75 times from Rs 3.9199 crore.
- MTTL's H1 FY 26-27 consolidated revenue rose 63.70% to Rs 120.3549 crore from Rs 73.5222 crore.
- MTTL's consolidated EBITDA margin increased to 24% in H1 FY 26-27 from 11% a year earlier.
- MTTL reported Q2 FY 26-27 consolidated PAT of Rs 9.6189 crore, up 6.83% from Q1 FY 26-27.
powered by IRIS
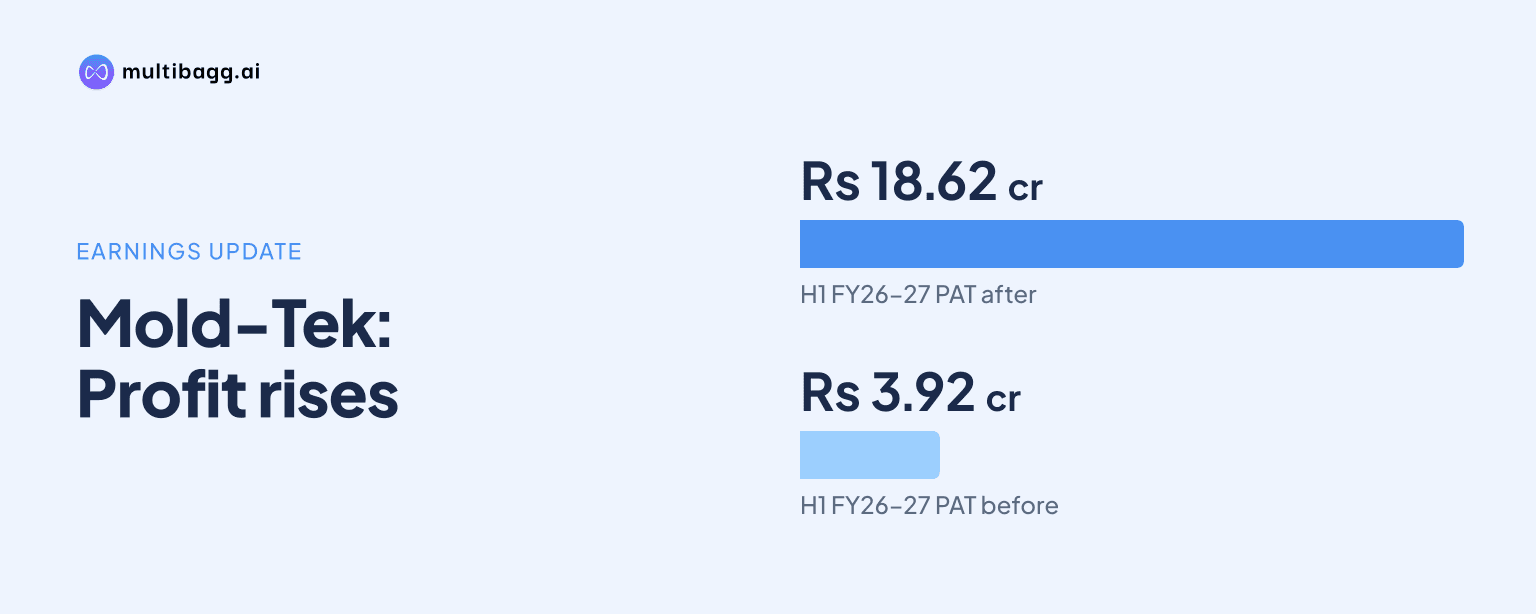
Mold-Tek Technologies Limited reported H1 FY 26-27 consolidated profit after tax (PAT) of Rs 18.6231 crore, 4.75 times H1 FY 25-26, as revenue rose 63.70% to Rs 120.3549 crore and earnings before interest, tax, depreciation and amortisation (EBITDA) margin increased to 24% from 11%.
Know Mold-Tek Technologies inside out
Results, valuation, peers and who's buying, in one view.
How did MTTL perform in H1 FY 26-27?
MTTL increased consolidated revenue, EBITDA and PAT in H1 FY 26-27 compared with H1 FY 25-26. Revenue rose to Rs 120.3549 crore from Rs 73.5222 crore, while EBITDA increased to Rs 28.4886 crore from Rs 8.4019 crore and PAT rose from Rs 3.9199 crore to Rs 18.6231 crore.
The reported margin change explains why profit growth exceeded revenue growth in the half year. MTTL's EBITDA margin increased by 13 percentage points to 24% from 11%, while PAT margin increased by 10 percentage points to 15% from 5%; return on capital employed (ROCE) stood at 34.08% in H1 FY 26-27.
MTTL reported pre-bonus earnings per share (EPS) of Rs 6.47 in H1 FY 26-27, compared with Rs 1.36 in H1 FY 25-26. Post-bonus EPS was Rs 3.23 against Rs 0.68, and management attributed the half-year performance to execution, diversification and expansion into higher-value engineering services.
What changed in MTTL's Q2 FY 26-27 results?
MTTL reported Q2 FY 26-27 consolidated revenue of Rs 60.8127 crore, up 1.51 times from Rs 40.231 crore in Q2 FY 25-26. EBITDA rose 2.45 times to Rs 14.5814 crore from Rs 5.9634 crore, while PAT rose 2.97 times to Rs 9.6189 crore from Rs 3.2352 crore.
Quarterly margins also improved from the prior-year period. Q2 EBITDA margin reached 24%, compared with 15% in Q2 FY 25-26, and PAT margin rose to 16% from 8%; pre-bonus EPS increased to Rs 3.34 from Rs 1.12 and post-bonus EPS rose to Rs 1.67 from Rs 0.56.
MTTL also reported sequential growth against Q1 FY 26-27. Q2 revenue of Rs 60.8127 crore was 2.13% above Rs 59.5422 crore in Q1, Q2 EBITDA of Rs 14.5814 crore was 4.85% above Rs 13.9072 crore, and Q2 PAT of Rs 9.6189 crore was 6.83% above Rs 9.0042 crore.
The company separately disclosed Q2 operational profit excluding foreign-exchange gains and losses of Rs 11.42 crore, compared with Rs 10.39 crore. Chairman and Managing Director J. Lakshmana Rao described this as MTTL's highest-ever quarterly performance on that measure.
How did MTTL's standalone results compare with consolidated results?
MTTL's standalone H1 FY 26-27 revenue was Rs 92.1648 crore, up 38.88% from Rs 66.3643 crore in H1 FY 25-26. Standalone EBITDA rose 265.30% to Rs 30.0227 crore from Rs 8.2186 crore, while standalone PAT increased 439.79% to Rs 20.1931 crore from Rs 3.7409 crore.
Consolidated revenue grew faster than standalone revenue during H1 FY 26-27, at 63.70% versus 38.88%. However, standalone PAT of Rs 20.1931 crore exceeded consolidated PAT of Rs 18.6231 crore; the release provides both results but does not explain the reconciling items.
In Q2 FY 26-27, standalone revenue increased 25.23% to Rs 46.6455 crore from Rs 37.248 crore. Standalone EBITDA rose 157.04% to Rs 15.1092 crore from Rs 5.8781 crore, while standalone PAT rose 222.52% to Rs 10.1659 crore from Rs 3.152 crore.
The Q2 standalone pattern again showed earnings growing faster than sales, with PAT up 222.52% and EBITDA up 157.04% against revenue growth of 25.23%. MTTL's consolidated Q2 PAT margin was 16%, compared with 8% in the year-earlier quarter, though the release does not state standalone margins.
Got a follow-up? Ask IRIS
What did MTTL say drove the margin increase?
MTTL said improved project execution, resource utilisation and business momentum supported H1 FY 26-27 results, when consolidated EBITDA margin reached 24%. Management said its strategy focused on diversification, operational excellence and higher-value engineering services while consolidated revenue increased 63.70%.
Over the past few quarters, MTTL said it implemented automation tools, standardised engineering workflows, performance-linked incentives and structured operational reviews. The company said these initiatives are intended to improve per-engineer productivity, revenue per employee and operating margins, following the increase in H1 EBITDA from Rs 8.4019 crore to Rs 28.4886 crore.
Management also said MTTL entered new civil-engineering domains and added a significant client during Q2 FY 26-27. It said the client addition may support future growth, while the reported Q2 operational profit excluding foreign-exchange gains and losses rose to Rs 11.42 crore.
What are MTTL's plans for its civil and mechanical divisions?
MTTL said its Civil & Structural Division had business momentum from enquiries, project wins and U.S. construction-market demand, with a project pipeline anticipated for Q3 FY 2026-27. During Q2 FY 2026-27, the division secured two data-centre projects, won a convention-centre project and entered the bridge-detailing segment through a new client.
The Civil & Structural Division is forming dedicated estimation, modelling and miscellaneous-detailing teams, according to MTTL. It is also onboarding Pre-Engineered Metal Building clients and expanding Beryl's offerings in residential engineering, permit engineering, plan review and building inspection services.
MTTL said its Mechanical Division is broadening beyond Body-in-White into transmission and distribution, plant engineering, special-purpose machines and utility infrastructure. Management expects the division to improve revenue growth and profitability during H2 FY 2026-27 as diversification initiatives and long-term customer engagements progress.
Beryl has also initiated expansion into additional U.S. states, MTTL said, as part of an integrated engineering offering across the construction lifecycle. Management linked future civil growth during FY 2026-27 to project conversions, customer additions and a larger contribution from higher-value services.
Conclusion
MTTL's H1 FY 26-27 results show profit expanding faster than revenue: consolidated PAT increased 4.75 times to Rs 18.6231 crore, compared with a 63.70% increase in revenue to Rs 120.3549 crore. EBITDA rose 3.39 times to Rs 28.4886 crore as EBITDA margin increased to 24% and PAT margin reached 15%.
The next disclosed milestone is Q3 FY 2026-27, for which MTTL anticipates a healthy Civil & Structural project pipeline. Investors can monitor whether civil-project conversions, new customer additions, Beryl's U.S. expansion and Mechanical Division diversification support management's stated expectation of better H2 FY 2026-27 revenue growth and profitability.