










Mrugesh Trading Limited reports FY26 income of ₹12.41 crore
Key highlights
- Mrugesh Trading reported FY2026 total income of ₹12.41 crore.
- Mrugesh Trading reported a FY2026 net loss of ₹0.24 crore.
- The March 2026 quarter recorded ₹6.51 crore of income and a ₹0.50 crore net loss.
- Mrugesh Trading disclosed a ₹72 crore preferential-warrant fundraising proposal.
powered by IRIS
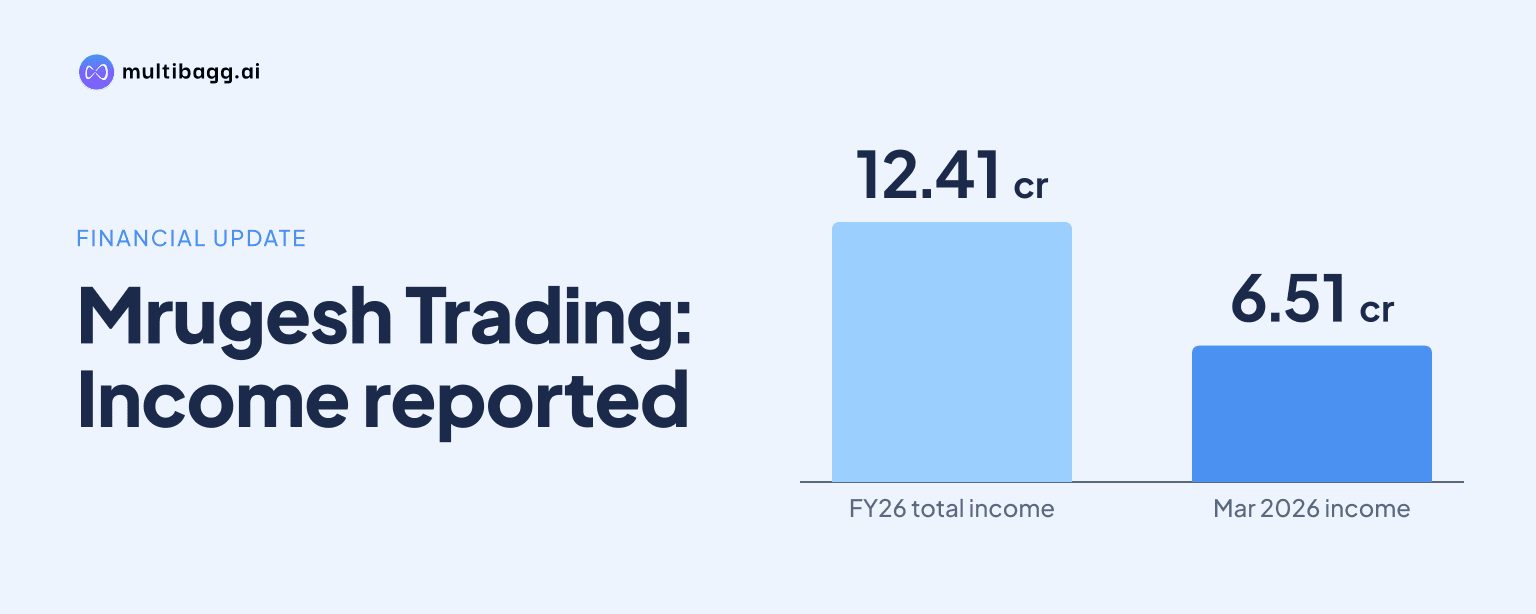
Mrugesh Trading Limited reported total income of ₹12.41 crore for FY2026 and a net loss of ₹0.24 crore, while the auditor issued a qualified opinion that cited unpaid tax and inventory-related verification issues. The results also followed the company's disclosure of a ₹72 crore preferential-warrant fundraising plan.
Know Mrugesh Trading inside out
Results, valuation, peers and who's buying, in one view.
What did Mrugesh Trading report for FY2026?
Mrugesh Trading reported FY2026 total income of ₹12.41 crore and a net loss of ₹0.24 crore in its audited financial results. The annual figures mark an increase in total income from ₹0.00 crore in FY2022, based on the five-year financial summary available for the company.
The reported loss shows that higher income did not translate into a full-year profit. Available quarterly data shows considerable variation in operating income and profit after tax across the periods disclosed, underlining the uneven nature of the company's reported financial performance.
For the March 2026 quarter, total income from operations was ₹6.51 crore and net loss was ₹0.50 crore. This followed income of ₹3.84 crore and profit after tax of ₹0.26 crore in the December 2025 quarter. The June 2026 quarter subsequently reported income of ₹0.43 crore and profit after tax of ₹0.09 crore.
What were the auditor's observations on Mrugesh Trading's accounts?
The auditor issued a qualified opinion on Mrugesh Trading's FY2026 financial results, with the reported observations covering unpaid tax and unverified inventory. The available filing summaries also refer to weaknesses in inventory controls.
A qualified opinion does not mean that every figure in the financial statements is rejected. It means the auditor has identified specific matters that affect, or could affect, the presentation of the accounts and has described those matters in the audit report.
The company's later quarter and half-year filing submitted on 31 October 2026 also carried a qualified limited review report. The filing summary cited matters relating to inventory, sales, advances and loans. These disclosures are relevant because they extend investor attention beyond the annual profit or loss figure to accounting controls and the support available for certain balances.
How does the FY2026 result compare with earlier disclosures?
Mrugesh Trading's disclosed five-year financial summary shows total income rising from ₹0.00 crore in FY2022 to ₹12.41 crore in FY2026, while net profit moved from a loss of ₹0.03 crore to a loss of ₹0.24 crore. The comparison indicates that revenue growth over the period has not yet produced a sustained annual profit.
The company had earlier presented its 41st annual report for the year ended 31 March 2025. In the auditor's report for that year, the auditor said the standalone Ind AS financial statements gave a true and fair view of the company's financial position, profit, comprehensive income, changes in equity and cash flows, based on the information and explanations provided.
The FY2026 reporting period therefore differs from the prior-year audit disclosure because the available FY2026 summary specifically notes a qualified opinion. Investors reading the filings need to distinguish between the company's reported financial results and the auditor's stated qualifications regarding selected accounting and control matters.
Got a follow-up? Ask IRIS
What does the ₹72 crore preferential-warrant proposal mean for investors?
Mrugesh Trading confirmed that it raised, or proposed to raise, ₹72 crore through preferential warrants in connection with its FY2026 results disclosure. Preferential warrants are instruments issued to identified investors that may be converted into equity shares subject to the stated terms and applicable approvals.
The disclosed ₹72 crore amount is substantially larger than FY2026 total income of ₹12.41 crore. That comparison makes the fundraising disclosure important for shareholders because the eventual conversion of warrants, if completed under their terms, can affect the company's equity base and shareholding structure.
The source material does not provide the warrant conversion price, the number of warrants, the identity of allottees, payment milestones or the planned use of proceeds. Those details would be necessary to assess the potential dilution and the precise balance-sheet effect of the transaction.
What recent filings should shareholders monitor?
Mrugesh Trading filed an integrated finance filing for its quarter and half-year results on 31 October 2026, along with a statement of deviation and variation. The board approved the relevant results, while the auditor issued a qualified limited review report, according to the filing summaries.
The company also submitted an annual secretarial compliance report for the year ended 31 March 2026. Separately, shareholders approved the FY2025-26 audited financial statements and auditor appointments at the annual general meeting reported on 30 September 2026.
For investors, the main disclosed issues to follow are future financial results, the status of matters raised in audit qualifications, and further information on the preferential warrants. These are specific filing-based items rather than assumptions about future performance.
Conclusion
Mrugesh Trading's FY2026 disclosures combine a rise in annual income to ₹12.41 crore with a net loss of ₹0.24 crore and a qualified audit opinion. The figures show that the company generated more income than in the earlier five-year comparison point, but profitability and reported accounting-control matters remain central to evaluating the results.
The next disclosures to watch are updates on the qualified observations covering tax, inventory, sales, advances and loans, as well as the terms and progress of the ₹72 crore preferential-warrant proposal. Subsequent quarterly filings will also show whether income and profitability stabilise after the uneven results reported through June 2026.