










Muthoot Capital sees faster NII growth as low-yield assets run off
Key highlights
- Muthoot Capital reported latest-quarter NII of Rs 94.46 crore, including about Rs 14 crore of upfront interest from one transaction.
- Management expects lower-yield assets to decline from about Rs 400 crore currently to about Rs 200 crore by March 2027.
- Muthoot Capital expects AUM to exit the year near Rs 4,200 crore, with about Rs 4,000 crore in higher-yielding assets.
- Bank borrowing costs fell 0.61% in the latest quarter, and management expects a further 0.25% to 0.30% reduction after the AA rating upgrade.
powered by IRIS
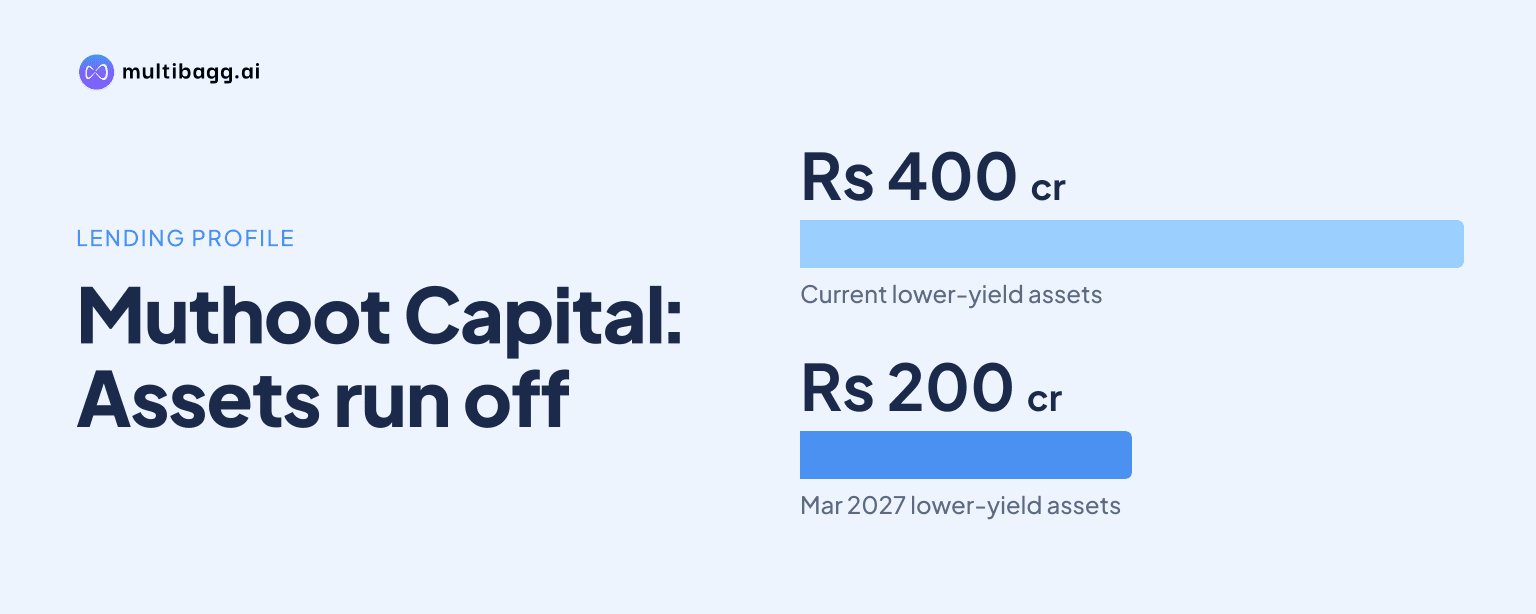
Muthoot Capital Services Limited said in the latest quarter that net interest income, or NII, should grow faster next financial year as lower-yield assets are expected to fall to Rs 200 crore by March 2027 from Rs 400 crore currently. Reported NII was Rs 94.46 crore, including about Rs 14 crore of upfront interest.
Know Muthoot Capital Services inside out
Results, valuation, peers and who's buying, in one view.
Why does Muthoot Capital expect NII growth to accelerate?
Muthoot Capital expects NII growth to accelerate because repayments and its remaining lower-yield portfolio have prevented interest income from moving in step with loan-book expansion. Management reported NII of Rs 94.46 crore in the latest quarter, compared with Rs 77.66 crore in Q1 and Rs 72.15 crore in the same quarter a year earlier. The latest figure included about Rs 14 crore of upfront interest from one direct-assignment transaction, which management said would leave NII of about Rs 80.46 crore excluding that contribution.
Muthoot Capital said loan-book growth does not create equivalent incremental interest income immediately because repayments offset fresh sourcing. Management used a Rs 200 crore two-wheeler disbursement as an illustration: if Rs 150 crore is repaid, only Rs 50 crore is incremental sourcing that can add interest income. It also said funding costs have been declining quarter on quarter, although the older mix of lower-yield co-lending assets reduced the blended lending yield.
How fast will Muthoot Capital's low-yield assets run off?
Muthoot Capital said about Rs 400 crore of its current Rs 3,500 crore assets under management, or AUM, consisted of corporate loans and other lower-yield assets. Management expects this amount to decline to about Rs 200 crore over approximately four quarters. It expects to exit the current financial year with AUM near Rs 4,200 crore, of which about Rs 4,000 crore would be higher-yielding assets.
The expected shift is substantial against the portfolio mix management described for March 2026. Muthoot Capital said it closed that period with AUM of about Rs 2,600 crore, including Rs 800 crore of lower-yield corporate-loan and co-lending assets. Management described that segment as around 40% of the book then, compared with an expected 7% to 8% by March 2027.
Muthoot Capital said the reduction means a much larger proportion of its opening book next financial year could earn higher retail yields. The company expects the Rs 400 crore lower-yield balance in the current book to be about Rs 200 crore by March, leaving Rs 4,000 crore of the projected Rs 4,200 crore portfolio in higher-yielding assets. Management said this mix change is why NII growth could be higher next financial year than in the current year.
Got a follow-up? Ask IRIS
What is lifting Muthoot Capital's portfolio yield?
Muthoot Capital said its blended yield has improved after it stopped originating co-lending business and the existing co-lending book fell by more than 50%. In the comparable quarter of the previous year, co-lending accounted for around 25% of the total book and the blended yield was 18.5%. Incremental co-lending is now almost zero, while the residual co-lending book is around 8% to 9% of AUM, according to management.
The lower-yield assets were originated at roughly 12% to 12.5%, while Muthoot Capital said its internal two-wheeler yield has historically been around 21.5% to 22%. Management said the overall two-wheeler yield increased from 20% to 22% over the past year as co-lending represented a smaller proportion of the book. It expects the current yield level to be sustained, with the full benefit of the runoff emerging over the next two to three quarters.
What loan growth supports Muthoot Capital's NII outlook?
Muthoot Capital had crossed Rs 3,500 crore of AUM and is focused on ending the year around Rs 4,200 crore. An analyst noted that the retail book had grown about 25% year on year and quarterly disbursements were up 21%; management attributed recent growth to an in-house origination scorecard. The scorecard increased approval rates from about 45% to 50% to more than 70%, closer to 75%, according to management.
Muthoot Capital expects used-car and commercial-vehicle loans to account for more than 50%, or closer to 60%, of the overall book over the next two years. Management said these are larger-ticket, longer-tenure loans that can build AUM faster than two-wheelers. It also said the commercial-vehicle business is expected to break even by the end of the year and the used-car business by the first quarter of the following year, following spending on people, credit, collections, sales and infrastructure.
How could funding and credit costs affect Muthoot Capital's NII?
Muthoot Capital said bank borrowing costs declined by 0.61% in the latest quarter. Following its AA rating upgrade, management expects another 0.25% to 0.30% reduction, although it said market conditions do not support an assumption of broad-based cost declines. Management's immediate target is for each new bank borrowing to cost less than the preceding funding, with an additional 0.10% reduction expected by March-end.
Credit costs remain an important variable in the earnings outlook. Muthoot Capital reported fresh flow into non-performing assets, or NPAs, of 0.50% of standard AUM in the quarter, down from 0.85% in the same period a year earlier and 0.67% in Q1. Management said impairment cost was Rs 28 crore in H1 and expects to contain the second-half addition rather than simply doubling the first-half charge, while recovery work continues on older NPAs.
Conclusion
Muthoot Capital's earnings-mix case rests on the runoff of corporate loans and co-lending assets allowing a larger share of AUM to earn higher retail yields. While reported NII of Rs 94.46 crore included about Rs 14 crore of upfront interest, management expects the lower-yield portfolio to fall from Rs 400 crore currently to Rs 200 crore on a projected Rs 4,200 crore March 2027 book.
The next indicators are the pace of the stated two-to-three-quarter yield improvement, progress toward the Rs 4,200 crore year-end AUM objective and whether bank funding costs fall by the additional 0.10% management expects by March-end. Management also expects commercial vehicles to break even by year-end and used cars by the first quarter of the following year, while seeking to constrain impairment costs after Rs 28 crore in H1.