










Muthoot Capital Services GNPA rises to 4.81% in September
Key highlights
- Muthoot Capital Services' GNPA ratio was 4.81% at September 30, 2026, compared with 3.94% at June 30, 2026.
- Gross NPAs fell to Rs 160.11 crore from Rs 212.07 crore a year earlier.
- Muthoot Capital Services held a Rs 25.17 crore management overlay and a Rs 2.50 crore ECL review buffer.
- Four fraud incidents totalled Rs 86.06 lakh and were provided for in full.
powered by IRIS
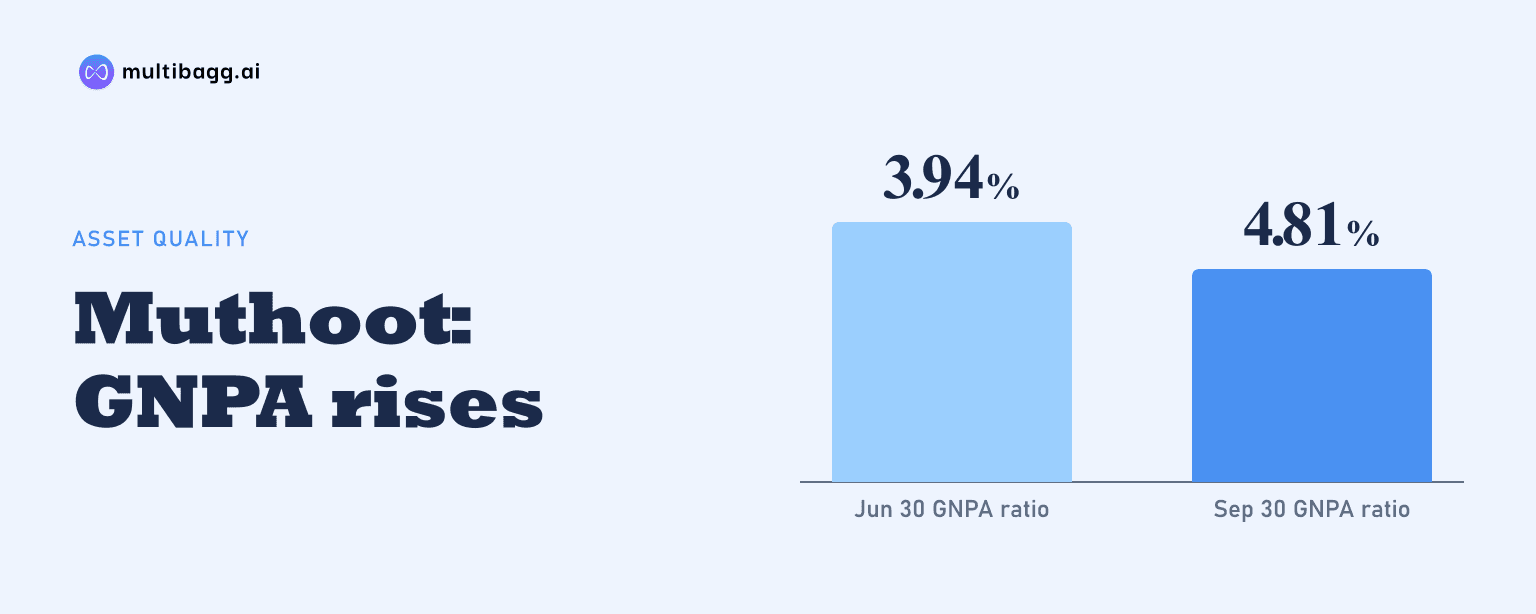
Muthoot Capital Services Limited reported a gross non-performing asset ratio of 4.81% at September 30, 2026, up from 3.94% three months earlier, as gross NPAs rose to Rs 160.11 crore. Gross NPAs were nevertheless Rs 51.95 crore lower than at September 30, 2025, when the ratio was 6.46%.
Know Muthoot Capital Services inside out
Results, valuation, peers and who's buying, in one view.
Why did Muthoot Capital Services' GNPA ratio rise to 4.81%?
Muthoot Capital Services' gross non-performing asset, or GNPA, ratio rose by 87 basis points sequentially because gross NPAs increased faster than advances. Gross NPAs including interest accrual rose to Rs 160.11 crore at September 30, 2026 from Rs 130.07 crore at June 30, while advances increased to Rs 3,325.63 crore from Rs 3,297.11 crore. One basis point equals one-hundredth of a percentage point.
Net NPAs also rose during the quarter, reaching Rs 92.81 crore from Rs 78.09 crore. The net NPA ratio, measured against advances net of Stage 3 provision, increased to 2.85% from 2.36%, while advances net of provisions rose to Rs 3,258.32 crore from Rs 3,245.12 crore.
The September-quarter numbers are balancing figures between the audited year ended March 31, 2026 and year-to-date results through September 30, 2026, which were subject to limited review. The board approved the results on November 5, 2026, and Muthoot Capital Services said its statutory auditors issued an unmodified report.
How did Muthoot Capital Services' asset quality change year on year?
Muthoot Capital Services' asset quality indicators improved from a year earlier despite the latest quarterly increase. Gross NPAs fell to Rs 160.11 crore at September 30, 2026 from Rs 212.07 crore a year earlier, reducing the GNPA ratio by 165 basis points to 4.81% from 6.46%.
Net NPAs declined to Rs 92.81 crore from Rs 97.16 crore over the same period, and the net NPA ratio decreased to 2.85% from 3.07%. Advances net of Stage 3 provision increased to Rs 3,258.32 crore from Rs 3,168.75 crore, expanding the denominator used for the net NPA ratio.
The September position was also below the March 31, 2026 level, when gross NPAs were Rs 233.10 crore and the GNPA ratio was 6.96%. Net NPAs declined from Rs 133.90 crore, or 4.12% of advances net of Stage 3 provision, at March-end to Rs 92.81 crore, or 2.85%, six months later.
Provision coverage was 50.06% at September 30, 2026, compared with 60.00% a year earlier and 50.23% at June 30, 2026. Muthoot Capital Services defines this measure as the provision coverage ratio on NPA principal outstanding, so the year-on-year decline occurred alongside the reduction in gross and net NPAs.
Got a follow-up? Ask IRIS
What provisions and fraud incidents did Muthoot Capital Services disclose?
Muthoot Capital Services said its board-approved policy provides for a 50% provision on credit-impaired assets and aims to keep net NPAs below 6%. It carried an additional management overlay of Rs 25.17 crore at September 30, 2026 and separately maintained a Rs 2.50 crore provisioning buffer for an upcoming periodic review of its expected credit loss model.
Expected credit loss, or ECL, is the impairment method used by Muthoot Capital Services under Indian Accounting Standards, or Ind AS, since April 1, 2019. During the September 2026 quarter, it recognised ECL of Rs 61.47 lakh on a servicer asset created from a direct-assignment transaction.
Muthoot Capital Services classified four fraud incidents involving misappropriation and forgery during the quarter, amounting to Rs 86.06 lakh. It said it provided 100% for these incidents, while the filing did not give a product-wise or geographic breakdown of the four cases.
The direct-assignment transaction had a pool size of Rs 155.90 crore and resulted in a Rs 17.83 crore credit to profit and loss for a servicer asset under Ind AS 109. The Rs 61.47 lakh ECL provision related to that servicer asset is distinct from the full provision reported for the four fraud incidents.
What stressed loans did Muthoot Capital Services transfer to ARCs?
Muthoot Capital Services transferred 61,916 stressed-loan accounts to asset reconstruction companies, or ARCs, during the year. The loans had aggregate principal outstanding of Rs 203.01 crore and net book value of Rs 143.52 crore at transfer, against aggregate consideration of Rs 93.20 crore.
The transferred accounts had a weighted average residual tenor of 7.52 months. Muthoot Capital Services reported no additional consideration from accounts transferred in earlier years and no reversal of excess provisions; it identified the rating of security receipts held as BWR RR1/Assignment by Brickwork Rating.
Separately, Muthoot Capital Services completed one securitisation and two direct-assignment transactions involving loans not in default during the September quarter. Athos Trust 2026 covered 7,104 accounts and Rs 33.12 crore of loans, while HLF MCSL DA SEPT 2026 and NC MCSL DA Sep 2026 involved Rs 43.94 crore and Rs 111.96 crore, respectively.
Each of the three non-default loan transfers retained 10% beneficial economic interest through overcollateralisation and equity, with 100% tangible-security coverage. Their weighted average residual maturities ranged from 1.74 years for Athos Trust 2026 to 1.93 years for HLF MCSL DA SEPT 2026, unlike the 7.52-month tenor disclosed for stressed loans transferred to ARCs.
Conclusion
Muthoot Capital Services reported a mixed asset-quality movement at September 30, 2026: its GNPA ratio increased to 4.81% from 3.94% in June as gross and net NPAs rose sequentially, but both measures remained below September 2025 and March 2026 levels. The company also held a Rs 25.17 crore management overlay and fully provided for Rs 86.06 lakh across four fraud incidents.
The next disclosed matter to watch is Muthoot Capital Services' periodic ECL-model review, for which it has maintained a Rs 2.50 crore additional buffer. Future filings will show whether that review, the Rs 203.01 crore stressed-loan transfer to ARCs and further changes in advances affect NPA ratios or provision coverage.