










NATCO Pharma raises FY27 PAT outlook to ₹775-800 crore on diversity
Key highlights
- NATCO Pharma raised FY27 PAT guidance to ₹775-800 crore from ₹700-750 crore.
- Brazil generated nearly ₹300 crore of revenue for NATCO Pharma in the first half.
- NATCO Pharma estimates a domestic quarterly base of ₹130-135 crore, versus ₹145 crore in the reported quarter.
- NATCO Pharma expects FY27 R&D spending of ₹300-350 crore, or 8-10% of sales.
powered by IRIS
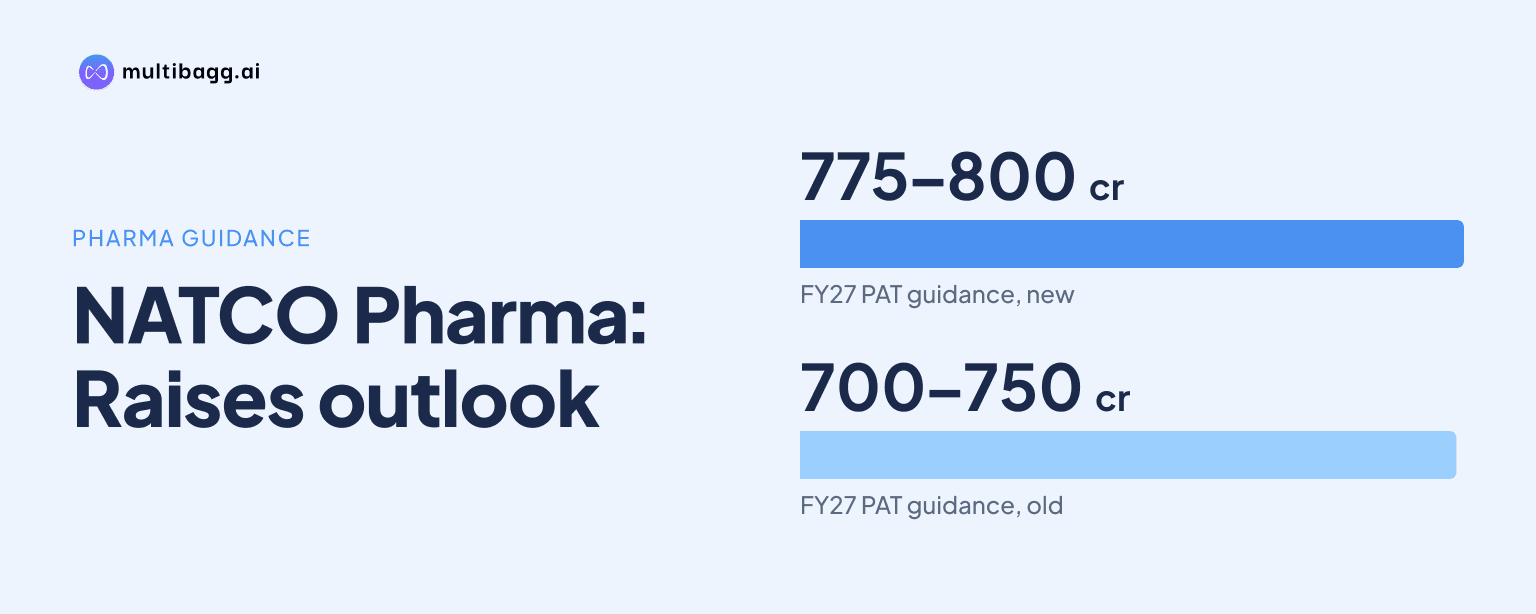
NATCO Pharma Limited expects financial year 2027 (FY27) profit after tax (PAT) of ₹775-800 crore, above its earlier ₹700-750 crore forecast, as management cited earnings from South Africa, Brazil and the United States (US) base business despite no lenalidomide contribution. Management also said the third quarter looked good, while it expected a weaker fourth quarter.
Know Natco Pharma inside out
Results, valuation, peers and who's buying, in one view.
What is NATCO Pharma's revised FY27 PAT outlook?
NATCO Pharma has raised its FY27 PAT expectation to ₹775-800 crore from the ₹700-750 crore range discussed at the start of the year. Vice Chairman and Chief Executive Officer Rajeev Nannapaneni said the company should deliver a result slightly below ₹800 crore, rather than merely maintain the previous forecast. The analyst on the call cited an earlier FY27 revenue outlook of ₹3,400-3,500 crore.
The upgraded PAT range followed an analyst's observation that NATCO Pharma had generated about ₹400 crore of PAT in the first half. Management said the third quarter appeared positive based on what it could then see, while the fourth quarter looked comparatively weak. That quarterly pattern means the revised full-year forecast does not imply that earnings will increase evenly through every remaining quarter.
Which businesses are replacing lenalidomide in NATCO Pharma's earnings?
NATCO Pharma says its FY27 earnings are being supported by South Africa, Brazil and the base US business rather than by lenalidomide. Brazil generated nearly ₹300 crore of revenue in the first half, according to management, although the company does not provide a full geographical revenue breakdown for that market. Management specifically said lenalidomide was not included in the earnings being discussed.
The change is material because management described prior financial years as periods when lenalidomide concentrated earnings to such an extent that gains elsewhere appeared smaller by comparison. In FY27, management characterised the profit mix as relatively more diverse, with meaningful portions coming from the three named businesses. This is management's assessment of the earnings mix, not a disclosed segment-wise PAT split.
South Africa also contributed through NATCO Pharma's associate, Adcock. The call confirmed that ₹78 crore of dividend from associates in cash flow came from Adcock. NATCO Pharma separately noted that Adcock's first-quarter profit contribution benefited from South Africa's flu season, while a ₹6.5 crore one-off amortisation charge related to acquiring an additional 13.25% interest affected the quarter under discussion.
Got a follow-up? Ask IRIS
Can NATCO Pharma sustain its current operating-margin base?
Management said NATCO Pharma's operating-margin base in the first and second quarters is sustainable, based on where the business was then headed. No operating-margin percentage was disclosed on the call, so the statement is a management view rather than a quantified margin target. The company linked the outlook to its broader base business rather than to a single limited-period product opportunity.
In the US, management did not separate the effects of volumes and pricing when asked about the base business. It said the market can generate substantial earnings when competition in a product is limited, but margins can disappear when many competitors enter. NATCO Pharma described the US generics operation as a portfolio, or basket, business and characterised rest-of-world operations as relatively more stable than the US.
Management identified several potential launches for the next few quarters that could affect the product mix. Carfilzomib is expected to launch in the US, with NATCO Pharma holding shared first-to-file status for the 60 milligram strength; Trabectedin is another US opportunity, where it is one of two first-to-file applicants. Olaparib launches are also expected in Brazil and Canada, subject to launch conditions and legal challenges.
What are NATCO Pharma's domestic and research spending plans?
NATCO Pharma estimates its domestic business base at about ₹130-135 crore per quarter, compared with ₹145 crore in the quarter under discussion. Management attributed the difference largely to stocking of Semaglutide by partners, which it does not expect to recur. It also said oncology price cuts should have only a small impact because distributor margins absorbed much of the change, while higher volumes should more than offset it.
Research and development (R&D) spending is expected to be 8-10% of FY27 sales, or about ₹300-350 crore, versus more than ₹400 crore in FY26. The chief financial officer said second-quarter R&D spending was substantially higher than in the first quarter and expected another relatively higher R&D spend in the third quarter. Other expenses also included annual Food and Drug Administration facility and programme fees, legal costs and R&D spending.
NATCO Pharma has also completed a rights issue with overall dilution of 10%, according to management. It said the proceeds were used partly to reduce debt raised for Adcock, with funds also retained for working-capital payments and a possible acquisition. Separately, management said the Crop Health Sciences demerger filing must be resubmitted after the rights issue changed the capital structure, pushing hoped-for completion by four to six months to around the middle of the next calendar year.
Conclusion
NATCO Pharma's revised FY27 PAT range of ₹775-800 crore signals management's view that earnings can exceed the original ₹700-750 crore plan without lenalidomide. The case presented on the call rests on a broader contribution from Brazil, South Africa and the US base business, while the company also says its first- and second-quarter operating-margin base is sustainable.
The next items to watch are whether the favourable third-quarter conditions offset the weaker fourth quarter management expects, and whether Carfilzomib, Trabectedin and Olaparib proceed on the indicated timelines. Investors can also monitor the planned Crop Health Sciences demerger timeline, which management now places around the middle of the next calendar year after a four-to-six-month delay.