










Natural Capsules lifts Q2 EBITDA to ₹3.01 crore on volume
Key highlights
- Natural Capsules reported Q2FY27 revenue from operations of ₹51.15 crore, up 12% year on year.
- Q2FY27 EBITDA was ₹3.01 crore, versus an EBITDA loss of ₹0.88 crore in Q2FY26.
- Q2FY27 EBITDA margin excluding other income rose to 5.88% from negative 1.93% a year earlier.
- Natural Capsules reported a Q2FY27 net loss of ₹4.22 crore, narrower than ₹6.99 crore in Q2FY26.
powered by IRIS
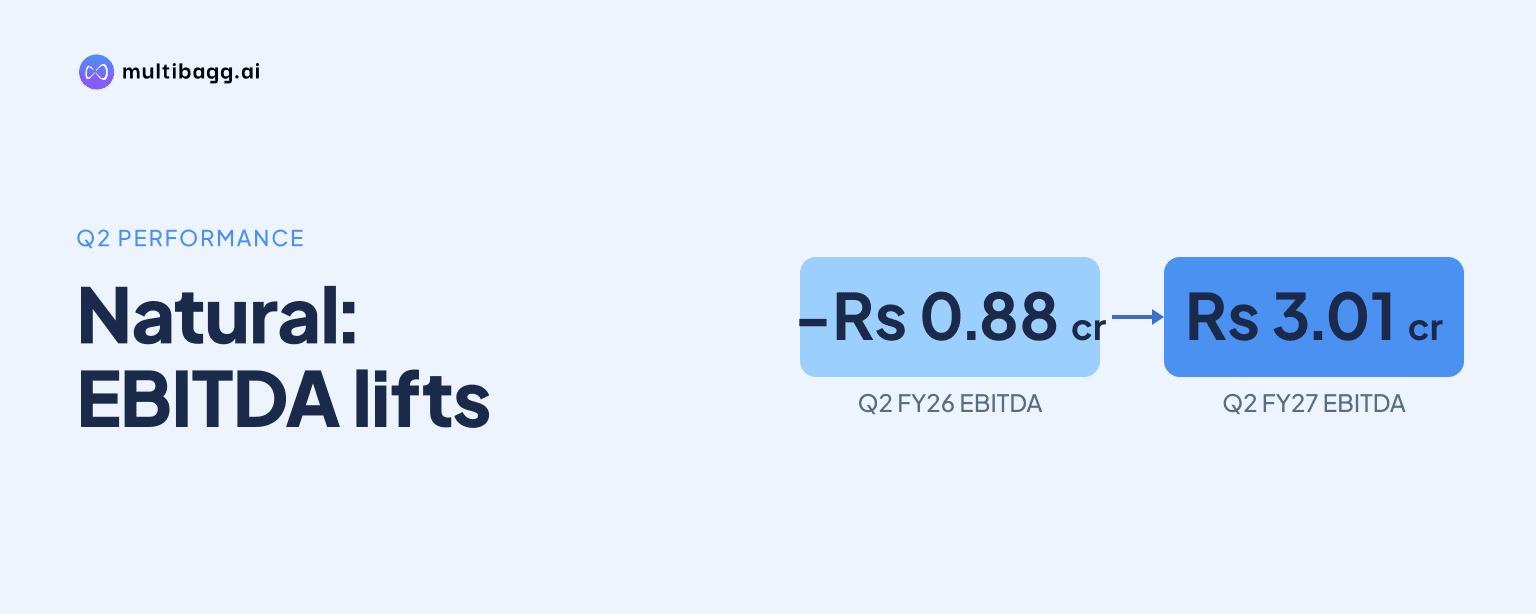
Natural Capsules Limited reported consolidated EBITDA of ₹3.01 crore in Q2FY27, compared with an EBITDA loss of ₹0.88 crore in Q2FY26, after converting an idle HPMC line to gelatin and adding volume. Revenue from operations reached ₹51.15 crore, while the company still recorded a ₹4.22 crore loss after tax.
Know Natural Capsules inside out
Results, valuation, peers and who's buying, in one view.
How did Natural Capsules’ Q2FY27 earnings change?
Natural Capsules moved to earnings before interest, tax, depreciation and amortisation, or EBITDA, of ₹3.01 crore in Q2FY27 from a ₹0.88 crore loss in Q2FY26 and ₹1.12 crore in Q1FY27. Revenue from operations was ₹51.15 crore, up 12% year on year and 5% quarter on quarter, while total operating expenses rose 3% year on year to ₹48.14 crore.
Natural Capsules’ EBITDA margin, excluding other income, reached 5.88% in Q2FY27, compared with negative 1.93% in Q2FY26 and 2.30% in Q1FY27. The margin improved by 781 basis points year on year and 358 basis points sequentially; one basis point equals one-hundredth of a percentage point. Total income rose 12% year on year to ₹51.34 crore, including ₹0.19 crore of other income.
For the first half, Natural Capsules reported revenue from operations of ₹99.86 crore in H1FY27, up 10% from ₹91.01 crore in H1FY26. H1FY27 EBITDA was ₹4.13 crore, compared with an EBITDA loss of ₹1.13 crore in H1FY26, and the margin excluding other income changed from negative 1.24% to 4.14%.
What drove Natural Capsules’ higher capsule-business volumes?
Natural Capsules said its HPMC lines had been idle because orders from the US market were absent, and management converted one line to gelatin during Q2FY27. Management said the conversion created additional gelatin volumes that drove quarterly growth and put unused capacity into production.
Management said an improvement of around 3% in realisations achieved in the previous quarter held through Q2FY27, with the rest of the growth coming from higher volumes. Revenue from operations increased by ₹2.44 crore from Q1FY27 to Q2FY27, although the presentation does not quantify the separate effects of realisations and volumes.
A second HPMC line was being converted at the time of the presentation and is expected by management to add volumes in the second half of FY27. Management also said it added several customers in Q2FY27, including Mankind Pharma, and completed an audit by Zydus Lifesciences, with business from Zydus expected in coming quarters.
Management identified container availability and freight rates as concerns during Q2FY27. It also expects gelatin prices to rise as international coal and oil prices increase, which could lift raw-material costs in the coming quarter; management said it expects to pass such increases to customers and keep EBITDA in the current range over coming quarters.
Got a follow-up? Ask IRIS
Why did Natural Capsules remain loss-making despite positive EBITDA?
Natural Capsules remained loss-making because depreciation and amortisation were ₹4.87 crore and finance cost was ₹2.91 crore in Q2FY27, together exceeding its ₹3.01 crore EBITDA. As a result, loss before tax and exceptional item was ₹4.58 crore, though this narrowed from ₹7.70 crore in Q2FY26 and ₹5.83 crore in Q1FY27.
Profit after tax was a loss of ₹4.22 crore in Q2FY27, improved from losses of ₹6.99 crore a year earlier and ₹5.74 crore in the preceding quarter. Earnings per share were negative ₹4.08, compared with negative ₹6.76 in Q2FY26 and negative ₹5.55 in Q1FY27.
For H1FY27, the net loss narrowed to ₹9.97 crore from ₹13.13 crore in H1FY26, while depreciation and amortisation increased 8% to ₹9.21 crore and finance cost rose 9% to ₹5.69 crore. The half-year figures show that the EBITDA turnaround had not yet offset these costs at the profit-after-tax level.
Natural Capsules’ consolidated total equity was ₹225.84 crore at H1FY27, down from ₹234.72 crore at FY26, while current liabilities increased to ₹141.05 crore from ₹133.73 crore. Cash and cash equivalents were ₹0.44 crore at the end of H1FY27, compared with ₹0.22 crore at the start of the year.
What is Natural Capsules planning for its API business?
Natural Capsules is closing loss-making API business lines and customer accounts while focusing on product registrations and approvals in selected markets, according to management. The company appointed a new chief executive officer for its API operations during Q2FY27, and management said operating changes had followed.
The regulatory plan includes World Health Organization Good Manufacturing Practices, or WHO GMP, certification, for which management expected an audit at any time, and Certificate of Pharmaceutical Product, or COPP, filings for seven products. Validation was complete for four products, remaining filings were scheduled for December, and management expected the COPP process to be complete by March 2027.
Natural Capsules has also planned filings covering 16 molecules for US Drug Master Files, or DMFs, and European Certificates of Suitability, or CEPs. Management said eight filings are due in FY28 and eight in FY29, and it expects a US Food and Drug Administration audit by Q1FY29.
On contract manufacturing, management said the Fermbox Bio programme encountered process challenges and the client took products back to the laboratory. Natural Capsules is pursuing a contract with another organisation and discussing work with other parties, including a contract manufacturing opportunity for its synthesis block, to use available capacity while its own product load develops.
Conclusion
Natural Capsules’ quarterly improvement combined higher capsule volumes from repurposed capacity with a realisation gain that management said held from the previous quarter. The resulting move from negative EBITDA in Q2FY26 to positive EBITDA in Q2FY27 narrowed the loss after tax, but depreciation and finance costs continued to exceed operating profit.
The next disclosed milestones are second-half FY27 volumes from the second converted HPMC line, the remaining COPP filings scheduled for December and management’s expected completion of that process by March 2027. Management also plans eight DMF and CEP filings in FY28 and expects a US Food and Drug Administration audit by Q1FY29.