










National Highways Infra Trust sets NAV at Rs 163.24 per unit
Key highlights
- NHIT reported pre-distribution NAV of Rs 163.24 per unit at 30 September 2026.
- NHIT's SPV enterprise value was Rs 59,299.7 crore under the DCF method.
- NHIT proposed a Rs 540.9 crore distribution, reducing NAV to Rs 160.72 per unit.
- NHIT raised its FY28 WPI growth assumption to 6.00% from 4.00%.
powered by IRIS
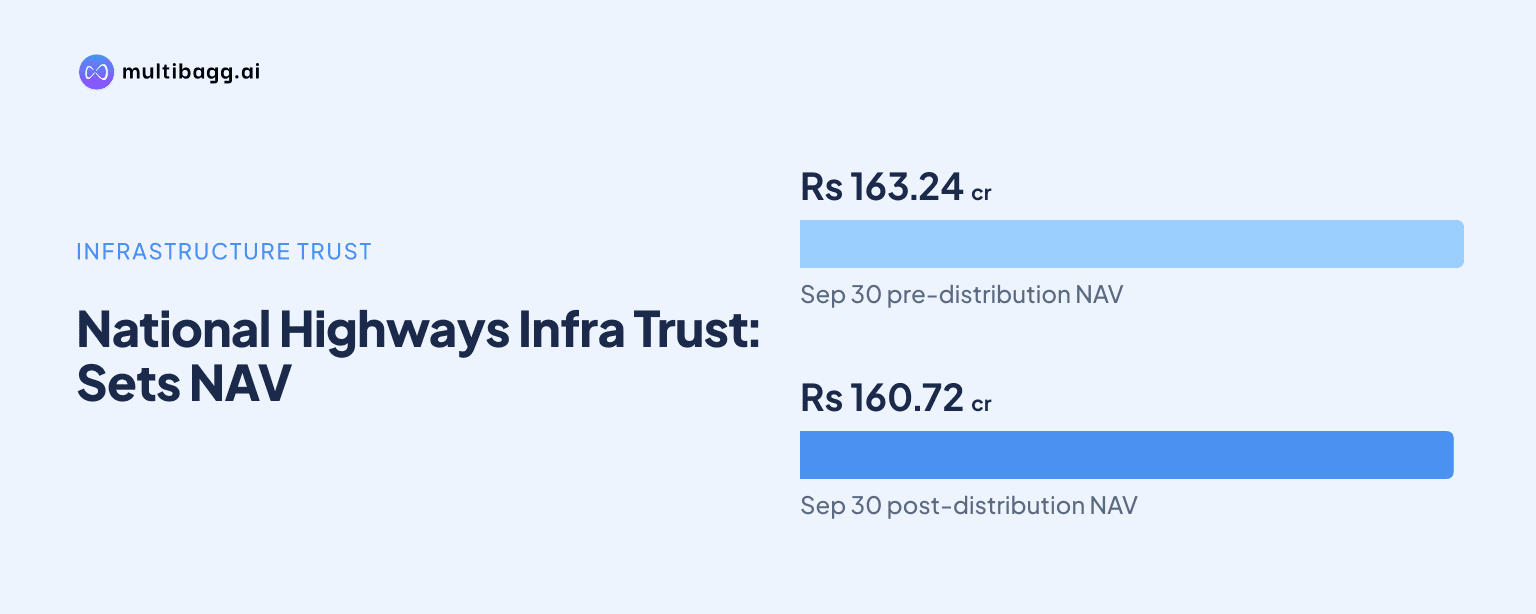
National Highways Infra Trust set its fair-value NAV at Rs 163.24 per unit before distribution at 30 September 2026, based on a discounted-cash-flow enterprise value of Rs 59,299.7 crore for its road-asset SPVs. A proposed Rs 540.9 crore distribution would take NAV to Rs 160.72 per unit.
Know National Highways Infra Trust inside out
Results, valuation, peers and who's buying, in one view.
What was NHIT's NAV at 30 September 2026?
NHIT reported net asset value, or NAV, of Rs 34,910.7 crore before the proposed distribution and Rs 34,369.8 crore after it at 30 September 2026. The distribution reduces NAV by Rs 540.9 crore, or Rs 2.52 per unit, from Rs 163.24 to Rs 160.72 per unit.
The trust-level calculation started with Rs 11,830.4 crore, the fair value of investments in special purpose vehicles, or SPVs. It added Rs 48,205 crore of debt recoverable from SPVs, Rs 38.2 crore of cash and Rs 151.2 crore of other assets, before deducting Rs 25,314.1 crore of liabilities. Cash excluded about Rs 18.8 crore of one-time unutilised funds and unpaid distribution funds in September 2026.
The Rs 11,830.4 crore investment value corresponds with the combined equity value of the SPVs under the discounted cash flow, or DCF, exercise. Management informed the valuer that NHIT proposed the Rs 540.9 crore distribution, rather than the valuation report itself setting a future distribution policy.
How did NHIT value its road assets?
NHIT valued its assets with the DCF method because the road projects have defined concession periods and cash flows that can be estimated through those periods. Ernst & Young Merchant Banking Services LLP, the registered valuer, estimated combined SPV enterprise value at Rs 59,299.7 crore and SPV equity value at Rs 11,830.4 crore as at 30 September 2026.
The valuer did not apply market-price, comparable-company, transaction-multiple or net-asset-value methods to the individual SPVs. None of the SPVs is publicly listed, and the report said there were no comparable listed companies matching their concession periods, road types or regions, nor recent transactions with sufficient public information. It also said net asset value would not capture the businesses' earning capacity.
NHIT owns 28 road projects through three SPVs: NHIT Western Projects Private Limited, NHIT Eastern Projects Private Limited and NHIT Southern Projects Private Limited. The portfolio spans 2,653 kilometres, or 13,315 lane kilometres, across 13 states and operates under Toll-Operate-Transfer concessions with the National Highway Authority of India.
The DCF review used audited financial statements for the western SPV from FY21 to FY26, financial statements for the eastern and southern SPVs for FY25 and FY26, and unaudited financials through 30 September 2026. It also considered projections from 1 October 2026 to concession expiry, traffic and technical reports, concession agreements, and site visits covering all projects.
Got a follow-up? Ask IRIS
Which NHIT portfolios changed between June and September 2026?
All three NHIT SPV portfolios recorded higher enterprise value between June 2026 and September 2026. The eastern SPV had the largest increase, rising Rs 504.4 crore to Rs 18,009.7 crore, compared with increases of Rs 293.1 crore for the southern SPV and Rs 257.2 crore for the western SPV, including R5 assets.
R5 assets, whose value is included in the western SPV enterprise-value presentation, increased to Rs 6,541.7 crore in September 2026 from Rs 6,354.7 crore in June 2026. The western SPV's equity value rose more sharply, to Rs 4,392.1 crore from Rs 3,315.1 crore, alongside a reduction in debt to Rs 17,436.4 crore from Rs 18,224 crore.
For each portfolio, the report identifies lower value from revised cash-flow projections reflecting changes in Wholesale Price Index, or WPI, forecasts and tax rates. It identifies higher value from the roll-forward between valuation dates and lower weighted average cost of capital, or WACC. The report does not quantify each factor's separate monetary contribution.
What assumptions changed in NHIT's September valuation?
NHIT used WACC of 9.70% for the western and eastern SPVs and 9.65% for the southern SPV and R5 assets at 30 September 2026. These were lower than June 2026 rates of 9.80% for the western SPV, 9.85% for the eastern SPV, and 9.75% for the southern SPV and R5 assets.
The September 2026 computation used a 7.18% risk-free rate, a 7.00% equity market risk premium and a long-term debt-to-equity ratio of 50:50. Cost of equity ranged from 13.39% to 13.45%, while post-tax cost of debt ranged from 5.87% to 5.99%. The valuer based the risk-free rate on prevailing yields to maturity for 10-year government securities.
Management increased the WPI growth assumption for FY28 to 6.00% from 4.00% in the prior quarterly exercise, while retaining its 3.50% long-term WPI growth assumption from FY29 onward. Since toll rates use base rates plus macroeconomic factors including WPI, the revised forecast affects projected toll revenue in the DCF model.
Management also reduced the assumed probability of collecting National Highway Authority of India revenue associated with the annual pass from 100%, assessing the revised probability separately for every project. The report does not state those project-level probabilities or quantify their effect. Separately, it says the surcharge on eligible InvIT SPVs using the concessional tax regime increased to 25% from 10% under the Taxation and Other Laws (Amendment) Act, 2026, increasing the applicable effective tax rate from 25.17% to 28.60%.
Conclusion
NHIT's September 2026 valuation places a Rs 59,299.7 crore DCF enterprise value on its 28-project road portfolio and produces pre-distribution NAV of Rs 163.24 per unit. Higher enterprise values across the western, eastern and southern SPVs reflected roll-forward effects and lower discount rates, while revised WPI, tax and annual-pass assumptions affected projected cash flows.
The disclosed item to watch next is the proposed Rs 540.9 crore distribution, which reduces reported NAV to Rs 160.72 per unit after distribution. Future valuations will also depend on management's FY28 WPI assumption of 6.00%, project-specific annual-pass revenue probabilities, tax treatment, traffic forecasts and discount-rate inputs.