










NMDC Q2 profit falls 17% as EBITDA margin drops to 37%
Key highlights
- NMDC’s Q2 FY27 profit after tax fell 17% sequentially to Rs 1,667 crore from Rs 2,007 crore.
- NMDC’s Q2 FY27 EBITDA margin declined to 37% from 41% in Q1 FY27.
- NMDC’s Q2 FY27 iron ore production fell 20% sequentially to 121.55 lakh tonnes.
- NMDC’s Q2 FY27 pellets job-work expenses increased 73% sequentially to Rs 430 crore.
powered by IRIS
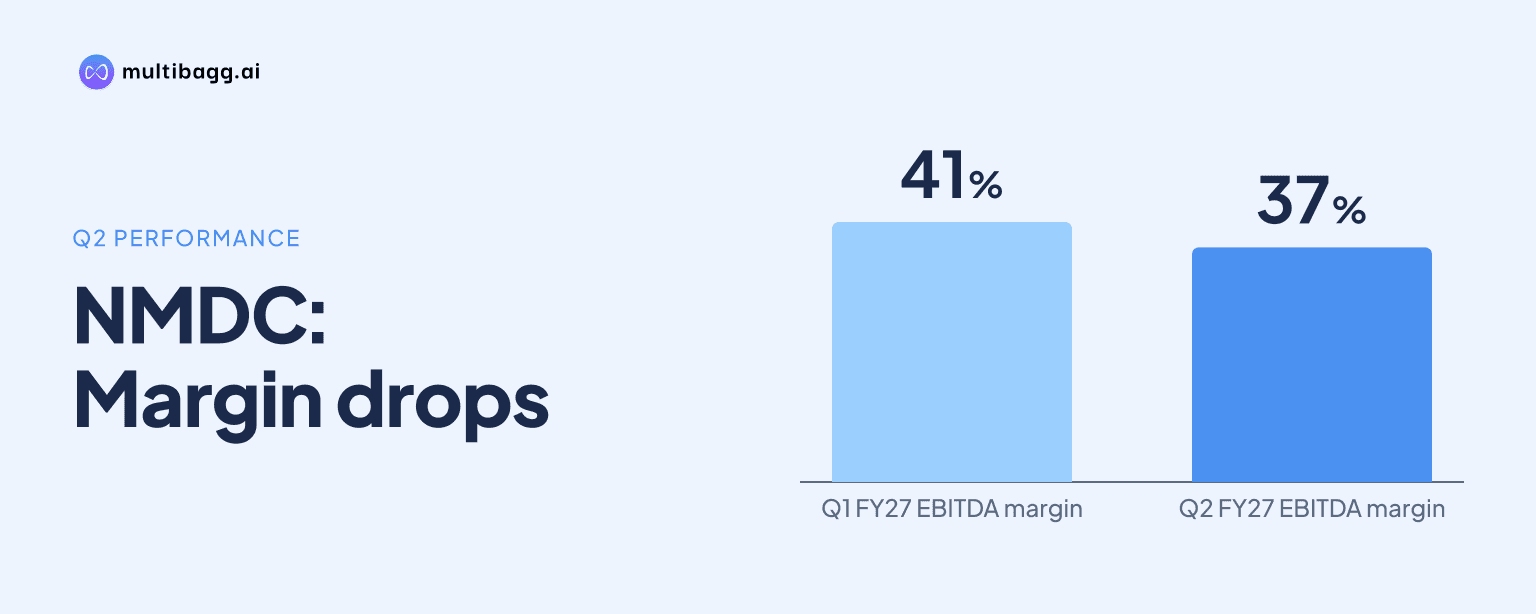
NMDC reported profit after tax of Rs 1,667 crore in the second quarter (Q2) of financial year 2026-27 (FY27), down 17% from the first quarter (Q1), after earnings before interest, tax, depreciation and amortisation (EBITDA) fell 14% to Rs 2,436 crore and margin declined to 37% from 41%.
Know NMDC inside out
Results, valuation, peers and who's buying, in one view.
Why did NMDC’s Q2 FY27 profit fall from Q1?
NMDC’s profit after tax (PAT) declined by Rs 340 crore from Rs 2,007 crore in Q1 FY27 to Rs 1,667 crore in Q2 FY27, a 17% sequential decline. Profit before tax (PBT) fell by Rs 432 crore, or 16%, to Rs 2,260 crore. Revenue from operations decreased by Rs 157 crore, or 2%, to Rs 6,638 crore, while total expenses increased by Rs 422 crore, or 9%, to Rs 4,872 crore.
EBITDA decreased by Rs 381 crore to Rs 2,436 crore in Q2 from Rs 2,817 crore in Q1. The EBITDA margin declined by four percentage points to 37% from 41%. Total income was nearly unchanged at Rs 7,132 crore, down Rs 10 crore, as interest income rose 20% to Rs 254 crore and other income increased 78% to Rs 240 crore.
How did iron ore volumes affect NMDC’s Q2 revenue?
NMDC produced 121.55 lakh tonnes of iron ore in Q2 FY27, down 20% from 151.17 lakh tonnes in Q1 FY27. Iron ore sales declined 11% to 104.83 lakh tonnes from 117.30 lakh tonnes. Iron ore sales revenue fell by Rs 754 crore, or 12%, to Rs 5,754 crore, alongside the lower sales volume and a 1% reduction in average domestic realisation.
Average domestic iron ore realisation was Rs 5,488 per tonne in Q2 FY27, Rs 60 per tonne below the Rs 5,548 per tonne reported in Q1 FY27. Other sales increased by Rs 597 crore to Rs 884 crore, or 208%, limiting the overall decline in revenue from operations to 2%. Q2 production was also 19% above the 102.08 lakh tonnes reported in Q2 FY26, despite the sequential reduction.
Which costs affected NMDC’s Q2 EBITDA margin?
NMDC’s pellets job-work expenses increased by Rs 181 crore, or 73%, quarter on quarter to Rs 430 crore in Q2 FY27. Ore transferred for pellets increased 40% to 11.47 lakh tonnes from 8.19 lakh tonnes in Q1. Operational expenses also rose by Rs 148 crore, or 8%, to Rs 1,948 crore, while production and sales volumes declined from Q1.
Royalty and other levies declined 19% to Rs 1,331 crore, while the additional amount equal to 150% of royalty declined 19% to Rs 1,499 crore. Stock adjustment was negative Rs 336 crore in Q2, compared with negative Rs 1,094 crore in Q1, a Rs 758 crore movement. These line items were reflected in the Rs 422 crore increase in total expenses between the two quarters.
Got a follow-up? Ask IRIS
How did NMDC’s Q2 compare with Q2 FY26?
NMDC’s revenue from operations rose 6% year on year from Rs 6,261 crore in Q2 FY26 to Rs 6,638 crore in Q2 FY27. Average domestic realisation increased 10% to Rs 5,488 per tonne from Rs 4,973 per tonne. Iron ore sales revenue rose 8% to Rs 5,754 crore even as sales volume declined 2% to 104.83 lakh tonnes, while production increased 19% to 121.55 lakh tonnes.
The profit comparison differed from the revenue trend. EBITDA increased 2% to Rs 2,436 crore, but EBITDA margin declined to 37% from 38%. PBT decreased by Rs 10 crore to Rs 2,260 crore and PAT fell by Rs 27 crore, or 2%, from Rs 1,694 crore. Total expenses increased 11% to Rs 4,872 crore, including a 48% rise in operational expenses and a 23% increase in pellets job-work expenses.
What does NMDC’s first-half FY27 performance show?
NMDC’s first half (H1) FY27 iron ore production increased 23% year on year to 272.72 lakh tonnes, while sales were broadly unchanged at 222.13 lakh tonnes compared with 222.33 lakh tonnes in H1 FY26. Ore transferred for pellets increased 43% to 19.65 lakh tonnes. Average domestic realisation rose 7% to Rs 5,520 per tonne, supporting a 7% increase in iron ore sales value to Rs 12,261 crore.
Revenue from operations increased 4% to Rs 13,433 crore in H1 FY27, while PAT increased 0.3% to Rs 3,674 crore from Rs 3,663 crore. EBITDA rose 2% to Rs 5,253 crore, but its margin decreased to 39% from 40% as total expenses increased 8% to Rs 9,321 crore. The first-half comparison shows production growth that was not matched by sales-volume growth.
Conclusion
NMDC’s Q2 FY27 sequential result combined lower production and sales with a higher expense base. Revenue from operations declined 2%, while EBITDA declined 14% and PAT declined 17%; the EBITDA margin fell to 37% from 41%. Compared with Q2 FY26, however, revenue increased 6% and production increased 19%, while PAT was 2% lower.
The disclosed matter to watch is whether the 23% H1 production increase translates into sales growth after H1 sales remained flat at 222.13 lakh tonnes. Pellets transfers rose 43% in H1 and pellets job-work expenses rose 73% sequentially in Q2, while average domestic realisation declined 1% from Q1 to Rs 5,488 per tonne.