










Park Medi World adds 680 beds as H1 EBITDA margin falls
Key highlights
- Park Medi World’s H1 FY'27 revenue rose 22% year on year to Rs 986.7 crore.
- Park Medi World added 680 beds in six months, taking reported capacity to 4,290 beds.
- Park Medi World’s H1 FY'27 EBITDA margin declined to 23.1% from 26.9%.
- Park Medi World’s Q2 FY'27 net profit fell 31% year on year to Rs 54.5 crore.
powered by IRIS
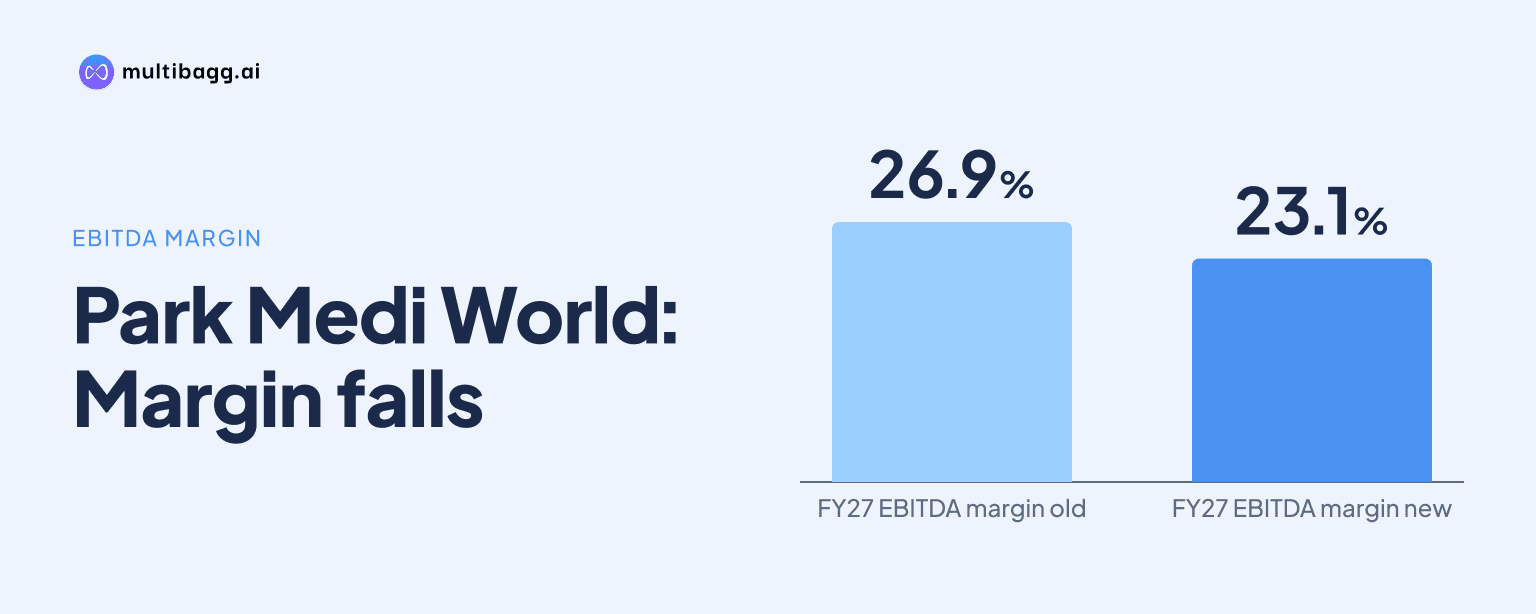
Park Medi World Limited reported H1 FY'27 revenue of Rs 986.7 crore, up 22% year on year, after adding 680 beds in six months, while earnings before interest, tax, depreciation and amortisation (EBITDA) margin declined to 23.1% from 26.9% as new facilities affected occupancy and profitability during their ramp-up.
Know Park Medi World inside out
Results, valuation, peers and who's buying, in one view.
Why did Park Medi World’s H1 EBITDA margin decline?
Park Medi World’s H1 FY'27 EBITDA margin fell 3.8 percentage points to 23.1% because management said recently onboarded capacity had a near-term effect on occupancy and profitability while new facilities ramped up. EBITDA, excluding other income, rose 5% year on year to Rs 227.8 crore, but revenue increased faster, by 22%, to Rs 986.7 crore.
Net profit was Rs 143.1 crore in H1 FY'27, down 1% from Rs 144.2 crore in H1 FY'26, and the net profit margin declined to 14.5% from 17.8%. Management reported that the 14 hospitals excluding Agra, Panchkula and Rudrapur, which were additions in the current calendar year, generated a 26% H1 EBITDA margin and a 17% net profit margin.
The pressure became more pronounced in Q2 FY'27. Quarterly EBITDA declined 10% year on year to Rs 101.7 crore from Rs 112.7 crore, and the margin fell to 19.9% from 27.5%. Q2 net profit declined 31% to Rs 54.5 crore from Rs 78.7 crore, reducing net profit margin to 10.7% from 19.2%.
The sequential comparison also showed revenue growth without a matching earnings increase. Revenue rose to Rs 511 crore in Q2 FY'27 from Rs 475.7 crore in Q1 FY'27, while EBITDA fell from Rs 126.1 crore to Rs 101.7 crore and net profit declined from Rs 88.6 crore to Rs 54.5 crore. Management linked the near-term profitability effect to the time required for new facilities to ramp up.
How did Park Medi World’s volumes and occupancy change?
Park Medi World treated 539,000 patients in H1 FY'27, up 23% from 439,000 in H1 FY'26, while reported occupancy fell to 55.7% from 68.1%. Outpatient department (OPD) patients increased to 482,000 from 392,000, and inpatient department (IPD) patients rose to 57,000 from 47,000, showing volume growth alongside a larger bed base.
Reported bed capacity was 4,290 in H1 FY'27, compared with 3,250 a year earlier, a 32% increase. Management said it added 680 beds during the six months through Rudrapur and Panchkula. The year-on-year capacity increase of 1,040 beds exceeded the growth in patient volumes, providing the operating context for lower occupancy.
Q2 FY'27 patient volume reached 290,000, 29% above 225,000 in Q2 FY'26. OPD patients increased 29% to 259,000 and IPD patients also increased 29% to 31,000. Over the same period, revenue rose 25% to Rs 511 crore from Rs 410.2 crore, but occupancy fell 12.7 percentage points to 55.8% as capacity expanded 32%.
Occupancy was broadly stable sequentially despite the additional 330 beds reported between Q1 FY'27 and Q2 FY'27. It increased to 55.8% in Q2 from 55.6% in Q1, while total patient volume increased by 40,000 from 250,000. The presentation does not disclose occupancy or profitability by individual hospital.
Got a follow-up? Ask IRIS
What expansion does Park Medi World plan in FY'27?
Park Medi World expects total FY'27 bed additions of 1,430, which management said would be about 40% above FY'26 closing capacity and its largest annual addition to date. The disclosed projects are Febris in Delhi, the Palam Vihar expansion in Gurugram, Mehar Hospital in Zirakpur and a Kanpur facility.
The network stood at 17 hospitals and 4,290 beds as of the presentation, including 1,166 intensive care unit (ICU) beds. Park Medi World operates in 15 cities across six states and reports more than 30 super-speciality and specialty services. Its 4,290-bed network comprises 1,450 greenfield beds and 2,840 beds added through acquisitions.
Management identified seamless integration of the new assets, higher utilisation and improved margins as immediate priorities. The presentation lists six greenfield hospitals and 11 acquired hospitals, with Panchkula described as its largest greenfield development and Agra as its largest acquisition. This mix means the planned FY'27 programme combines facility commissioning, an existing-hospital expansion and new hospital assets.
Park Medi World disclosed cash of Rs 371.3 crore against term debt of Rs 177.9 crore at the H1 FY'27 update. Management said this balance-sheet position could fund growth, but the presentation does not provide a capital-expenditure budget, project-wise funding allocation or timetable beyond the FY'27 addition target.
Conclusion
Park Medi World’s H1 FY'27 results show revenue and patient growth occurring alongside a capacity ramp-up that reduced reported occupancy and margins. Revenue increased 22% to Rs 986.7 crore and patient volume rose 23% to 539,000, while capacity increased 32% year on year to 4,290 beds, EBITDA margin fell to 23.1%, and H1 net profit declined 1% to Rs 143.1 crore.
The next disclosed milestone is management’s planned 1,430-bed addition in FY'27 through projects in Delhi, Gurugram, Zirakpur and Kanpur. Management has identified integration, utilisation and margins as priorities, so reported occupancy after the Q2 FY'27 level of 55.8% and the earnings contribution from the new facilities remain the key disclosed matters to watch.