










Powerica's Rs 1,950 crore DG-set book is data-centre led
Key highlights
- Powerica's Cummins-powered DG-set order book was about Rs 1,950 crore in October 2026.
- Data-centre orders made up about Rs 1,200 crore of Powerica's disclosed Cummins-powered DG-set order book.
- Powerica's H1FY27 revenue from operations rose 12.5% year on year to Rs 1,627.7 crore.
- Powerica's generator-set EBITDA margin was 6.5% in H1FY27, compared with 10.1% in H1FY26.
powered by IRIS
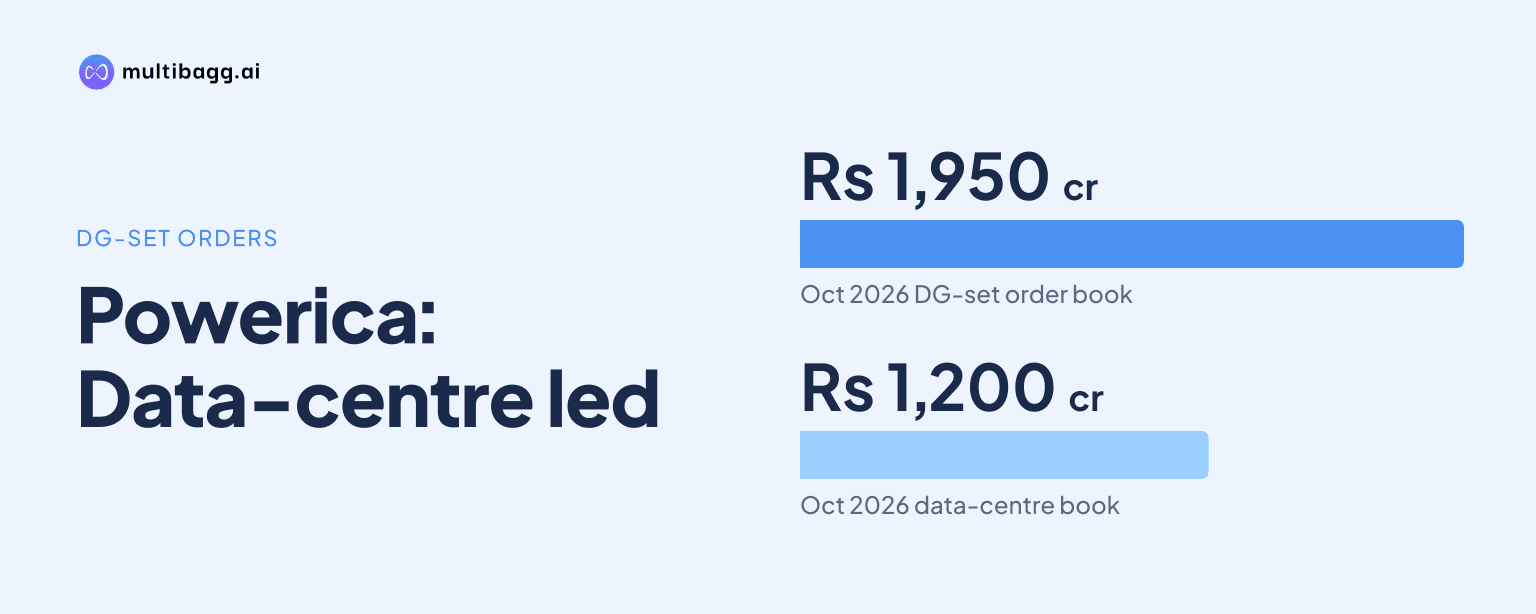
Powerica Limited reported a Cummins-powered diesel generator-set order book of about Rs 1,950 crore as of October 2026, including about Rs 1,200 crore from data centres. Data centres therefore represented about 62% of the disclosed pipeline, while management said engine-supply constraints and renewed steel-price increases could keep near-term margins under pressure.
Know Powerica inside out
Results, valuation, peers and who's buying, in one view.
How large is Powerica's Cummins-powered DG-set order book?
Powerica's Cummins-powered diesel generator-set, or DG-set, order book stood at about Rs 1,950 crore in October 2026, of which about Rs 1,200 crore related to data centres. The remaining Rs 750 crore is the calculated balance of the disclosed order book after deducting the data-centre component, rather than a separately reported category.
Powerica said demand was strong for medium- and high-horsepower DG sets, led by data centres, manufacturing and infrastructure, while low-horsepower demand was moderate. Its generator-set portfolio spans 7.5 kilovolt-amperes, or kVA, to 10,000 kVA, covering equipment for primary and standby power applications.
The Rs 1,950 crore disclosure covers only Cummins-powered DG sets, not Powerica's full generator-set or wind-power operations. The release did not disclose a consolidated group order book, the order-book value of its medium-speed large generator, or MSLG, offerings with Hyundai, or a delivery schedule for the Cummins-powered orders.
How concentrated is Powerica's DG-set pipeline in data centres?
Powerica's disclosed Cummins-powered DG-set pipeline is concentrated in data centres because about Rs 1,200 crore, or roughly 62%, of the Rs 1,950 crore order book is from that customer category. The calculation indicates that the data-centre portion exceeds the balance of the disclosed book by about Rs 450 crore.
The order-book mix matches management's description of shifting demand towards medium- and high-horsepower equipment in October 2026. However, the release does not identify individual data-centre customers, capacity ratings, project locations, delivery dates or whether the equipment will serve primary or standby applications.
This pipeline should not be treated as revenue already recorded for the half year ended September 30, 2026. Powerica reported that generator sets contributed 80.6% of consolidated revenue in H1FY27, compared with 80.5% in H1FY26, but it did not link any specified part of that revenue to the Rs 1,200 crore data-centre order book.
Within group revenue, Cummins-powered DG sets contributed 69.7% in H1FY27, up from 63.6% a year earlier. MSLG offerings associated with Hyundai contributed 1.0%, down from 5.1%, while allied business contributed 9.9%, down from 11.8%, showing that Cummins-powered equipment accounted for a larger share of the generator-set revenue mix.
What does the order book mean for Powerica's FY27 outlook?
Powerica said its FY27 growth outlook was unchanged and management continued to expect double-digit revenue growth, supported by the DG-set order book. This is management's forward-looking expectation, and the release does not quantify FY27 revenue or state how much of the Rs 1,950 crore pipeline will be executed during the year.
Consolidated revenue from operations rose 12.5% to Rs 1,627.7 crore in H1FY27 from Rs 1,447.4 crore in H1FY26. Q2FY27 revenue was Rs 847.6 crore, up 1.9% from Rs 831.5 crore in Q2FY26 and 8.7% from Rs 780.1 crore in Q1FY27.
The Cummins-powered DG-set order book equals about 1.2 times H1FY27 consolidated revenue, although the two measures cover different scopes and periods. Reported earnings before interest, tax, depreciation and amortisation, or EBITDA, increased 6.5% to Rs 234.8 crore in H1FY27, while profit after tax was nearly unchanged at Rs 135.3 crore against Rs 134.6 crore a year earlier.
Got a follow-up? Ask IRIS
What is affecting Powerica's margins as orders are executed?
Powerica said engine-supply constraints and higher input costs affected its Q2FY27 operating environment, even as prior price revisions improved generator-set margins sequentially. Management identified steel as one of its largest raw-material inputs and said suppliers had announced further price increases after steel prices rose again.
Generator-set EBITDA margin rose 180 basis points sequentially to 7.4% in Q2FY27 from 5.6% in Q1FY27. A basis point is one-hundredth of a percentage point. Despite that improvement, H1FY27 generator-set EBITDA margin was 6.5%, below the 10.1% reported in H1FY26.
At the consolidated level, gross margin declined to 35.1% in Q2FY27 from 38.6% in Q2FY26, while EBITDA margin declined to 15.2% from 15.9%. Profit after tax margin was 8.4%, compared with 10.1% a year earlier, alongside Q2 profit after tax falling 15.6% to Rs 70.9 crore.
Management said margins were likely to remain under pressure in the near term until the next price revisions take effect with execution of new orders. The release does not state the size or timing of those future revisions, nor does it quantify the effect of engine availability on deliveries from the October 2026 order book.
How does wind power contribute alongside Powerica's DG-set business?
Powerica's wind-power segment contributed 19.4% of H1FY27 revenue, compared with 19.5% in H1FY26, while its EBITDA margin rose to 47.4% from 37.3%. The segment therefore remained close to one-fifth of group revenue as its reported segment margin increased year on year.
Within wind power, the independent power producer, or IPP, business contributed 11.4% of group revenue in H1FY27, up from 8.6% in H1FY26. Engineering, procurement and construction, or EPC, and operation and maintenance, or O&M, for balance of plant, or BoP, contributed 8.0%, down from 10.9%, and management said wind generation is typically higher in H1 than H2 because of seasonality.
Powerica received a letter of intent from Gujarat Urja Vikas Nigam Limited, or GUVNL, in October 2026 for a 50-megawatt wind-power project secured through competitive bidding in July 2026. The release did not state the project's value, tariff, capital expenditure, commissioning date or expected revenue contribution.
The company said its operational wind portfolio comprises 12 projects supported by long-term fixed-tariff power purchase agreements with GUVNL and Solar Energy Corporation of India, generally with 25-year terms. It also reported EPC experience across 12 wind projects with aggregate capacity of 450.40 megawatts and BoP O&M services at 10 projects with aggregate capacity of 296.50 megawatts.
Conclusion
Powerica's October 2026 disclosure shows that data centres form the majority of its Rs 1,950 crore Cummins-powered DG-set order book, consistent with management's reported demand for medium- and high-horsepower equipment. H1FY27 revenue increased 12.5%, but generator-set EBITDA margin declined to 6.5% from 10.1% as higher input costs and engine-supply constraints affected the business.
The next disclosed factors to watch are the execution of new orders after further price revisions, engine availability for DG-set deliveries and progress on the 50-megawatt GUVNL wind project for which Powerica received a letter of intent in October 2026. Management has retained its FY27 expectation for double-digit revenue growth, but did not provide an order-book conversion timetable or a quantified revenue target.