










Raghunath International fair-value impact cannot be quantified
Key highlights
- Reviewers said the September 30, 2026 fair-value impact on specified balances was not ascertainable.
- Consolidated non-current investments were Rs 5.17 crore at September 30, 2026, versus Rs 5.13 crore at March 31, 2026.
- Standalone non-current investments remained Rs 76.46 lakh at both September 30, 2026 and March 31, 2026.
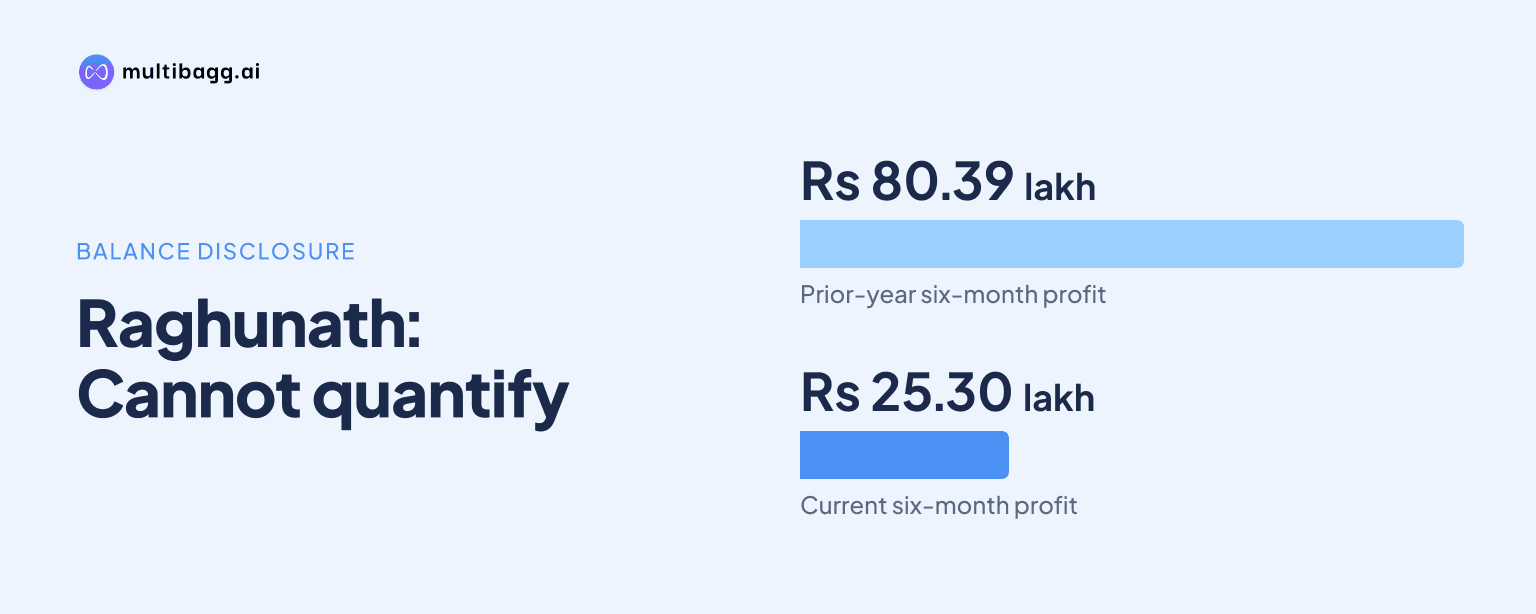
- Consolidated six-month profit fell to Rs 25.30 lakh from Rs 80.39 lakh a year earlier.
powered by IRIS
Raghunath International Limited’s standalone and consolidated reviewers said on November 5, 2026 that the financial impact of carrying specified equity investments at cost instead of fair value could not be ascertained as of September 30, 2026, when consolidated non-current investments were reported at Rs 5.17 crore.
Know Raghunath International inside out
Results, valuation, peers and who's buying, in one view.
What did the reviewers flag at Raghunath International?
Raghunath International’s standalone reviewer said the company had recognised non-current equity investments at cost in its unaudited standalone balance sheet as at September 30, 2026. The November 5, 2026 review report described this treatment as a departure from Indian Accounting Standard 109, or Ind AS 109, Financial Instruments, for the quarter and six months ended September 30, 2026.
The reviewer said Ind AS 109 requires equity-share investments other than subsidiaries, associates and joint ventures to be recognised at fair value through profit or loss or fair value through other comprehensive income. However, the report states that Raghunath International carried non-current equity investments, including those in subsidiaries, associates and joint ventures, at cost at September 30, 2026.
The consolidated review report identified the same accounting treatment in the consolidated unaudited balance sheet at September 30, 2026. It said the impact of the difference between fair value and cost on non-current investments, other equity, other comprehensive income and deferred tax was not ascertainable from the financial information presented.
Neither review report provides a fair value for the investments, the cost of each holding, or an estimated adjustment to profit, equity, tax or comprehensive income for September 30, 2026. The filing therefore does not provide a basis for calculating revised earnings or a revised balance sheet after a fair-value adjustment.
Which Raghunath International balances could be affected?
Raghunath International reported consolidated non-current investments of Rs 5.17 crore at September 30, 2026, compared with Rs 5.13 crore at March 31, 2026. The balance increased by Rs 3.86 lakh, but the reviewer did not state whether that movement reflected any change in fair value because the investments remained recorded at cost.
Standalone non-current investments were Rs 76.46 lakh at September 30, 2026, unchanged from March 31, 2026. The difference between the consolidated and standalone investment balances is consistent with the consolidated accounts including the associate identified by the reviewer, Raghunath Builders Private Limited.
Other equity in the consolidated balance sheet stood at Rs 12.48 crore at September 30, 2026, up from Rs 12.23 crore at March 31, 2026. The consolidated reviewer explicitly included other equity, other comprehensive income and deferred tax among the balances for which the fair-value-versus-cost effect could not be ascertained.
Raghunath International’s consolidated total assets were Rs 19.31 crore at September 30, 2026, against Rs 19.00 crore at March 31, 2026. Other financial assets were Rs 11.45 crore, current income tax was Rs 1.24 crore and cash and cash equivalents were Rs 16.65 lakh, but the review report confines its unascertainable-impact observation to investments, other equity, other comprehensive income and deferred tax.
Got a follow-up? Ask IRIS
How did Raghunath International’s reported results change?
Raghunath International reported consolidated profit for the six months ended September 30, 2026 of Rs 25.30 lakh, down from Rs 80.39 lakh in the six months ended September 30, 2025. Total comprehensive income was also Rs 25.30 lakh for the latest half year, while the reviewer said any effect on other comprehensive income from the investment measurement issue was not ascertainable.
For the three months ended September 30, 2026, consolidated profit was Rs 11.45 lakh, compared with Rs 69.77 lakh a year earlier and Rs 13.85 lakh in the quarter ended June 30, 2026. Basic and diluted earnings per share were Rs 0.23 in the September 2026 quarter, versus Rs 1.40 in the September 2025 quarter.
Segment disclosure shows real-estate-development revenue of Rs 12.87 lakh in the six months ended September 30, 2026, down from Rs 96.50 lakh a year earlier. Other unallocable income rose to Rs 44.46 lakh from Rs 40.21 lakh, but total segment revenue fell to Rs 57.33 lakh from Rs 1.37 crore.
Raghunath International’s share of associate profit was Rs 3.87 lakh for the six months ended September 30, 2026, compared with Rs 2.56 lakh a year earlier. The consolidated reviewer said it had not reviewed the associate’s interim financial results and relied on unaudited information supplied by management, while stating that the associate’s results were not material to the group.
What assurance did the review reports provide?
Raghunath International’s reports were limited reviews under Standard on Review Engagements 2410, or SRE 2410, rather than audits. The standalone report dated November 5, 2026 says a review principally involves inquiries and analytical procedures, gives less assurance than an audit and does not result in an audit opinion.
Both reviewers said that nothing had come to their attention to suggest the results did not make disclosures required by Regulation 33 of the Securities and Exchange Board of India Listing Obligations and Disclosure Requirements Regulations, 2015, or that they contained a material misstatement. That conclusion appeared alongside the separately stated Ind AS 109 departure and the inability to quantify its effect.
The board took the unaudited consolidated results for the quarter and half year ended September 30, 2026 on record on November 5, 2026 after audit committee review. The notes say Raghunath International adopted Ind AS from April 1, 2026 and prepared the September 2026 quarter and half-year results under Ind AS 34, Interim Financial Reporting.
Raghunath International reported no investor complaints pending at the beginning or end of the September 2026 quarter, and none received or disposed of during the quarter. This disclosure does not set out a valuation method, a restatement proposal, a timetable for fair-value measurement or a management estimate of the accounting difference.
Conclusion
The filing shows that Raghunath International’s reviewers identified an Ind AS 109 departure in the use of cost for equity investments and could not determine the resulting effect on specified balances. The matter relates to reported consolidated non-current investments of Rs 5.17 crore as at September 30, 2026, as well as other equity, other comprehensive income and deferred tax.
The next results filing after the September 30, 2026 half-year report approved on November 5, 2026 is the disclosed point to watch. It may show whether Raghunath International provides fair-value measurements, quantifies the effect on the named balances, changes the accounting treatment or repeats the reviewers’ limitation.