










Refex targets Rs 1,300-1,400 crore wind revenue in FY27
Key highlights
- Refex targets Rs 1,300-1,400 crore of FY27 wind-business revenue.
- Management maintained wind EBITDA margin guidance of 4-5% and PAT margin guidance of 2.5-3%.
- Wind EBITDA improved to Rs 11.32 crore in the September 2026 quarter from a Rs 3 crore loss in the previous quarter.
- Refex expects its indigenous wind manufacturing plant to be operational within 12-14 months.
powered by IRIS
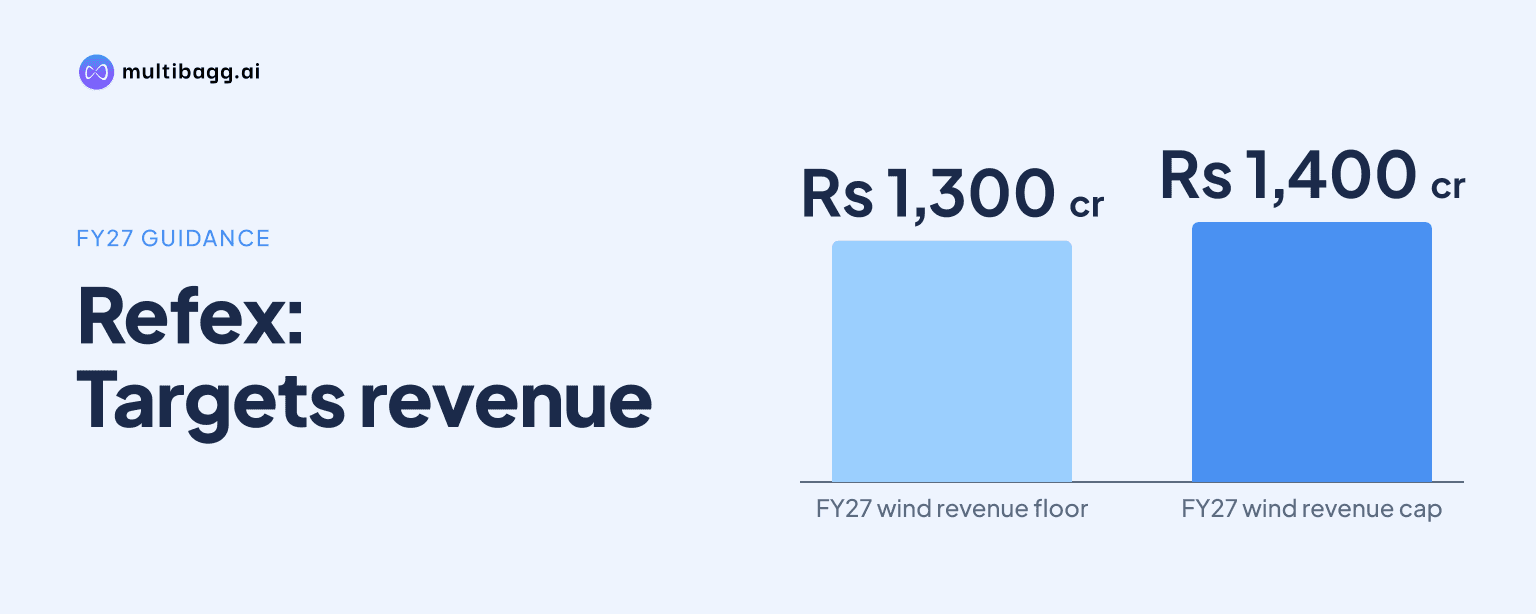
Refex is targeting Rs 1,300-1,400 crore of wind-business revenue in FY27 and an earnings before interest, tax, depreciation and amortisation (EBITDA) margin of 4-5%, management said. The target follows about Rs 500 crore of first-half execution cited during the call, while management expects some wind-order deliveries to spill into the following financial year.
Know Refex Industries inside out
Results, valuation, peers and who's buying, in one view.
What is Refex's FY27 wind revenue and margin target?
Refex is targeting Rs 1,300-1,400 crore of wind-business revenue for the full FY27 financial year, with EBITDA margin of 4-5%. Management clarified the range after an analyst referred to an earlier Rs 1,800 crore execution expectation. Dinesh Agarwal said Refex had instead indicated business of Rs 1,300-1,400 crore, alongside completing the order book then discussed at about Rs 1,100-1,200 crore.
Management also put the wind-business profit after tax (PAT) margin at 2.5-3%. It said the 4-5% EBITDA margin and 2.5-3% PAT margin applied for the current financial year and the coming financial year until the first half. When asked whether EBITDA margin could reach 5-6%, Agarwal reaffirmed the 4-5% range.
How much wind-order execution will spill into next year?
Refex expects part of its wind orders to spill into the following financial year, although management said a large part would be executed in FY27. In the discussion around the Rs 1,100 crore of additional orders cited by an analyst, Agarwal agreed that the full amount would not be executed entirely in the current year.
Management gave a more specific timing indication while discussing the second half: it expects to complete the majority of wind orders, but said a few would spill into the next year's first quarter. The Rs 1,300-1,400 crore FY27 target therefore does not assume that all orders under discussion will convert to revenue within the year.
The next potential order was still in commercial negotiation at the time of the call. Management said it was in the final stage of price negotiations for a large-volume order and expected closure within 30-45 days, followed by an announcement. It said right-of-way (ROW) and land matters would not sit with Refex because it supplies equipment rather than developing the projects.
What did Refex report for wind energy in September 2026?
Refex reported wind-energy revenue of Rs 201 crore in the quarter ended September 30, 2026, compared with Rs 297 crore in the previous quarter. The Rs 96 crore sequential decline in segment revenue coincided with EBITDA turning positive at Rs 11.32 crore, from a loss of Rs 3 crore in the preceding quarter.
The movement to positive quarterly EBITDA is the reported backdrop to management's 4-5% FY27 wind-margin target, but it does not establish the full-year margin outcome. Wind revenue recognition depends on the pace of equipment execution, and the call's reference to about Rs 500 crore of first-half execution shows that activity was higher across the half than the September-quarter revenue alone.
At the wider company level, Refex reported standalone continuing-operations revenue of Rs 560 crore for the September 2026 quarter, compared with Rs 411 crore a year earlier. Standalone EBITDA rose to Rs 91 crore from Rs 74 crore and PAT increased to Rs 60 crore from Rs 53 crore, but these figures cover more than the wind segment and are not wind-margin measures.
Got a follow-up? Ask IRIS
When does Refex expect wind margins to improve further?
Refex expects indigenous manufacturing to improve wind profitability after the plant becomes operational and its output begins affecting the accounts. Management said the manufacturing plant was in full swing and should be operational within 12-14 months, with the meaningful profitability effect taking another six months after commissioning.
Management described the project as backward integration through an indigenous manufacturing plant. It said the impact on profitability should emerge after about one to one-and-a-half years in the books of account, while also saying localisation would take time. The call did not disclose the plant's capacity, capital expenditure or component localisation level.
Higher margins remain an aspiration rather than a quantified post-manufacturing target. In response to an analyst's comparison with 17-20% margins at other wind-equipment makers, management said those companies had matured in localisation and that matching such economics would take time. Refex did not revise its stated 4-5% EBITDA target for FY27.
How does wind guidance fit Refex's wider outlook?
Refex's wind framework is distinct from its company-wide standalone guidance of 15-18% EBITDA margin and 20-25% revenue growth for the year. The difference reflects the wind segment's equipment-supply model and order-execution cycle, whereas the standalone guidance covers continuing operations more broadly.
Mobility reported quarterly revenue of Rs 36 crore in September 2026, up from Rs 33 crore in the previous quarter, and EBITDA of Rs 1.3 crore versus Rs 0.8 crore. Management said mobility had reached positive EBITDA and targeted PAT-level profitability within one year, a separate timeline from the wind manufacturing plan.
For the coal-ash business, management retained guidance for 20-25% revenue growth despite an analyst citing 53% first-half growth. Management said the prior year's second half was substantially higher than its first half in absolute terms, which was why it maintained the 20-25% range rather than raising guidance.
Conclusion
Refex has set a measurable FY27 framework for wind equipment: Rs 1,300-1,400 crore of revenue, 4-5% EBITDA margin and 2.5-3% PAT margin. September-quarter wind revenue fell sequentially to Rs 201 crore, but EBITDA improved from a Rs 3 crore loss to a Rs 11.32 crore profit, showing a changed quarterly profitability result as execution timing remained relevant.
The next disclosed milestones are the possible closure of the large wind order within 30-45 days and the portion of current orders that moves into the following year's first quarter. Management also plans to bring its indigenous manufacturing plant into operation within 12-14 months, with an additional six months expected before its profitability impact appears.