










Sathlokhar Q2 FY27 revenue doubles as EBITDA margin reaches 14.9%
Key highlights
- Sathlokhar's Q2 FY27 revenue doubled year on year to Rs 297 crore from Rs 138 crore.
- Q2 FY27 operating EBITDA margin rose to 14.9% from 12.6%, an improvement of approximately 232 basis points.
- H1 FY27 revenue reached Rs 509 crore, up 85%, while PAT rose 120% to Rs 51 crore.
- Sathlokhar reported a Rs 1,239 crore confirmed order book as of October 1, 2026, excluding goods and services tax.
powered by IRIS
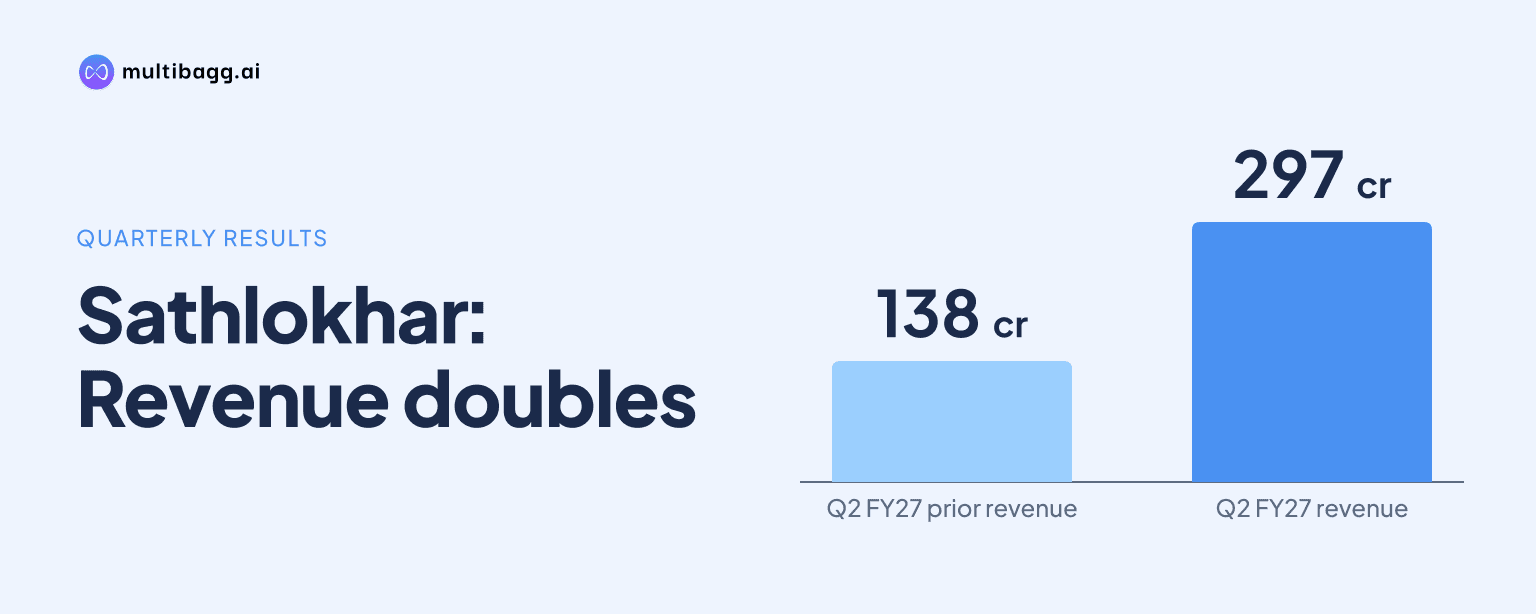
Sathlokhar Synergys E&C Global Limited doubled revenue from operations to Rs 297 crore in Q2 FY27 and reported an operating EBITDA margin of 14.9%, up from 12.6% a year earlier. Operating EBITDA rose 137% to Rs 44 crore despite start-up costs for its new pre-engineered metal building facility.
Know Sathlokhar Synergys E&C Global inside out
Results, valuation, peers and who's buying, in one view.
How did Sathlokhar perform in Q2 FY27?
Sathlokhar reported 100% year-on-year growth in Q2 FY27 revenue, with revenue from operations rising to Rs 297 crore from Rs 138 crore in Q2 FY26. Operating earnings before interest, tax, depreciation and amortisation, or EBITDA, increased 137% to Rs 44 crore. The faster increase in EBITDA than revenue lifted the operating EBITDA margin by approximately 232 basis points to 14.9%.
Profit after tax, or PAT, rose 111% year on year to Rs 29 crore in Q2 FY27, while the PAT margin increased to 9.9% from 9.3% in the corresponding quarter. Management said the margin expansion occurred despite start-up costs for the new pre-engineered building, or PEB, manufacturing facility. The quarter therefore combined a Rs 159 crore increase in revenue with an improvement in reported operating margin.
What does Sathlokhar's first-half performance show?
Sathlokhar delivered Rs 509 crore of revenue from operations in H1 FY27, up 85% from Rs 271 crore in H1 FY26. Operating EBITDA grew 131% year on year to Rs 74 crore, and the EBITDA margin rose by 296 basis points to 14.8%. The H1 margin was 0.1 percentage point below the Q2 FY27 margin of 14.9%.
Sathlokhar's H1 FY27 PAT increased 120% year on year to Rs 51 crore, producing a PAT margin of 10.1%. That margin was 0.2 percentage points above Q2's 9.9%, even as Q2 revenue reached an all-time high of Rs 297 crore. Management linked the results to scaling its project portfolio while stressing execution quality, operating efficiency and working-capital management as the business expands.
What order pipeline supports Sathlokhar's FY27 target?
Sathlokhar retained its FY27 revenue guidance of approximately 70% growth over FY26 revenue, supported by a confirmed order book of about Rs 1,239 crore as of October 1, 2026, excluding goods and services tax. It also reported H1 FY27 order inflow of Rs 624.73 crore including goods and services tax, after winning about Rs 352.68 crore of orders during Q2.
Order momentum continued into October 2026, when Sathlokhar reported intake of about Rs 117.61 crore excluding goods and services tax. Its bid pipeline stood at about Rs 23,505 crore, and management said its historical bid-to-order conversion rate was around 10% to 12%. That pipeline is an opportunity pool rather than booked work because conversion depends on customer decisions, project approvals and commercial viability.
Sathlokhar said typical steel-construction PEB projects take about five to six months, while projects involving mechanical, electrical and plumbing, or MEP, work take seven to nine months depending on scope. Management expects the existing order book to translate progressively into revenue over coming quarters. In the call, it said Rs 738 crore of the stated order book remained to be executed after Rs 501 crore through H1, and it expected another Rs 150 crore of packages within ongoing projects.
Got a follow-up? Ask IRIS
How could the new PEB facility affect margins?
Sathlokhar's new PEB manufacturing facility spans 165,000 square feet and has designed capacity of about 1,200 metric tonnes a month at optimum utilisation. Installation and commissioning of machinery were roughly completed on August 30, 2026. Management expects commercial production to begin in December 2026, subject to receiving statutory approvals.
Management expects the facility to provide about 4,500 tonnes of production capacity during the current financial year as utilisation builds. The initial focus is to meet captive project requirements, with external-customer opportunities under evaluation. Over the next five years, management plans to establish PEB plants across India closer to industrial markets, although it did not specify investment amounts or locations in the call.
Management expects the PEB ramp-up to generate incremental operating-margin improvement of approximately 1% through backward integration, more control over material procurement, reduced reliance on external manufacturing vendors, improved production planning and greater control of project execution. Those benefits remain management expectations and depend on production ramp-up, capacity utilisation and market demand. The facility was funded largely through internal accruals and preferential funds, with limited bank borrowing for equipment and machinery.
What funding needs does Sathlokhar see as it grows?
Sathlokhar said it requires Rs 25 crore to Rs 30 crore of funding support for every Rs 100 crore of revenue, including performance bank guarantees, advance bank guarantees and working capital. Management said the company had working capital for ongoing projects sufficient to pursue its FY27 guidance, but was working with bankers on incremental debt capacity as orders are booked.
For FY28, management said additional funding may be necessary if its bid pipeline converts into orders, particularly to support guarantees and working capital. It said bank debt was the preferred route and that non-convertible debentures, or NCDs, could be considered as an alternative. Management said it had no equity-raising plans at the time of the call. The funding requirement is tied to order conversion rather than a disclosed fixed borrowing target.
Conclusion
Sathlokhar's Q2 FY27 result showed that revenue growth and profitability improved together: revenue reached Rs 297 crore, operating EBITDA margin rose to 14.9%, and PAT reached Rs 29 crore. H1 FY27 extended that pattern, with Rs 509 crore of revenue, Rs 74 crore of operating EBITDA and a 14.8% margin, while the Rs 1,239 crore confirmed order book provides the stated base for execution.
The next items to watch are whether the PEB facility begins commercial production in December 2026 after statutory approvals, how quickly its 1,200-tonne monthly capacity is utilised, and whether order wins support management's approximately 70% FY27 growth guidance. Management is also assessing eligibility and preparatory steps for a proposed move from the SME platform to the main board, subject to regulatory requirements and approvals.