










Shera Energy Limited H1FY27 profit doubles on record sales
Key highlights
- Shera reported H1FY27 consolidated revenue of Rs 1,047.40 crore, up 34.2% year on year.
- H1FY27 PAT rose 102.3% year on year to Rs 30.77 crore from Rs 15.21 crore.
- EBITDA margin expanded 146 basis points to 6.76% in H1FY27.
- Shera’s average monthly order book stood at Rs 200 crore.
powered by IRIS
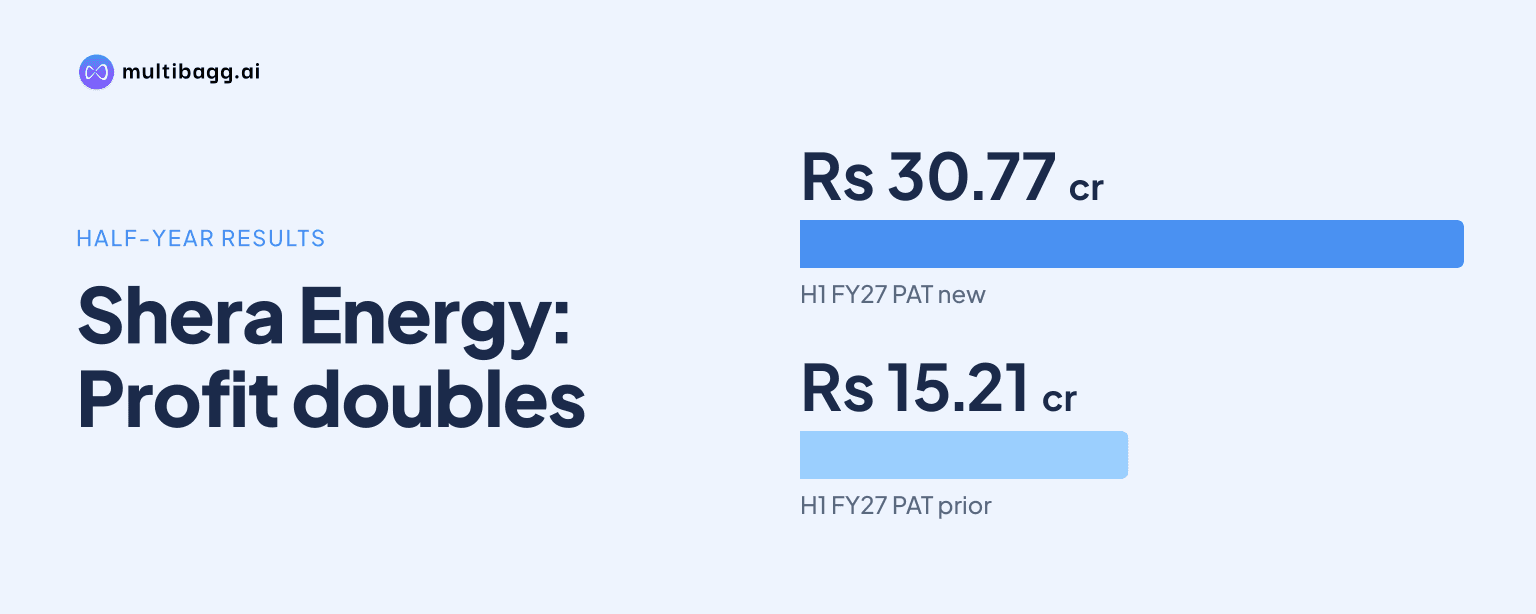
Shera Energy Limited reported H1FY27 consolidated revenue of Rs 1,047.40 crore, its first half-year above Rs 1,000 crore, while profit after tax rose 102.3% year on year to Rs 30.77 crore. EBITDA margin, including other income, increased 146 basis points to 6.76% as revenue grew 34.2% from H1FY26.
Know Shera Energy inside out
Results, valuation, peers and who's buying, in one view.
What were Shera’s H1FY27 financial results?
Shera recorded revenue from operations of Rs 1,047.40 crore in H1FY27, up from Rs 780.65 crore in H1FY26 and above Rs 859.40 crore in H2FY26. The Rs 266.75 crore year-on-year increase represented 34.2% growth, and the presentation described H1FY27 as the Group’s strongest-ever half-year.
Profit before tax increased 98.2% to Rs 41.85 crore in H1FY27 from Rs 21.12 crore a year earlier. Profit after tax, or PAT, rose 102.3% to Rs 30.77 crore from Rs 15.21 crore, while H2FY26 PAT was Rs 21.76 crore.
How did Shera’s margins change in H1FY27?
Shera’s earnings before interest, tax, depreciation and amortisation, or EBITDA, rose 70.9% year on year to Rs 70.78 crore in H1FY27 from Rs 41.40 crore in H1FY26. EBITDA margin increased to 6.76% from 5.30%, a 146-basis-point expansion, with EBITDA and its margin including other income according to the presentation.
PAT margin rose to 2.94% in H1FY27 from 1.95% in H1FY26, an increase of 99 basis points. Both measures also exceeded H2FY26 levels, when EBITDA margin was 6.14% and PAT margin was 2.53%; EBITDA itself rose by Rs 17.97 crore from Rs 52.81 crore in the preceding half-year.
The gap between sales growth and profit growth widened in H1FY27. Revenue increased 34.2%, while EBITDA grew 70.9% and PAT grew 102.3%, producing the higher 6.76% EBITDA margin and 2.94% PAT margin reported for the period.
What drove Shera’s H1FY27 revenue growth?
Shera said sustained customer demand and higher utilisation of existing capacity across key verticals drove its Rs 1,047.40 crore H1FY27 turnover. The chairman cited broad-based demand from transformer and power-equipment manufacturers, while the presentation placed the average monthly order book at Rs 200 crore.
Capacity utilisation had increased to 78% in FY26 from 74% in FY25, a four-percentage-point change before the H1FY27 reporting period. Management said its copper, aluminium and brass product capability, in-house recycling and working-capital management supported volume growth during metal-price volatility, although it did not disclose H1FY27 volume, utilisation or cash-flow figures.
The presentation links the demand backdrop to winding wires and conductors used by power-equipment customers. It does not quantify the revenue contribution of individual metals, customer groups or product verticals within the Rs 1,047.40 crore reported H1FY27 revenue.
Got a follow-up? Ask IRIS
What new production capacity has Shera started?
Shera said Shera Metal Private Limited’s facility for super-fine enamelled wires, photovoltaic ribbon wires and busbars has entered commercial production. Trials for continuously transposed conductors, or CTC conductors, are complete and initial commercial orders have been executed, with full-scale commercial production expected by the end of the year.
Rajputana Industries has commenced commercial production of 2,400 metric tonnes per annum, or MTPA, of nickel-iron alloy capacity and 36,000 kilometres per annum of cable and conductor capacity at Reengus. The presentation does not state how much revenue or profit these additions contributed to H1FY27 revenue of Rs 1,047.40 crore.
These value-added product initiatives sit alongside the 78% FY26 capacity utilisation disclosed by Shera. The source identifies the products and operating status, but provides no separate production volumes, realisations or order-book amounts for enamelled wires, photovoltaic ribbon wires, busbars or CTC conductors.
When will Shera’s Zambia cathode project begin commercial operations?
Shera expects commercial operations at the pilot-stage Zambia copper cathode facility to commence by Q4FY27. Shera Zambia Limited, a 99.50%-owned subsidiary, produced and sold its first trial batch of 8.6 metric tonnes of 99.99% pure copper cathode, while Phase 1 is designed for 1,200 MTPA.
The presentation identifies a proposed scale-up to 5,000 MTPA and describes the project as backward integration into a major raw-material cost. It does not disclose capital expenditure, production cost, revenue contribution or profitability for the Zambia operation during H1FY27.
On 14 July 2026, Shera allotted 45 lakh convertible warrants at Rs 118 each on a preferential basis, totalling Rs 53.10 crore. On 15 July 2026, its credit rating was upgraded to ACUITE A- / Stable for the long term and A2+ for the short term.
Conclusion
Shera’s H1FY27 results show profit growing faster than revenue, with sales rising 34.2% to Rs 1,047.40 crore, EBITDA increasing 70.9% to Rs 70.78 crore and PAT more than doubling to Rs 30.77 crore. The resulting 6.76% EBITDA margin and 2.94% PAT margin were above both H1FY26 and H2FY26 levels, while management attributed the revenue outcome to customer demand and greater use of existing capacity.
The next disclosed operating milestones are commercial operations at the 1,200-MTPA Zambia cathode facility by Q4FY27 and full-scale CTC conductor production by the end of the year. Subsequent disclosures can show whether the Rs 200 crore average monthly order book, newly commissioned product capacities and Rs 53.10 crore warrant allotment translate into reported revenue, margins and operating performance.