










Shradha Realty deploys Rs 120.61 crore with no deviation
Key highlights
- Shradha Realty reported Rs 120.61 crore utilised from its Rs 121.50 crore rights issue by September 30, 2026.
- Rs 75 crore allocated as a debt loan to a wholly owned subsidiary was reported fully utilised.
- The supporting certificate recorded Rs 120.46 crore utilised and Rs 1.03 crore unutilised at September 30, 2026.
- A Rs 1 crore ICICI Bank fixed deposit was stated to mature on November 4, 2026 at a 4.00% return.
powered by IRIS
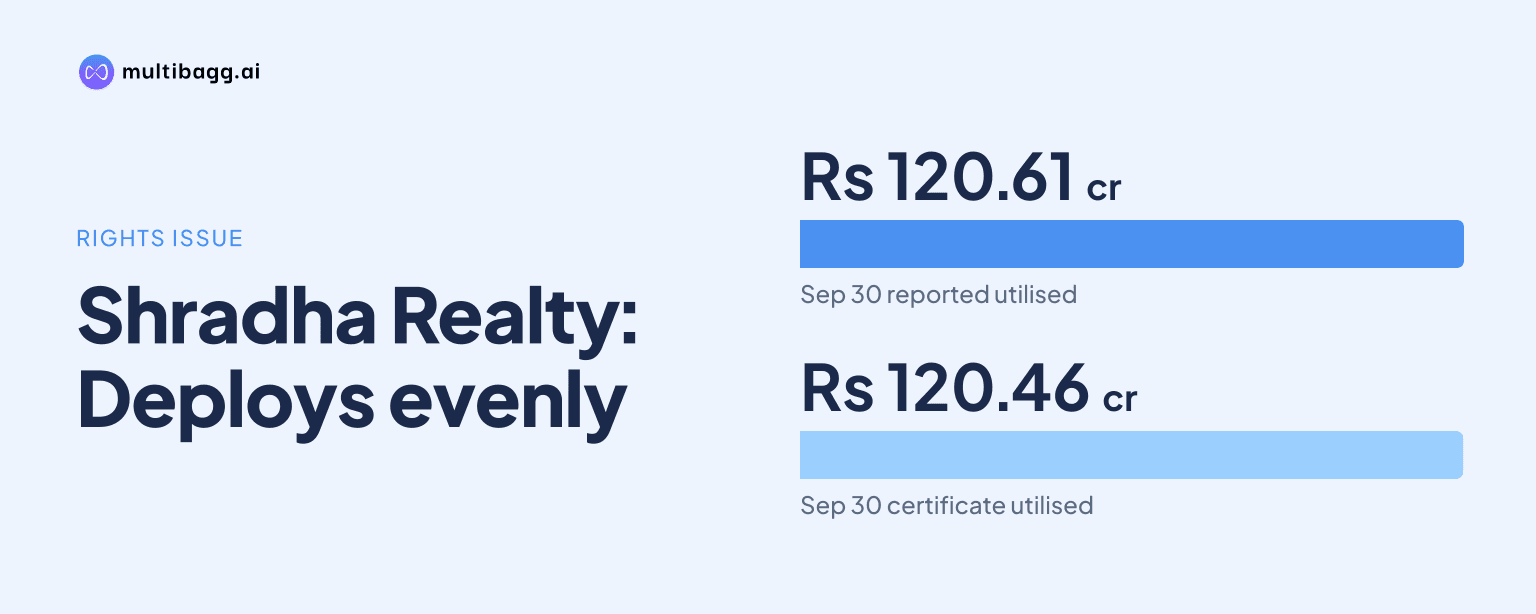
Shradha Realty Limited said it had utilised Rs 120.61 crore of Rs 121.50 crore raised in its October 6, 2025 rights issue by September 30, 2026, and reported no deviation or variation from the stated objects. The largest disclosed use was a fully utilised Rs 75 crore debt loan to a wholly owned subsidiary.
Know Shradha Realty inside out
Results, valuation, peers and who's buying, in one view.
What did Shradha Realty report on rights-issue utilisation?
Shradha Realty reported Rs 120.61 crore of utilisation against Rs 121.50 crore raised in the rights issue as of September 30, 2026. Its Regulation 32(1) statement, filed on November 14, 2026, answered “No” to whether there had been a deviation or variation in the use of funds and showed nil deviation for each stated object.
The filing identified Brickwork Ratings India Pvt. Ltd as the monitoring agency for the Rs 121.50 crore issue. It recorded nil audit committee comments after review, while no shareholder approval was applicable because the statement reported no modified object, allocation or contractual change as of September 30, 2026.
The company’s statement leaves Rs 89 lakh unutilised when its reported Rs 120.61 crore utilisation is deducted from the Rs 121.50 crore amount raised. However, the accompanying certificate from V. K. Surana & Co. reports a different total of Rs 120.46 crore utilised and Rs 1.03 crore unutilised at September 30, 2026.
How were Shradha Realty’s rights-issue proceeds allocated?
Shradha Realty allocated Rs 75 crore to an investment by way of debt loan to its wholly owned subsidiary, Rs 16.50 crore to working-capital requirements, Rs 29.50 crore to general corporate purpose and Rs 50 lakh to issue expenses. The Regulation 32 statement reported no modification to any of these four allocations as of September 30, 2026.
The Rs 75 crore subsidiary loan was fully utilised, according to both the Regulation 32 statement and the accountant’s certificate. This was the largest object, exceeding the Rs 29.50 crore general-corporate-purpose allocation and the Rs 16.50 crore working-capital allocation, while the supplied filing does not name the subsidiary or set out the loan’s interest, maturity or repayment terms.
For working capital, Shradha Realty’s Regulation 32 statement reported Rs 15.62 crore utilised by September 30, 2026. It reported the full Rs 29.50 crore allocated to general corporate purpose as used, and Rs 49 lakh of the Rs 50 lakh issue-expense allocation as used, with nil reported deviation across all four objects.
Why do the two rights-issue utilisation records differ?
Shradha Realty’s Regulation 32 statement and the supporting certificate report different aggregate utilisation totals for September 30, 2026. The statement reports Rs 120.61 crore used, whereas the certificate, which describes gross rights-issue proceeds of Rs 121.50 crore, records Rs 120.46 crore used, a difference of Rs 14.71 lakh between the reported totals.
The largest visible difference is in working capital. The certificate records Rs 13.68 crore utilised by June 30, 2026 and Rs 1.79 crore in the September 2026 quarter, or Rs 15.47 crore in total, compared with Rs 15.62 crore in Shradha Realty’s Regulation 32 statement. The supplied documents do not explain the Rs 14.58 lakh difference in working-capital utilisation.
For general corporate purpose, the certificate records Rs 29.36 crore used by June 30, 2026 and Rs 13.69 lakh during the quarter ended September 30, 2026. The bank-entry details identify the Rs 13.69 lakh quarterly use as general-corporate-purpose funds applied to advance tax, bringing the certificate’s cumulative amount to approximately the Rs 29.50 crore allocation.
The certificate records Rs 48.87 lakh of issue expenses used, including Rs 18.84 lakh claimed in the September 2026 quarter, and Rs 76,369 left for that object. It states that the rights-issue proceeds were used in accordance with the offer document’s stated objects and that no other purpose had been separately approved by the board as of September 30, 2026.
Got a follow-up? Ask IRIS
Where was Shradha Realty’s unutilised money held?
Shradha Realty’s certificate reports Rs 1.03 crore of unutilised proceeds at September 30, 2026, all attributed to the working-capital and issue-expense objects. The certificate showed a Rs 1.03 crore balance for working capital, Rs 76,369 for issue expenses, and nil balances for the Rs 75 crore subsidiary loan and Rs 29.50 crore general-corporate-purpose allocation.
The certificate’s deployment schedule separately identifies Rs 1 crore invested in ICICI Bank fixed deposit number 624210028587, maturing on November 4, 2026, at a stated return of 4.00%. It recorded nil earnings on that fixed deposit at September 30, 2026 and did not state a market value for it.
The same deployment schedule lists Rs 35.17 lakh in an ICICI Bank monitoring account and Rs 76,369 in the ICICI Bank rights-issue allotment account. Those three listed balances total more than the Rs 1.03 crore unutilised-proceeds total in the certificate, and the supplied filing does not provide a reconciliation of that difference.
What happened in the September 2026 quarter?
Shradha Realty’s certificate records Rs 2.12 crore of utilisation during the quarter ended September 30, 2026, after Rs 118.35 crore had been utilised by June 30, 2026. Quarterly deployment comprised Rs 1.79 crore for working capital, Rs 13.69 lakh for general corporate purpose and Rs 18.84 lakh for issue-related expenses.
The Rs 18.84 lakh issue-expense entry reimbursed expenses that had earlier been paid from another company bank account. The certificate says the reimbursement was subsequently made from the issue-proceeds account during the September 2026 quarter, which is why it was claimed as utilisation in that period.
Bank entries show Rs 4.75 crore received from the maturity of two fixed deposits, Rs 3.76 lakh of interest earned on matured deposits and Rs 37,640 deducted as tax deducted at source on that interest. The monitoring account also recorded Rs 3 crore placed into two new fixed deposits and a Rs 15.29 lakh transfer from the rights-issue allotment account, identified as a contra entry.
Conclusion
Shradha Realty reported that its Rs 121.50 crore rights issue was used for the disclosed objects without deviation as of September 30, 2026, led by the Rs 75 crore loan to its wholly owned subsidiary. The supporting certificate supports stated-object compliance, but its Rs 120.46 crore utilisation total differs from the company statement’s Rs 120.61 crore total.
The next disclosed event to monitor is the November 4, 2026 maturity of the Rs 1 crore ICICI Bank fixed deposit identified in the September 30 certificate. A later utilisation statement could also clarify the remaining working-capital and issue-expense balances, as well as reconcile the differing utilisation and unutilised-proceeds figures in the two records.