










Shree OSFM E-Mobility Limited retains Rs 9.08 crore unspent proceeds
Key highlights
- Shree OSFM had Rs 9.08 crore of Rs 39.93 crore issue proceeds unutilised at September 30, 2026.
- Rs 6.01 crore remained for IPO-funded passenger-vehicle purchases against a Rs 12.22 crore allocation.
- Rs 3.07 crore of preferential-issue general corporate-purpose funds remained unutilised.
- The unutilised balance was held in short-term deposits and bank balances, according to the October 31, 2026 certificate.
powered by IRIS
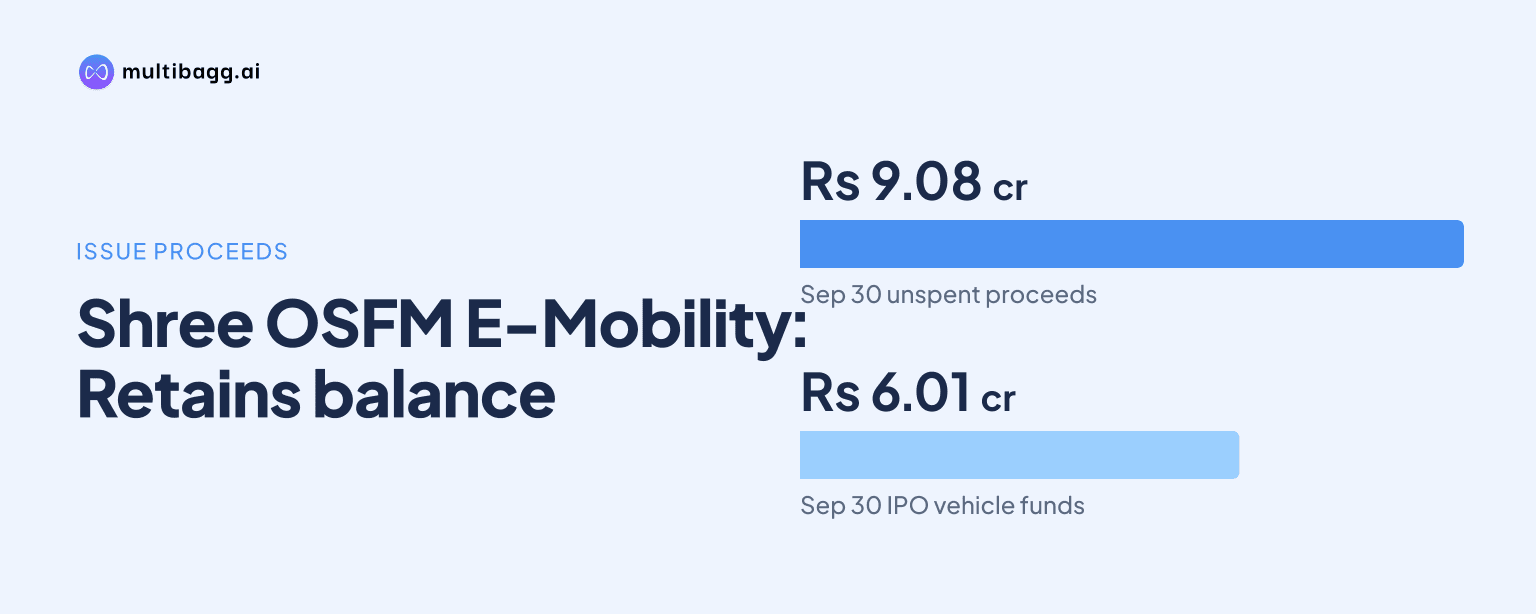
Shree OSFM E-Mobility Limited had Rs 9.08 crore of its Rs 39.93 crore initial public offering, or IPO, and preferential-issue proceeds unutilised as of September 30, 2026. The certified utilisation statement attributes Rs 6.01 crore to passenger-vehicle purchases and Rs 3.07 crore to preferential-issue general corporate purposes.
Know Shree OSFM E-Mobility inside out
Results, valuation, peers and who's buying, in one view.
How much of Shree OSFM's issue proceeds remained unspent?
Shree OSFM had used Rs 30.85 crore of Rs 39.93 crore raised through the IPO and preferential issues, leaving Rs 9.08 crore unutilised at September 30, 2026. The amounts appear in Annexure A to the utilisation certificate dated October 31, 2026, which says the examiner reviewed the company’s books, records and relevant supporting documents.
The unspent balance was concentrated in two objects rather than spread across all five disclosed uses. Passenger-vehicle purchases under the IPO accounted for Rs 6.01 crore, while general corporate purpose under the preferential issue accounted for Rs 3.07 crore. The three other objects, representing Rs 24.65 crore in aggregate, were shown as fully utilised.
Which Shree OSFM uses account for the unspent balance?
Shree OSFM’s largest outstanding allocation was Rs 6.01 crore for the IPO object of purchasing passenger vehicles. Of the Rs 12.22 crore disclosed for that purpose, the certificate records Rs 6.21 crore as actually utilised by September 30, 2026, leaving Rs 6.01 crore to be applied.
The remaining Rs 3.07 crore related to general corporate purpose under the preferential issue. The annexure gives Rs 3.07 crore as both the disclosed allocation and unutilised amount, while the actual-utilised column for this line does not provide a numerical figure. The certificate therefore identifies the full preferential-issue allocation for this purpose as outstanding.
The two pending objects have different stated purposes. The Rs 6.01 crore passenger-vehicle balance is tied to a named asset-purchase use under the IPO, while the Rs 3.07 crore balance is assigned to the broader general corporate purpose category under the preferential issue. The certificate does not provide a timetable for deploying either amount.
How were Shree OSFM's IPO and preferential proceeds allocated?
Shree OSFM allocated Rs 24.60 crore of the Rs 39.93 crore total to IPO objects, based on the annexure’s line items. These comprised Rs 5.11 crore for additional working-capital requirements, Rs 12.22 crore for passenger vehicles and Rs 7.27 crore for general corporate purposes, including apportioned IPO expenses.
The preferential-issue line items total Rs 15.34 crore, consisting of Rs 12.27 crore for additional working-capital requirements and Rs 3.07 crore for general corporate purpose. This differed from the IPO allocation because the preferential issue had no passenger-vehicle object. By September 30, 2026, the Rs 12.27 crore preferential working-capital allocation was reported utilised, while the Rs 3.07 crore corporate-purpose allocation remained unutilised.
The certificate describes the IPO as an issue of 37,84,000 equity shares with a face value of Rs 10 each and a premium of Rs 55 per share. It describes the preferential issue as 11,19,400 equity shares with a face value of Rs 10 and a premium of Rs 127 per share, stating that the preferential issue amounted to Rs 15.33 crore on August 22, 2024.
Got a follow-up? Ask IRIS
Where is Shree OSFM holding the unutilised money?
Shree OSFM held the Rs 9.08 crore unutilised balance in short-term deposits and bank balances, according to the certificate. The statement says these balances were reflected in the financial statements as of September 30, 2026, and does not state that they were redirected to another disclosed object.
The certificate says Shree OSFM had partially applied IPO and preferential-issue proceeds for their disclosed purposes as of that date. Its stated purpose was to verify, using management-provided information, books and other records, whether the funds had been used in line with the purposes specified in the offer document and annexure.
Kale Malde & Co. issued the certificate on October 31, 2026, with Institute of Chartered Accountants of India Unique Document Identification Number 26138034MFJIUZ5411. The document says it was intended solely for submission to the National Stock Exchange of India and does not accept liability or a duty of care for other users or purposes.
What does the Shree OSFM certificate establish about fund use?
Shree OSFM’s certificate establishes that Rs 30.85 crore had been applied and Rs 9.08 crore remained unutilised from the Rs 39.93 crore raised as of September 30, 2026. It also records that the residual funds were held in short-term deposits and bank balances, with passenger vehicles and preferential-issue general corporate purpose identified as the pending uses.
The certificate does not state that the Rs 9.08 crore was spent after September 30, 2026, nor does it disclose a completion date for the passenger-vehicle purchases. It is a special-purpose certificate issued under guidance on reports or certificates for special purposes, with its conclusion limited to the funds and records reviewed through the reporting date.
Conclusion
Shree OSFM had completed deployment of Rs 24.65 crore across IPO working capital, IPO general corporate purposes and preferential-issue working capital by September 30, 2026. The remaining Rs 9.08 crore consisted of Rs 6.01 crore for passenger-vehicle purchases and Rs 3.07 crore for preferential-issue general corporate purpose, distinguishing completed working-capital allocations from the two pending objects.
The next disclosure to watch is a subsequent utilisation statement showing whether Shree OSFM has applied the Rs 6.01 crore vehicle-purchase balance and Rs 3.07 crore corporate-purpose balance. The October 31, 2026 certificate identifies where the money was held at September 30 but discloses no target date or spending schedule for either pending use.