










Shree Pushkar targets Rs 1,800 crore after Unit 6 ramp-up
Key highlights
- Shree Pushkar said Rs 1,250-1,300 crore of FY27 sales can be achieved without Unit 6 revenue.
- Unit 6 may generate no Q4 FY27 revenue while trials, PDIL inspection and NBS-policy inclusion are completed.
- Management asked investors to use about Rs 1,800 crore for 2027-28 rather than its initially cited Rs 2,000 crore figure.
- Q2 FY27 revenue was Rs 403.5 crore, up 58% year on year, while EBITDA rose 88% to Rs 50 crore.
powered by IRIS
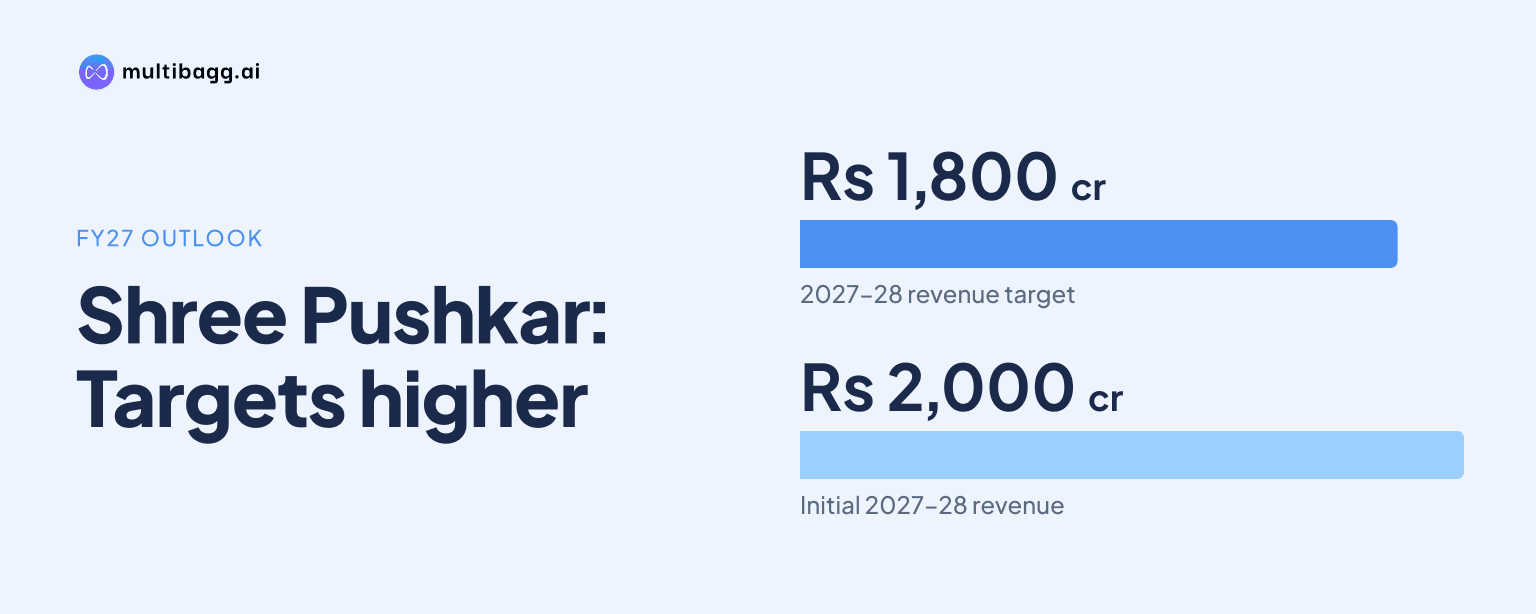
Shree Pushkar Chemicals & Fertilisers Limited said it can achieve Rs 1,250-1,300 crore of FY27 sales without Unit 6, which may produce no revenue in Q4 while trials and approvals are completed. For 2027-28, management asked investors to use about Rs 1,800 crore rather than its initially cited Rs 2,000 crore figure.
Know Shree Pushkar Chemicals & Fertilizers inside out
Results, valuation, peers and who's buying, in one view.
Will Shree Pushkar’s Unit 6 add revenue in FY27?
Shree Pushkar is conservatively assuming that Unit 6 will make no revenue contribution in Q4 FY27, although management said it would try to make some sales. The facility was ready at the time of the Q2 FY27 call, with raw materials being imported for a trial planned by the end of November 2026 or, at the latest, December 2026.
Management said Unit 6 needs three to three-and-a-half months for stabilisation, statutory clearances and other commissioning work before full commercial output. It specifically identified inspection by Projects and Development India Limited (PDIL) and inclusion under the Nutrient Based Subsidy (NBS) policy as steps required for subsidy claims.
The company had earlier included a few months of Unit 6 production in its FY27 outlook, but management now said Rs 1,250-1,300 crore of sales could be achieved without it. Shree Pushkar reported Rs 683 crore of revenue from operations in H1 FY27, leaving Rs 567-617 crore to reach that range during the second half.
Why is Shree Pushkar referring to Rs 1,800 crore for 2027-28?
Shree Pushkar’s Rs 1,800 crore reference for 2027-28 reflects the expected full-year contribution from Unit 6 and other operations, but management did not issue formal guidance. Management initially said sales could be near Rs 2,000 crore, subject to a possible 10% variation, then asked investors to use Rs 1,800 crore instead.
Unit 6 has capacity of 1.5 lakh tonnes, and management said 70% utilisation would mean output of about 1 lakh tonnes. It described the product as carrying a price of Rs 70 per kilogram, which implies roughly Rs 700 crore of sales at those assumptions, although Shree Pushkar did not provide a formal revenue forecast for the plant.
A separate 3,000-tonne chemical project could add to the future revenue base. Management said that project, involving Rs 70 crore of capital expenditure, could generate about Rs 250 crore of sales at 75% utilisation, but declined to identify the product, chemistry or market.
Management distinguished the 3,000-tonne project from an earlier 6,000-tonne Unit 5 investment that cost Rs 37 crore. It said the projects use different products and chemistry, so their capital costs are not directly comparable. Management also described a potential 2.5-to-three-times increase from the current scale after all expansions, but labelled that as personal opinion rather than guidance.
Got a follow-up? Ask IRIS
What supports Shree Pushkar’s FY27 sales plan without Unit 6?
Shree Pushkar’s FY27 plan is supported by Rs 403.5 crore of Q2 revenue from operations, up 58% year on year and 44% sequentially from Rs 280 crore in Q1 FY27. H1 FY27 revenue rose 34% to Rs 683 crore from Rs 509 crore in H1 FY26, before any Unit 6 production.
The chemicals segment led the increase, reporting Q2 FY27 sales of Rs 245 crore, up 85% year on year, compared with fertiliser sales of Rs 158 crore, up 27%. In H1 FY27, chemicals sales rose 53% to Rs 383 crore, while fertiliser sales increased 15% to Rs 300 crore.
Management attributed Q2 growth to both volumes and realisations. It cited a supply shortage of dye intermediates in China linked to environmental and safety compliance, while the Kharif season supported fertiliser volumes. Total Q2 sales volume rose 4.3% year on year to 93,500 metric tonnes, a slower increase than revenue, indicating the contribution of price and mix.
Profitability also improved during Q2 FY27, with earnings before interest, tax, depreciation and amortisation (EBITDA) increasing 88% year on year to Rs 50 crore. EBITDA margin rose to 12.2% from 10% in Q2 FY26, while profit after tax increased 97% to Rs 35 crore.
What could affect Shree Pushkar’s execution in the second half?
Shree Pushkar expects Q3 FY27 fertiliser performance to be somewhat subdued because of poor rains and drought conditions in parts of Maharashtra and Madhya Pradesh. Fertiliser sales volume was 1.45 lakh tonnes in H1 FY27, compared with 1.48 lakh tonnes in H1 FY26, and management said it would seek to outperform the prior year overall.
The timing of the fertiliser subsidy declaration remains an unresolved issue. Management said the central government had not declared the subsidy by the call date, despite expecting it by the end of September 2026, and anticipated an announcement on November 5. Unit 6 also requires NBS-policy inclusion before the company can claim the related subsidy.
Chemical prices aided Q2 results, but management repeatedly described elevated H-Acid and vinyl sulfone prices as temporary. It acknowledged that higher prices had contributed some revenue and profitability but said it could not quantify the impact because Shree Pushkar operates an integrated complex and has existing customer commitments.
Unit 5 has entered commercial production, but management was cautious on its immediate contribution because global demand remained weak. Chemical volume rose from about 9,000 tonnes in Q1 FY27 to about 14,000 tonnes in Q2 FY27, and management said Q3 volume could be somewhat higher than Q2 if the China-related supply conditions continued.
Conclusion
Shree Pushkar’s current message is that FY27 sales of Rs 1,250-1,300 crore do not require Unit 6 revenue, with H1 revenue already at Rs 683 crore and chemicals delivering 53% H1 sales growth. The company’s approximately Rs 1,800 crore reference for 2027-28 depends on Unit 6 ramp-up, its 1.5 lakh-tonne capacity, the new 3,000-tonne chemical project and continued execution in existing segments.
The next milestones are the planned Unit 6 trial update by late November 2026 or December 2026, followed by stabilisation, PDIL inspection and NBS-policy inclusion. Investors will also watch whether Shree Pushkar meets its FY27 sales range as Q3 fertiliser demand faces rainfall pressure and chemical pricing remains subject to changing supply-demand conditions.