










Shubhshree review flags unverified balances and MSME provision
Key highlights
- Shubhshree reported Rs 51.99 crore of trade receivables at September 30, 2026, which the auditor could not independently verify.
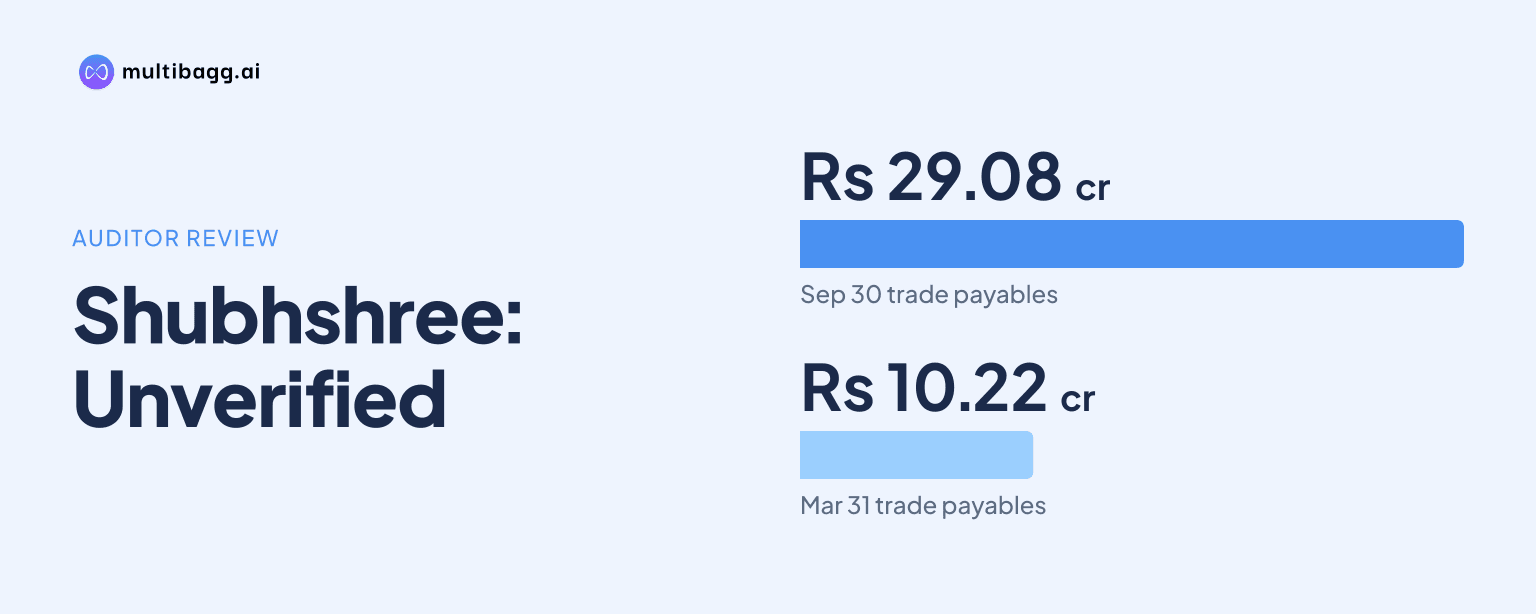
- Shubhshree’s trade payables increased to Rs 29.08 crore at September 30, 2026 from Rs 10.22 crore at March 31, 2026.
- Shubhshree reported Rs 6.35 crore of inventories, but the auditor could not perform physical verification.
- Shubhshree reported half-year profit after tax of Rs 3.42 crore for September 2026, versus Rs 3.00 crore a year earlier.
powered by IRIS
Shubhshree Biofuels Energy Limited received an unmodified limited-review conclusion for the half year ended September 30, 2026, but the reviewer could not independently verify reported trade receivables of Rs 51.99 crore and cited confirmation, inventory, Goods and Services Tax and MSME creditor-classification limitations that prevented a necessary interest provision from being made.
Know Shubhshree Biofuels Energy inside out
Results, valuation, peers and who's buying, in one view.
What did Shubhshree’s auditor conclude on the September 2026 results?
Shubhshree’s auditor, Khandelwal Badaya & Co., concluded on November 14, 2026 that it had not identified matters leading it to believe the unaudited standalone half-yearly results failed to make disclosures required under Regulation 33 of the Securities and Exchange Board of India Listing Obligations and Disclosure Requirements Regulations, 2015. The review covered the half year ended September 30, 2026, and the conclusion was not modified for the matters highlighted.
The conclusion is a limited-review conclusion rather than an audit opinion. The auditor said it performed the engagement under Standard on Review Engagement 2410, which uses inquiries and analytical procedures to provide moderate assurance; it also said a review has substantially less scope than an audit and does not provide assurance that all significant audit matters would be identified. That distinction applies to the four balance-related observations dated November 14, 2026.
Shubhshree’s standalone results for the September 2026 half year reported total income of Rs 130.94 crore and profit after tax of Rs 3.42 crore, compared with Rs 96.37 crore and Rs 3.00 crore respectively in the half year ended September 30, 2025. The auditor did not state that those reported income or profit figures were misstated, but it expressly drew attention to limits on independently verifying specific balance-sheet items.
Which Shubhshree balances could not be independently verified?
Shubhshree’s trade receivables and trade payables were subject to reconciliation and confirmation at September 30, 2026, and the auditor said statements or confirmations from the respective parties were unavailable. It therefore could not independently verify the accuracy and completeness of either balance, while stating that its conclusion was not modified on this account.
The September 30, 2026 balance sheet reported trade receivables of Rs 51.99 crore and trade payables of Rs 29.08 crore. These reported figures indicate the scale of the balances covered by the auditor’s reconciliation and confirmation observation, although the review report does not quantify any potential difference arising from the missing confirmations.
Shubhshree’s inventory observation involved a separate verification mechanism. The auditor said it could not carry out physical verification and was consequently unable to independently verify the quantity and condition of stock held. It relied on inventory records, stock statements and related reports supplied by management for quantitative reporting; inventories stood at Rs 6.35 crore on September 30, 2026.
The auditor also drew attention to Goods and Services Tax, or GST, balances in Shubhshree’s books that remain subject to reconciliation with corresponding GST returns and related records. Neither the review report nor the September 30, 2026 financial statements gave a standalone rupee amount for GST balances or quantified an effect from the pending reconciliation. The conclusion remained unmodified for this matter.
Got a follow-up? Ask IRIS
How did Shubhshree’s working-capital balances change since March 2026?
Shubhshree’s reported trade receivables rose by Rs 14.09 crore, or about 37%, to Rs 51.99 crore on September 30, 2026 from Rs 37.89 crore at March 31, 2026. Inventories increased by Rs 0.84 crore to Rs 6.35 crore over the same period. These movements accompanied an increase in revenue from operations to Rs 130.43 crore in the September 2026 half year, from Rs 96.02 crore a year earlier.
Shubhshree’s trade payables increased by Rs 18.87 crore from Rs 10.22 crore at March 31, 2026, while short-term borrowings rose by Rs 3.25 crore to Rs 15.58 crore. The auditor’s observation is not a finding that these changes are incorrect. It says that confirmations and reconciliations were not available to enable independent verification of the receivable and payable balances reported at the September 30 date.
Other current assets increased to Rs 7.15 crore at September 30, 2026 from Rs 2.43 crore at March 31, 2026, while cash and cash equivalents fell to Rs 0.32 crore from Rs 7.70 crore. The filing does not break out GST within other current assets or link these movements to the auditor’s GST reconciliation observation. No causal conclusion can therefore be drawn from the disclosed figures.
What is the MSME delayed-payment provision issue?
Shubhshree had not made the interest provision required for delayed payments to creditors classified as micro, small and medium enterprises because creditors had not submitted their classification status, according to the auditor’s November 14, 2026 report. MSME means micro, small and medium enterprises, and the applicable law cited in the report is the Micro, Small and Medium Enterprises Development Act, 2006.
The auditor said the omission could have financial and legal implications, including potential non-compliance with the Act, but did not quantify the possible interest charge. Shubhshree’s September 30, 2026 balance sheet reported total trade payables of Rs 29.08 crore, but the report does not identify how much of that amount, if any, relates to creditors that qualify as MSMEs.
The review report does not state that any creditor is definitely an MSME, that a delayed payment occurred, or that a specified interest amount is payable. Its stated issue is the lack of creditor classification information, which prevented Shubhshree from making the necessary interest provision if required. The auditor did not modify its conclusion in relation to this matter.
Conclusion
Shubhshree reported higher half-year total income of Rs 130.94 crore and profit after tax of Rs 3.42 crore for the period ended September 30, 2026, and its limited-review conclusion remained unmodified. At the same time, the auditor placed clear limits on independent verification of Rs 51.99 crore in receivables, Rs 29.08 crore in payables, Rs 6.35 crore in inventories and GST-related book balances.
The unresolved matters to watch are completion of receivable, payable and GST reconciliations, confirmation of creditor MSME status and any resulting delayed-payment interest provision. Shubhshree’s November 14, 2026 filing did not provide a timetable for those reconciliations or quantify a potential MSME-related charge.