










Shyam Metalics projects 44% FY31 EBITDA from three lines
Key highlights
- Stainless steel, SBQ and CRM are projected to contribute 44% of Shyam Metalics’ FY31E EBITDA, up from 8% in FY26.
- Shyam Metalics projects FY31 revenue of approximately Rs 42,500 crore-plus and EBITDA of Rs 6,600 crore-plus, versus Rs 18,552 crore and Rs 2,333 crore in FY26.
- Carbon steel is projected to remain the largest FY31E EBITDA contributor at Rs 2,866 crore, although its EBITDA share is expected to fall to 46% from 73%.
- The Phutamura Coal Block is expected to begin mining and coal production in July 2027, with estimated reserves of about 170 million tonnes and projected FY31E EBITDA of Rs 400 crore.
powered by IRIS
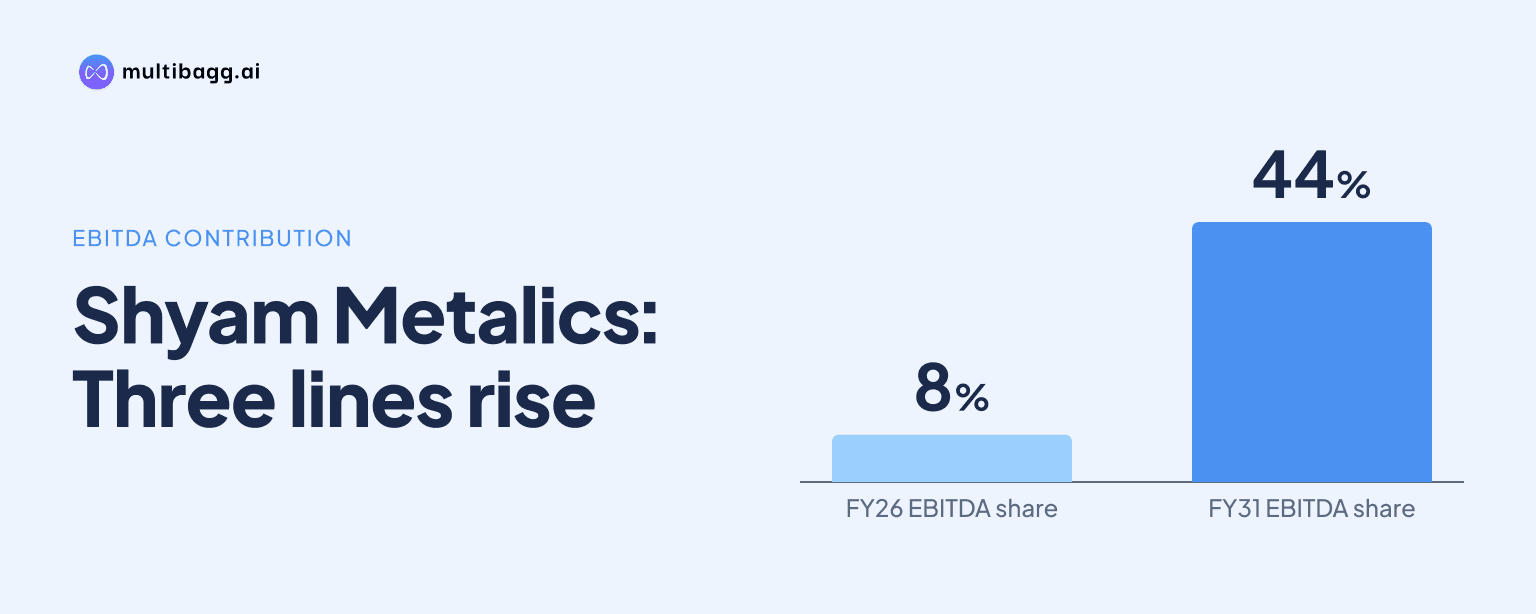
Shyam Metalics projects that stainless steel, special bar quality steel (SBQ) and CRM will account for a combined 44% of FY31 estimated earnings before interest, tax, depreciation and amortisation (EBITDA), compared with 8% in FY26. The proposed mix change underpins management’s approximately Rs 6,600 crore-plus FY31 EBITDA roadmap, versus Rs 2,333 crore in FY26.
Know Shyam Metalics & Energy inside out
Results, valuation, peers and who's buying, in one view.
How will Shyam Metalics change its EBITDA mix by FY31?
Shyam Metalics assigns 44% of FY31E EBITDA share to stainless steel, SBQ and CRM, compared with 8% in FY26. Stainless steel is projected to account for 18% of EBITDA, SBQ for 16% and CRM for 10%, while their FY26 shares were 3%, 0% and 5%, respectively.
The roadmap lists Rs 1,108 crore of FY31E EBITDA from stainless steel, Rs 1,019 crore from SBQ and Rs 645 crore from CRM, a combined Rs 2,772 crore. In FY26, stainless steel contributed Rs 77 crore and CRM Rs 106 crore, while SBQ had nil volume and EBITDA; the comparable combined contribution was Rs 183 crore.
The projected increase is driven by new capacity and product-mix expansion rather than by carbon steel alone. Stainless steel EBITDA is projected to increase by Rs 1,031 crore between FY26 and FY31E, SBQ is projected to add Rs 1,019 crore from a nil base, and CRM EBITDA is projected to rise by Rs 539 crore. Shyam Metalics identifies stainless steel, aluminium foil, CR coils and sheets, SBQ, railway wagons and speciality alloys as high-value portfolio areas.
What revenue and volume growth supports Shyam Metalics’ FY31 plan?
Shyam Metalics projects approximately Rs 42,500 crore-plus of revenue and approximately Rs 6,600 crore-plus of EBITDA in FY31, compared with Rs 18,552 crore and Rs 2,333 crore in FY26. Management presents these targets as revenue compound annual growth of about 18% and EBITDA compound annual growth of about 23%.
Stainless steel has the largest projected revenue increase among the three selected lines. Its volume is projected to rise to 6,99,733 metric tonnes in FY31E from 94,102 metric tonnes in FY26, while revenue is projected to increase to Rs 11,969 crore from Rs 1,322 crore. Its revenue share is consequently projected to rise to 28% from 7%.
SBQ is projected to reach 7,84,000 metric tonnes of volume and Rs 4,704 crore of revenue in FY31E, from nil FY26 volume and revenue. CRM volume is projected to increase to 3,92,000 metric tonnes from 1,65,307 metric tonnes, with revenue rising to Rs 2,976 crore from Rs 1,242 crore. CRM’s revenue share is shown at 7% in both FY26 and FY31E despite the increase in absolute revenue.
The broader volume plan also indicates the scale of the proposed expansion. Shyam Metalics reported 49.46 lakh tonnes of volume in FY26 and projects 61.62 lakh tonnes in FY27P, where P denotes projected. H1 FY27 volume was 29.32 lakh tonnes, compared with 24.39 lakh tonnes in H1 FY26, an increase of 20%; Q2 FY27 volume was 15.49 lakh tonnes, up 26% from 12.26 lakh tonnes in Q2 FY26.
Got a follow-up? Ask IRIS
How does carbon steel change in Shyam Metalics’ FY31 roadmap?
Carbon steel is projected to remain Shyam Metalics’ largest FY31E EBITDA contributor at Rs 2,866 crore, but its EBITDA share is projected to fall to 46% from 73% in FY26. Its revenue share is also projected to decrease to 42% from 70%, showing that the plan relies on faster growth in other product categories.
Carbon-steel revenue is nevertheless projected to rise to Rs 17,933 crore in FY31E from Rs 12,760 crore in FY26, while volume is projected to increase to 52,80,074 metric tonnes from 44,37,734 metric tonnes. Its EBITDA is projected to rise by Rs 1,160 crore, even as the three highlighted lines take a larger stated share of the EBITDA mix.
Specialty alloys move in the opposite direction in the product roadmap. Their FY31E revenue is projected at Rs 947 crore, down from Rs 2,097 crore in FY26, and EBITDA is projected at Rs 143 crore versus Rs 367 crore. Aluminium is projected to increase revenue to Rs 2,331 crore from Rs 821 crore and EBITDA to Rs 277 crore from Rs 76 crore, while retaining a 5% revenue share.
Railway wagons are another FY31E addition, with projected revenue of Rs 1,788 crore and EBITDA of Rs 180 crore. The product table assigns wagons 4% of FY31E revenue and 3% of EBITDA, alongside Shyam Metalics’ stated plan to strengthen its positioning in defence, engineering, railways and real estate.
What funding and execution factors are included in the plan?
Shyam Metalics projects FY31 cash accrual of approximately Rs 5,198 crore, compared with Rs 1,238 crore in FY26. Gross debt is projected to increase to approximately Rs 4,226 crore from Rs 957 crore, while net debt is shown as approximately negative Rs 912 crore in FY31, compared with negative Rs 378 crore in FY26.
Reported capital expenditure was Rs 2,046 crore in FY26 against Rs 2,023 crore of cash flow from operations, equal to 101% of operating cash flow. In H1 FY27, capital expenditure was Rs 1,291 crore and cash flow from operations was Rs 1,544 crore, equal to 84%. Cash and cash equivalents were Rs 1,115 crore in H1 FY27, compared with Rs 1,238 crore in FY26.
Coal is a separate planned contributor to FY31E EBITDA. Shyam Metalics Group secured mining rights for the Phutamura Coal Block through an investment in Alom Solar Private Limited; the block in Raigarh district, Chhattisgarh, has estimated reserves of about 170 million tonnes. The presentation expects mining operations and coal production to commence in July 2027 and assigns coal Rs 400 crore, or 6%, of FY31E EBITDA, with no FY26 revenue or EBITDA shown.
Conclusion
Shyam Metalics’ FY31 roadmap depends on a stated shift in EBITDA composition toward stainless steel, SBQ and CRM, whose combined share is projected to rise from 8% in FY26 to 44% in FY31E. Carbon steel is still projected to generate Rs 2,866 crore of FY31E EBITDA, but its share is set to decline as stainless steel, SBQ, CRM, wagons and coal expand.
The next disclosed milestones are the planned July 2027 start of mining and coal production at Phutamura, alongside delivery of projected product volumes and capital expenditure. Management’s FY31 outcome also depends on reaching approximately Rs 42,500 crore-plus in revenue, Rs 5,198 crore in cash accrual and Rs 6,600 crore-plus in EBITDA.