










Shyam Metalics Q2 profit nearly doubled as margin expanded
Key highlights
- Shyam Metalics’ Q2 FY27 revenue rose 33.4% year on year to Rs 5,960 crore, with sales volume increasing 26% to 15.49 lakh tonnes.
- Q2 FY27 profit after tax nearly doubled, rising 96.2% to Rs 511 crore from Rs 261 crore a year earlier.
- Operating EBITDA increased 52.6% to Rs 823 crore, while operating EBITDA margin expanded 170 basis points to 13.8%.
- Shyam Metalics invested in a 51% stake in the Phuthamara Coal Block, with total capital expenditure of Rs 360 crore and expected incremental EBITDA of approximately Rs 400 crore by FY31.
powered by IRIS
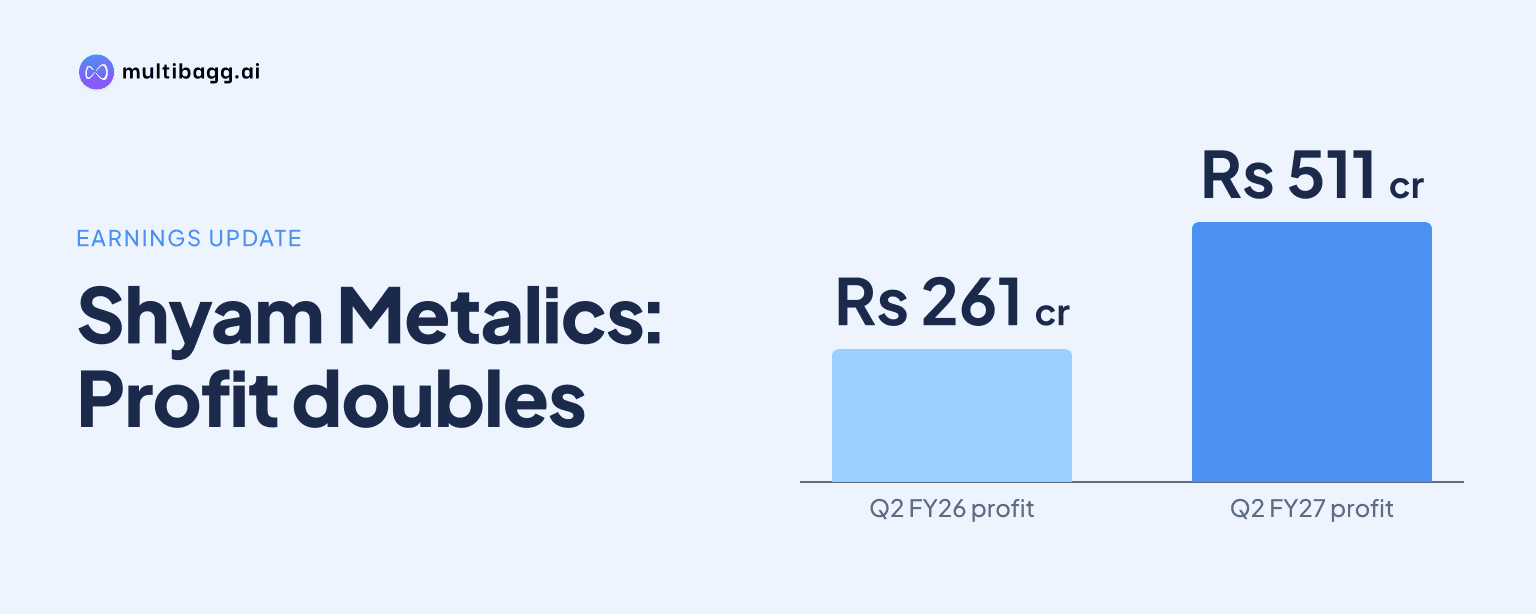
Shyam Metalics and Energy Limited reported a 33.4% year-on-year rise in revenue to Rs 5,960 crore in the second quarter of financial year 2027 (Q2 FY27), ended September 30, 2026. Profit after tax rose 96.2% to Rs 511 crore as operating earnings before interest, tax, depreciation and amortisation margin increased 170 basis points to 13.8%.
Know Shyam Metalics & Energy inside out
Results, valuation, peers and who's buying, in one view.
How did Shyam Metalics perform in Q2 FY27?
Shyam Metalics increased Q2 FY27 revenue to Rs 5,960 crore from Rs 4,467 crore a year earlier, while total sales volume grew 26% to 15.49 lakh tonnes. Revenue also rose 9.3% from Rs 5,455 crore in the first quarter of FY27 (Q1 FY27), showing a higher sales level in the September quarter than in the preceding June quarter.
The company reported earnings before interest, tax, depreciation and amortisation (EBITDA) of Rs 857 crore, up 40.9% from Rs 609 crore in Q2 FY26. EBITDA margin was 14.4%, compared with 13.6% a year earlier, an 80-basis-point increase, although it was 50 basis points below the 14.9% reported in Q1 FY27. A basis point is one-hundredth of a percentage point.
Profit after tax (PAT) reached Rs 511 crore in Q2 FY27, compared with Rs 261 crore in Q2 FY26 and Rs 351 crore in Q1 FY27. The respective 96.2% year-on-year and 45.7% sequential increases were faster than the revenue changes. PAT margin rose to 8.6% from 5.8% a year earlier and 6.4% in Q1 FY27.
Why did Shyam Metalics’ profit rise faster than revenue?
Shyam Metalics’ reported operating EBITDA increased 52.6% to Rs 823 crore, outpacing the 33.4% increase in revenue, and its operating EBITDA margin reached 13.8% from 12.1% in Q2 FY26. The 170-basis-point margin change is the clearest reported measure of greater operating earnings conversion during the quarter.
The company’s total EBITDA increase was lower at 40.9%, to Rs 857 crore from Rs 609 crore, while operating EBITDA rose from Rs 539 crore. This difference means the release presented operating EBITDA separately from total EBITDA, but it did not provide a numerical reconciliation between the two measures in its Q2 FY27 financial highlights.
Management attributed the Q2 FY27 outcome to disciplined execution and its integrated business model. Chairman and Managing Director Brij Bhushan Agarwal said downstream expansion and integration supported flat-product volume growth and higher sequential stainless-steel sales, but the release did not assign specific rupee amounts of the Rs 284 crore operating EBITDA increase to those factors.
A reported accounting change is also relevant when comparing return measures and underlying performance. Effective in Q2 FY27, Shyam Metalics changed depreciation from written-down value to straight-line depreciation, saying the approach aligns with industry practice and supports a stable return profile. The company reported return on equity (RoE) of 14% and return on capital employed (RoCE) of 20%, but did not quantify the effect of the depreciation change on Q2 profit or those ratios.
Got a follow-up? Ask IRIS
What do Shyam Metalics’ first-half results show?
Shyam Metalics generated Rs 11,415 crore of revenue in the first half of FY27 (H1 FY27), up 28.4% from Rs 8,890 crore in H1 FY26, while PAT increased 56.4% to Rs 862 crore. First-half profit therefore grew faster than revenue, consistent with the Q2 FY27 relationship between the two measures.
H1 FY27 EBITDA was Rs 1,670 crore, a 34.4% increase from Rs 1,242 crore, and the EBITDA margin improved 60 basis points to 14.6%. Operating EBITDA rose 41.9% to Rs 1,588 crore from Rs 1,119 crore, lifting its margin by 130 basis points to 13.9% from 12.6%.
The half-year data also show that Q2 FY27 had a higher revenue level than Q1 FY27, at Rs 5,960 crore against Rs 5,455 crore, but a slightly lower total EBITDA margin of 14.4% against 14.9%. In contrast, PAT margin increased to 8.6% in Q2 from 6.4% in Q1, contributing to the Rs 511 crore quarterly PAT despite the lower sequential EBITDA margin.
For the first six months, PAT margin rose to 7.5% from 6.2% in H1 FY26, a 130-basis-point change. That expansion was smaller than the 280-basis-point year-on-year increase in Q2 FY27 PAT margin, indicating that the September quarter represented a larger share of the half-year improvement than the June quarter.
How is Shyam Metalics pursuing coal integration?
Shyam Metalics acquired a 51% controlling stake in Alom Solar Private Limited for the Phuthamara Coal Block in Raigarh, Chhattisgarh. The disclosed total capital expenditure is Rs 360 crore, of which the company expects to contribute approximately Rs 183.6 crore for its 51% share.
Management described the transaction as backward integration intended to secure long-term coal supply for captive power generation and steel manufacturing. The company expects approximately Rs 400 crore of incremental EBITDA by FY31 from the project, which is a management expectation rather than a reported Q2 FY27 financial contribution.
The Q2 FY27 result release places the Rs 360 crore coal-block investment alongside Rs 621 crore of cash accrual reported for the quarter. However, it does not provide a construction schedule, coal production timeline or interim earnings contribution for the Phuthamara Coal Block, leaving the FY31 EBITDA expectation as the stated longer-term reference point.
Conclusion
Shyam Metalics converted a Rs 1,493 crore year-on-year revenue increase in Q2 FY27 into a Rs 250 crore increase in PAT, with operating EBITDA margin expanding to 13.8% from 12.1%. The first-half figures point in the same direction: revenue rose 28.4% to Rs 11,415 crore, while PAT rose 56.4% to Rs 862 crore.
The next disclosed milestone to watch is execution of the Rs 360 crore Phuthamara Coal Block investment and management’s expectation of approximately Rs 400 crore in incremental EBITDA by FY31. Comparisons in subsequent quarters will also need to account for the depreciation-method change adopted in Q2 FY27, for which Shyam Metalics has not disclosed a quantified earnings effect.