










SMC Global Securities Limited trims FY27 NBFC AUM to Rs 1,150 crore
Key highlights
- SMC expects FY27 NBFC AUM of Rs 1,125 crore to Rs 1,150 crore, below its earlier aim of about Rs 1,300 crore.
- NBFC AUM was Rs 1,031 crore at September 2026, compared with Rs 1,119 crore in March 2026.
- Micro-LAP AUM rose to Rs 172 crore from Rs 121 crore in six months, while gold-loan AUM increased to Rs 74 crore from Rs 66 crore.
- H1 FY27 NBFC NIM was 7.8%, compared with 7.3% in FY26.
powered by IRIS
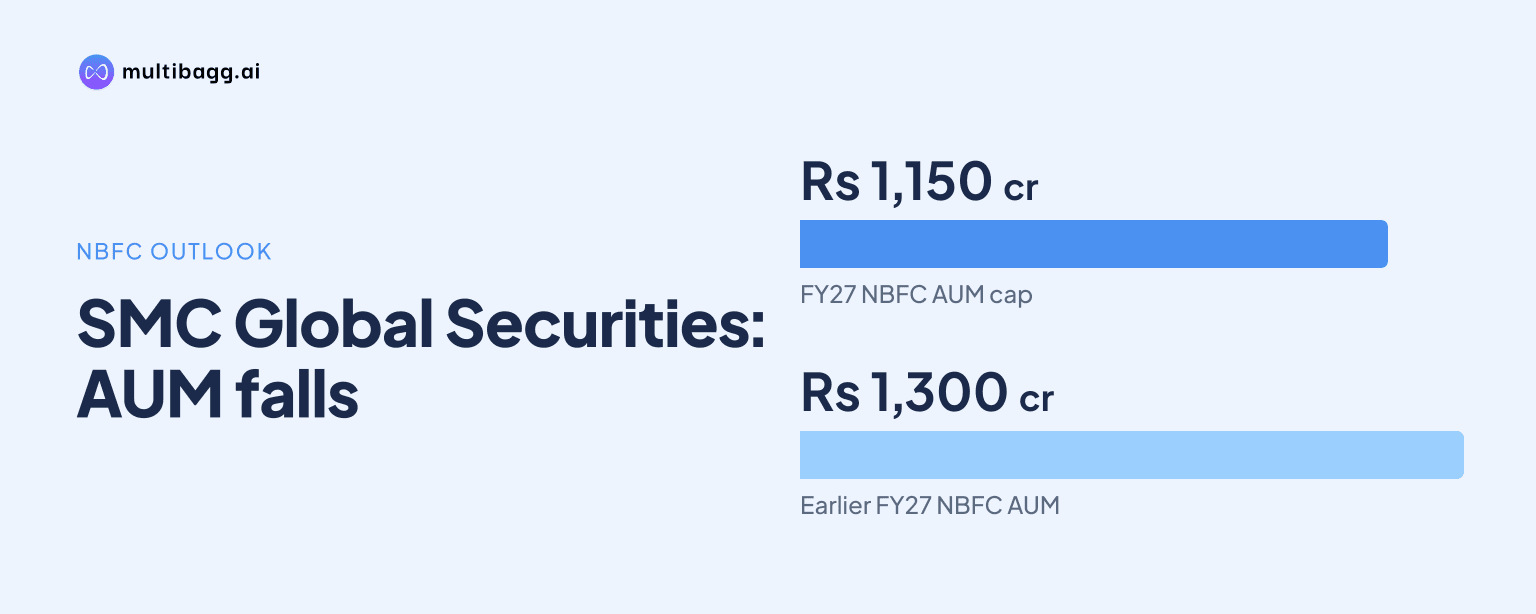
SMC Global Securities Limited expects FY27 non-banking financial company (NBFC) assets under management (AUM) of Rs 1,125 crore to Rs 1,150 crore, versus its earlier roughly Rs 1,300 crore aim, after AUM fell to Rs 1,031 crore at September 2026 from Rs 1,119 crore in March as legacy loans ran off faster.
Know SMC Global Securities inside out
Results, valuation, peers and who's buying, in one view.
Why did SMC lower its FY27 NBFC AUM expectation?
SMC lowered its expectation because the run-off of discontinued large-ticket loan-against-property (LAP) loans and tightened unsecured loans is outpacing additions in its focus products. Management had earlier aimed for about Rs 1,300 crore of NBFC AUM by FY27-end, but now expects Rs 1,125 crore to Rs 1,150 crore as the portfolio transition advances faster than planned.
AUM declined by Rs 88 crore between March 2026 and September 2026, from Rs 1,119 crore to Rs 1,031 crore. Management said discontinued and tightened products ran off by about Rs 253 crore during the last year, while other products grew by Rs 196 crore, leaving a net reduction despite continued lending activity.
SMC reported Rs 323 crore of disbursements in H1 FY27 through 41 branches in seven states, showing that new lending continued while the older book reduced. Management said some run-off that could have occurred in the following year instead happened during FY27, which lowered the closing-book expectation but accelerated the product-mix change.
What lending mix is SMC building?
SMC is building a smaller-ticket secured retail book centred on micro-LAP, gold loans and asset finance while discontinuing large-ticket LAP and tightening unsecured business lending. The stated objective is a more granular portfolio, rather than rebuilding AUM through the legacy products that management is reducing.
Micro-LAP AUM increased to Rs 172 crore at September 2026 from Rs 121 crore in March 2026, a Rs 51 crore increase in six months. Gold-loan AUM rose to Rs 74 crore from Rs 66 crore over the same period, while management identified both products as priority categories alongside asset finance.
SMC also plans to lower unsecured lending from its current level to below 15% of the NBFC book in about a year and then maintain it in a 10% to 15% range. An analyst referred to unsecured small and medium enterprise working-capital term loans as 22.3% of AUM, while management did not provide a separate unsecured-loan amount in its response.
Management said fresh slippages, or newly delinquent loans, have declined following the tightening of unsecured credit. It did not disclose a fresh-slippage ratio, gross non-performing asset ratio or net non-performing asset ratio, so the call did not quantify the change in credit quality alongside the September 2026 AUM figure.
Got a follow-up? Ask IRIS
How is the portfolio transition affecting SMC's margins and profit?
SMC said the transition increased blended lending yield by 25 basis points during the six months to September 2026 and helped lift net interest margin (NIM) to 7.8% in H1 FY27 from 7.3% in FY26. Management attributed the improvement to the growing share of granular retail products and said further mix changes should support yields.
The financing segment recorded Q2 FY27 revenue of Rs 62 crore, up 33.6% year on year, and earnings before interest and tax (EBIT) of Rs 37.6 crore, up 43.0%. In H1 FY27, NBFC revenue rose 11.5% to Rs 108.5 crore, while NBFC profit after tax was Rs 23.3 crore, close to the Rs 24.6 crore reported for all of FY26.
The Reserve Bank of India raised the repo rate by 25 basis points to 5.50% on October 7, 2026, after the September quarter ended. Management said more than 90% of SMC's NBFC borrowings are floating rate and estimated that its borrowing cost could rise by about 20 basis points as facilities reset, based on expected rate transmission of 75% to 80%.
Management expects the repo-rate increase to have an almost negligible effect on NIM because higher yields from the changing loan mix should offset much of the funding-cost rise. The NBFC's capital adequacy ratio was 46.1% at September 2026, while SMC retained Rs 150 crore from a secured non-convertible debenture issue that was allotted on October 13 and listed on October 14.
How does SMC's NBFC strategy fit its wider FY27 performance?
SMC's financing revenue grew faster than consolidated operational income in Q2 FY27, although broking, distribution and trading remained the largest reported segment. Financing revenue rose 33.6% to Rs 62 crore, compared with 20.9% growth in consolidated operational income to Rs 532.5 crore for the September quarter.
Broking, distribution and trading revenue was Rs 288.3 crore in Q2 FY27, up 19.7% year on year, while insurance broking revenue was Rs 193.8 crore, up 19.3%. Financing EBIT of Rs 37.6 crore exceeded insurance-broking EBIT of Rs 4.5 crore, with management attributing the latter figure partly to investment in manpower, technology and reinsurance.
For H1 FY27, SMC reported consolidated operational income of Rs 1,047.5 crore, up 21.1% year on year, and profit after tax of Rs 65 crore, up 27.6%. Its broking client base, including StoxKart, reached 14.2 lakh at September 2026, while mutual-fund AUM was Rs 4,711 crore, about 2% below Rs 4,787 crore in Q1 as broader equity indices fell by more than 5% in the quarter.
The reduced NBFC AUM expectation therefore reflects the timing of the portfolio replacement rather than a withdrawal from lending. Management's position is that lower aggregate AUM in FY27 is consistent with moving sooner toward micro-LAP, gold loans and other secured retail products with higher yields and lower fresh slippages.
Conclusion
SMC is accepting a lower FY27 NBFC closing-book range in exchange for a faster exit from large-ticket LAP and tighter unsecured lending. The shift has reduced total AUM during the transition, but micro-LAP rose by Rs 51 crore in six months, gold loans increased by Rs 8 crore, and H1 FY27 NIM improved by 50 basis points from the FY26 level.
The next disclosed milestones are the Rs 1,125 crore to Rs 1,150 crore FY27-end AUM expectation and management's plan to take unsecured loans below 15% in about a year. Results will also show whether additional retail-product yield offsets the estimated 20-basis-point increase in borrowing costs as floating-rate facilities reset after the October 2026 repo-rate increase.