










STEL Holdings Q2 FY27 Revenue Rises to ₹2,651.20 Crore
Key highlights
- STEL Holdings reported Q2 FY27 consolidated revenue of ₹2,651.20 crore, compared with ₹9.79 crore a year earlier.
- Q2 FY27 profit after tax was ₹19.67 crore, versus a loss of ₹0.13 crore in the year-earlier quarter.
- Half-year FY27 consolidated revenue reached ₹2,660.99 crore and net profit was ₹19.54 crore.
- The Board approved the unaudited September 2026 quarter and half-year results on November 4, 2026.
powered by IRIS
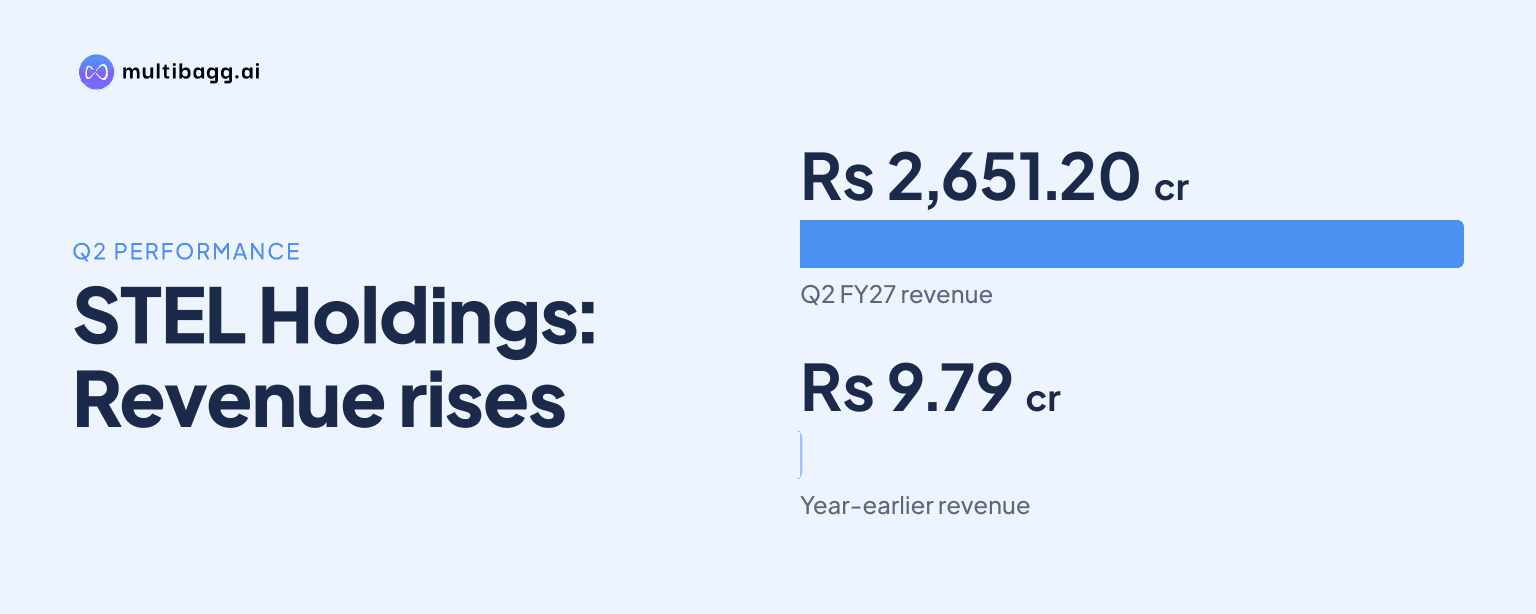
STEL Holdings Limited reported unaudited consolidated revenue of ₹2,651.20 crore for the quarter ended September 30, 2026, compared with ₹9.79 crore a year earlier, while profit after tax was ₹19.67 crore. The results, approved by the Board on November 4, 2026, mark a sharp change from the ₹0.13 crore loss reported in the preceding June quarter.
Know STEL Holdings inside out
Results, valuation, peers and who's buying, in one view.
What did STEL Holdings report for Q2 FY27?
STEL Holdings reported consolidated revenue of ₹2,651.20 crore for the September 2026 quarter, representing a stated year-on-year increase of 26,900% from ₹9.79 crore in the corresponding quarter of the previous year. The company reported net profit of ₹1,966.84 lakh, or ₹19.67 crore, for the quarter, compared with a net loss of ₹13.06 lakh, or ₹0.13 crore, a year earlier.
For the half-year ended September 30, 2026, consolidated revenue was ₹2,660.99 crore, against ₹997.29 crore in the year-earlier half-year. Half-year net profit stood at ₹1,953.78 lakh, or ₹19.54 crore, compared with a loss of ₹12.24 lakh, or ₹0.12 crore, in the comparable period.
The figures point to a substantial concentration of reported income in the September quarter. Revenue for the half-year was only ₹9.79 crore higher than the September-quarter figure, while the half-year profit was marginally below the quarter's profit because the June quarter recorded a loss.
When were the results approved and reviewed?
The Board approved STEL Holdings' unaudited consolidated financial results on November 4, 2026. The company had announced on October 27 that its Board would meet on that date to consider unaudited standalone and consolidated results for the quarter and half-year ended September 30, 2026.
The results were reviewed by auditors under Regulation 33 of the SEBI Listing Obligations and Disclosure Requirements Regulations. Regulation 33 governs the submission and review of periodic financial results by listed companies, including board approval and auditor review requirements for unaudited statements.
The supplied results summary refers to the board approval as relating to “Q3 FY2026”, while the announced agenda and stated reporting period identify the September 30, 2026 quarter and half-year. The September quarter is generally described in the supplied material as Q2 FY27. Investors should rely on the company’s detailed exchange filing for the final period classification and accompanying financial statements.
How did the June quarter compare with the September quarter?
STEL Holdings had reported consolidated revenue from operations of ₹0.10 crore for the quarter ended June 30, 2026. Total income was also ₹0.10 crore, as the company reported no other income contribution for that quarter.
The June-quarter loss before tax was ₹0.12 crore and the loss after tax was ₹0.13 crore. Basic and diluted earnings per share were negative ₹0.07. The company attributed the low operating revenue to timing differences in investment income, which it described as characteristic of a Core Investment Company.
The June-quarter disclosures also showed other comprehensive income of ₹168.26 crore before deferred-tax adjustments. After those adjustments, total comprehensive income was ₹136.88 crore. Other comprehensive income and profit after tax are separate measures, so the comprehensive-income movement does not alter the reported quarterly loss after tax of ₹0.13 crore.
The sharp difference between the June and September revenue figures is therefore central to understanding the half-year numbers. The available material provides the reported figures but does not give a detailed line-item explanation for the September-quarter increase.
Got a follow-up? Ask IRIS
Why do these figures matter for investors?
The September-quarter revenue of ₹2,651.20 crore is far above the company’s recent quarterly revenue levels shown in the supplied historical data. Consolidated sales in the reported quarters from June 2023 through June 2026 ranged from ₹0.10 crore to ₹17.20 crore, with the latter recorded in December 2025.
The reported quarterly profit also reverses the loss recorded in June 2026 and the loss in the year-earlier September quarter. For investors, the result changes the reported scale of revenue and profitability for the first half of FY27, but the supplied information does not provide a breakdown of the source of the September-quarter income.
As a Core Investment Company, STEL Holdings can experience uneven recognition of investment-related income across reporting periods. That makes quarter-to-quarter comparisons sensitive to the timing and nature of income recorded. The June-quarter filing specifically highlighted this timing factor, while the September-quarter summary establishes the reported outcome without setting out the underlying components.
The company’s recent results history also shows irregular revenue patterns. Consolidated sales were ₹17.20 crore in December 2025, ₹0.26 crore in March 2026, and ₹0.10 crore in June 2026. The September-quarter figure should consequently be assessed alongside the detailed financial statements, notes and any management disclosures available in the exchange filing.
What should investors examine in the detailed filing?
Investors should examine the composition of the reported ₹2,651.20 crore revenue, the accounting notes, segment disclosures if any, and the cash-flow information accompanying the unaudited results. These details can help distinguish recurring operating or investment income from income whose recognition is tied to a specific transaction or period.
They should also compare the consolidated and standalone statements because the Board considered both sets of results. The supplied material gives the headline consolidated figures, whereas the underlying statements may provide additional context on expenses, tax, investments, other comprehensive income and the reason for the difference between quarterly and half-year profit.
The auditor review under SEBI LODR Regulation 33 is a relevant procedural disclosure, but it does not replace an assessment of the full notes to accounts. Investors assessing financial performance should use the formally filed statements rather than relying only on percentage growth, especially when the comparison base is small.
Conclusion
STEL Holdings reported a major increase in consolidated revenue to ₹2,651.20 crore for the quarter ended September 30, 2026, and returned to a quarterly profit of ₹19.67 crore. The result contrasts with both the ₹0.10 crore revenue and ₹0.13 crore loss in the June quarter and the ₹9.79 crore revenue recorded in the year-earlier September quarter.
The next point to watch is the detailed exchange filing for clarity on the revenue composition and on the period reference, as the supplied summary contains both a September 2026 Q2 FY27 description and a reference to Q3 FY2026. The company’s standalone and consolidated statements, notes to accounts and auditor-reviewed disclosures will provide the relevant context for evaluating the reported increase.