










Stylam H1 FY27 PAT rose 38% as production margins expanded
Key highlights
- Stylam’s H1 FY27 PAT rose 38% to Rs 91 crore from Rs 66 crore in H1 FY26.
- H1 FY27 contribution margin increased to 48% from 45% despite higher raw-material costs.
- Q2 FY27 other expenses rose to Rs 77 crore from Rs 58 crore in Q1 FY27, led by freight and fuel costs.
- Stylam commenced commercial production at its Manak Tabra laminate plant on September 22, 2026.
powered by IRIS
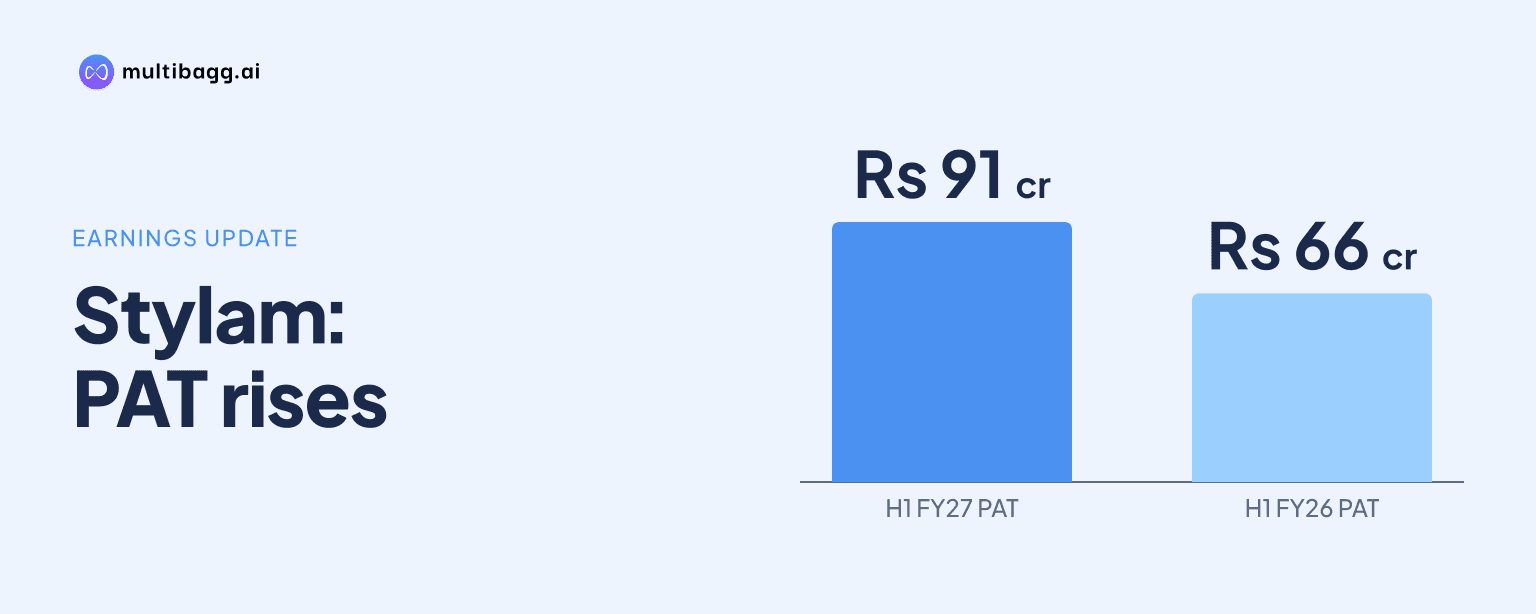
Stylam Industries Ltd. reported profit after tax of Rs 91 crore in H1 FY27, up 38% from Rs 66 crore a year earlier, as its contribution margin increased to 48% from 45% through laminate-production efficiencies despite higher raw-material, ocean-freight and fuel costs during the six-month period.
Know Stylam Industries inside out
Results, valuation, peers and who's buying, in one view.
How did Stylam’s H1 FY27 profit change?
Stylam’s H1 FY27 profit after tax (PAT) rose by Rs 25 crore to Rs 91 crore from Rs 66 crore in H1 FY26, while net revenue increased 16% to Rs 667 crore from Rs 575 crore. PAT margin increased to 14% in the profit-and-loss table, while the financial overview gives the more precise movement as 13.6% from 11.4%, an expansion of 2.2 percentage points.
Earnings before interest, tax, depreciation and amortisation (EBITDA) increased to Rs 132 crore from Rs 111 crore, while the EBITDA margin moved to 20% from 19%. Profit before tax rose to Rs 121 crore from Rs 92 crore, with finance costs falling to Rs 1 crore from Rs 9 crore and other income rising to Rs 5 crore from Rs 2 crore.
What lifted Stylam’s H1 FY27 contribution margin?
Stylam said its H1 FY27 contribution margin improved to 48% from 45% because of efficiencies and increased automation in laminate production, despite an increase in raw-material prices. Contribution rose by Rs 56 crore to Rs 317 crore, compared with a Rs 36 crore increase in material consumption to Rs 350 crore and a Rs 92 crore rise in revenue.
Laminate sheets sold increased to 6.96 million in H1 FY27 from 5.83 million in H1 FY26. Over the past two years, Stylam said its laminates division reached about 90% capacity utilisation after modular expansions at existing facilities, although the presentation does not quantify how much of the H1 margin change came from volume growth or capacity use.
Stylam also reported a higher share of value-added products and an improved product mix over the past two years, without disclosing separate sales or margins for those products. The company specifically attributed the H1 contribution-margin improvement to operational efficiencies and automation rather than to the product mix alone.
Got a follow-up? Ask IRIS
Why did Stylam’s Q2 FY27 profit fall sequentially?
Stylam’s Q2 FY27 PAT was Rs 42 crore, below Rs 48 crore in Q1 FY27, although net revenue increased to Rs 341 crore from Rs 326 crore and contribution rose to Rs 163 crore from Rs 154 crore. The company attributed the sequential PAT decline to higher other expenses, principally ocean freight and fuel prices affected by global factors.
Other expenses increased by Rs 19 crore to Rs 77 crore in Q2 FY27 from Rs 58 crore in Q1 FY27. Stylam said other expenses as a percentage of sales rose by 5 percentage points quarter on quarter, while contribution margin improved by 0.6 percentage points, from 47.2% to 47.6%; operating profit nevertheless fell to Rs 57 crore from Rs 69 crore.
The comparison with Q2 FY26 shows that the latest quarter remained higher in absolute earnings and sales. Net revenue rose to Rs 341 crore from Rs 292 crore, contribution increased to Rs 163 crore from Rs 135 crore and PAT reached Rs 42 crore versus Rs 37 crore, but EBITDA margin was 18%, compared with 21% in Q1 FY27 and 20% in Q2 FY26.
What did Stylam’s Q2 FY27 sales and production data show?
Stylam sold 3.58 million laminate sheets in Q2 FY27, compared with 3.39 million in Q1 FY27 and 3.09 million in Q2 FY26. Export volume increased to 2.57 million sheets from 2.06 million in Q1 FY27, while domestic volume declined to 1.01 million from 1.33 million.
The revenue mix also moved toward exports in Q2 FY27. Export sales were Rs 272 crore, up from Rs 214 crore in Q2 FY26, while domestic sales were Rs 69 crore, down from Rs 79 crore; together, those figures equal the Rs 341 crore of Q2 net revenue reported in the profit-and-loss table.
Stylam commenced commercial production at its new laminate manufacturing plant adjacent to its existing Manak Tabra facility in Panchkula, Haryana, on September 22, 2026. The company said the plant was established as part of its manufacturing-capacity expansion and that it was confident of achieving its financial guidance, but the presentation gives no numerical guidance range, plant capacity or expected financial contribution.
Conclusion
Stylam’s H1 FY27 results show that higher revenue and a 3-percentage-point contribution-margin increase outweighed increased material and logistics costs over the six months. Net revenue reached Rs 667 crore, EBITDA reached Rs 132 crore and PAT reached Rs 91 crore, compared with Rs 575 crore, Rs 111 crore and Rs 66 crore respectively in H1 FY26.
The next disclosed matter to watch is the ramp-up of the Manak Tabra laminate plant, which began commercial production on September 22, 2026, alongside management’s stated aim of meeting financial guidance. Subsequent results will also indicate whether ocean-freight and fuel costs, which lifted Q2 FY27 other expenses to Rs 77 crore, continue to constrain quarterly profitability.