










Sudarshan pigment EBITDA margin reaches 9.4% in H1 FY27
Key highlights
- Sudarshan Pigment Global business EBITDA increased 106.5% to Rs 499 crore in H1 FY27.
- Sudarshan Pigment Global business EBITDA margin rose to 9.4% from 5.1% in H1 FY26.
- Sudarshan’s Acquired Group business EBITDA margin increased to 6.1% from 2.0% in H1 FY27.
- Sudarshan expects the CHF 7 million aluminium-dyes facility acquisition to close in January 2027.
powered by IRIS
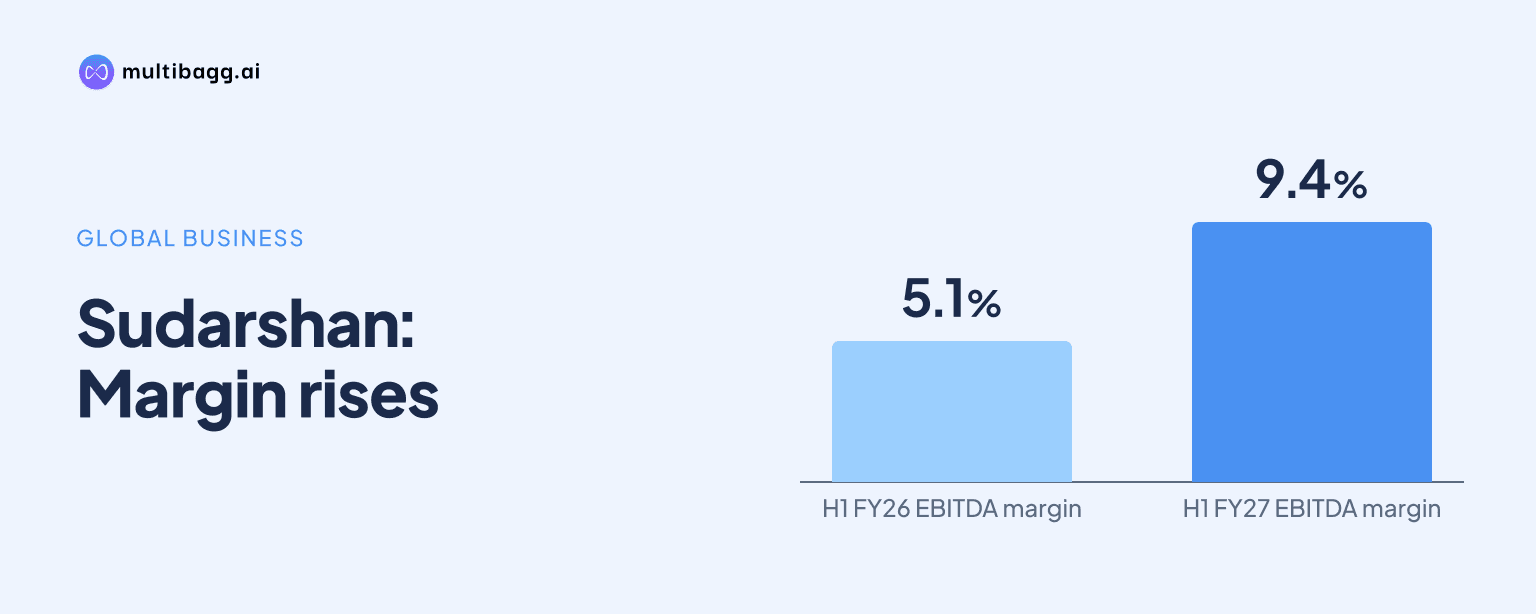
Sudarshan lifted Pigment Global business EBITDA margin to 9.4% in H1 FY27 from 5.1% in H1 FY26, as business EBITDA rose 106.5% to Rs 499 crore despite soft demand in most end markets during Q2 FY27. The Acquired Group accounted for Rs 170 crore of the Rs 257 crore increase in underlying pigment EBITDA.
Know Sudarshan Chemical Industries inside out
Results, valuation, peers and who's buying, in one view.
How much did Sudarshan’s pigment margin improve in H1 FY27?
Sudarshan’s Pigment Global business EBITDA margin increased by 4.3 percentage points to 9.4% in H1 FY27 from 5.1% in H1 FY26. Business EBITDA, or earnings before interest, tax, depreciation and amortisation from actual sales excluding inventory-change effects, increased to Rs 499 crore from Rs 242 crore, while revenue from operations rose 10.8% to Rs 5,300 crore from Rs 4,784 crore.
The 9.4% margin was about 1.8 times the prior-year 5.1% margin, rather than more than twice as high. However, business EBITDA itself more than doubled, increasing 106.5%, while reported EBITDA rose 96.1% to Rs 539 crore from Rs 275 crore. The difference reflects inventory-related effects that Sudarshan excludes from business EBITDA.
What changed in Sudarshan’s legacy and acquired pigment businesses?
Sudarshan’s Acquired Group delivered the larger absolute increase in H1 FY27 business EBITDA, which rose to Rs 240 crore from Rs 70 crore in H1 FY26. Its business EBITDA margin increased to 6.1% from 2.0%, while revenue grew 10.4% to Rs 3,935 crore from Rs 3,565 crore. The Acquired Group therefore supplied about two-thirds of Pigment Global’s Rs 257 crore year-on-year business EBITDA increase.
Sudarshan’s legacy pigment business remained the higher-margin operation, with H1 FY27 business EBITDA margin of 16.5% against 6.1% for the Acquired Group. Legacy pigment business EBITDA rose 48.7% to Rs 255 crore from Rs 172 crore, on revenue growth of 26.2% to Rs 1,551 crore. That revenue growth exceeded the Acquired Group’s 10.4% rate, although the Acquired Group remained the larger business by revenue.
The presentation reports sales between the legacy pigment business and Acquired Group at gross level, but eliminates inter-group sales in Pigment Global consolidated revenue. As a result, the two segment revenue figures should not be added to recreate the Rs 5,300 crore consolidated total. Sudarshan presents the two units separately but does not quantify integration savings or assign the H1 margin expansion to a particular integration measure.
Why does Sudarshan report business EBITDA alongside reported EBITDA?
Sudarshan defines business EBITDA as operating profit from actual sales without the impact of changes in finished-goods and work-in-progress inventory. Reported EBITDA includes the effect of inventory changes. This distinction matters in Q2 FY27, when the Acquired Group reported EBITDA of Rs 134 crore but business EBITDA of Rs 112 crore.
The Rs 22 crore difference in the Acquired Group’s Q2 FY27 figures was an inventorised-overhead credit from an increase in stock. For H1 FY27, Sudarshan said legacy pigment EBITDA included Rs 16 crore of inventorised overheads associated with higher stock. Excluding that item, management presented normalised legacy pigment EBITDA of Rs 239 crore, or a 15.4% margin, and normalised Pigment Global EBITDA of Rs 483 crore, or 9.1%.
Reported EBITDA also excludes specified foreign-exchange translation items related to redeemable preference shares. Sudarshan excluded a Rs 43 crore foreign-exchange gain in H1 FY26 and a Rs 1 crore foreign-exchange loss in H1 FY27 from the reported EBITDA figures. The business EBITDA measure is therefore the presentation’s stated comparison of profit from actual sales before inventory movements.
Got a follow-up? Ask IRIS
How did Q2 FY27 compare with the H1 pigment trend?
Sudarshan’s Pigment Global business EBITDA margin was 9.0% in Q2 FY27, below 9.8% in Q1 FY27 but above 3.9% in Q2 FY26. Q2 business EBITDA was Rs 242 crore on revenue of Rs 2,695 crore, compared with Rs 257 crore on revenue of Rs 2,605 crore in Q1 FY27. Revenue increased sequentially, but the business EBITDA margin declined by 0.8 percentage points.
The Acquired Group’s Q2 FY27 business EBITDA was Rs 112 crore, down from Rs 128 crore in Q1 FY27, and its margin declined to 5.7% from 6.5%. It remained above Q2 FY26, when business EBITDA was Rs 5 crore and the margin was 0.3%, while Q2 FY27 revenue grew 16.5% year on year to Rs 1,962 crore.
Legacy pigment business EBITDA margin was 15.6% in Q2 FY27, compared with 17.4% in Q1 FY27 and 13.0% in Q2 FY26. Sudarshan said Q2 FY27 legacy EBITDA included Rs 3 crore of inventorised overheads from higher stock. On its normalised basis, legacy pigment EBITDA was Rs 125 crore at a 15.4% margin, while Pigment Global EBITDA was Rs 239 crore at an 8.9% margin.
What market conditions could affect Sudarshan’s next pigment results?
Sudarshan said demand in most end markets stayed soft in Q2 FY27, citing weak US housing and European construction and volatile masterbatch demand as buyers managed cost volatility. Management also said raw-material costs remained high while demand was moderate, creating near-term pressure on pigment volumes and margins. These conditions coincided with the Q2 Pigment Global margin easing to 9.0% from 9.8% in Q1 FY27.
Management identified more positive indicators, including European manufacturing moving into expansion with a purchasing managers’ index of about 52 and certain raw-material prices declining from their Q2 FY27 peak. It nevertheless said it expected signs of demand uptake only towards Q4, rather than immediately. The presentation does not provide a margin target for Q4 or quantify the possible effect of lower raw-material prices.
Sudarshan also disclosed two transactions outside the H1 pigment result that establish future milestones. It expects the CHF 7 million acquisition of Clariant’s Muttenz manufacturing facility for aluminium dyes to close in January 2027. Separately, Sudarshan completed the sale of VP4 Frankfurt GmbH on 2 November 2026 for EUR 75.8 million and said proceeds would be primarily used to prepay acquisition debt.
Conclusion
Sudarshan’s H1 FY27 pigment performance shows that underlying profitability increased faster than revenue: business EBITDA rose 106.5% to Rs 499 crore on 10.8% revenue growth, lifting the margin by 4.3 percentage points to 9.4%. The Acquired Group generated Rs 170 crore of the Rs 257 crore increase in business EBITDA, while the legacy pigment business retained the higher 16.5% margin.
The next results will test whether the Q2 FY27 margin of 9.0% can hold while management expects demand improvement only towards Q4 and reports continued raw-material cost pressure. Investors can also watch the planned January 2027 closing of the CHF 7 million aluminium-dyes facility acquisition and the application of EUR 75.8 million VP4-sale proceeds toward acquisition-debt prepayment.