










Sudarshan retains outlook despite returning pigment business
Key highlights
- Sudarshan retained FY27 acquired-group guidance of €700 million revenue and €35 million EBITDA.
- The acquired group’s H1 FY27 business EBITDA rose to Rs 240 crore from Rs 70 crore, while its margin increased to 6.1% from 2.0%.
- Sudarshan said some lost pigment business has returned, with coatings and digital inks driving current demand.
- Sudarshan closed the €75.8 million VP4 sale on November 2, 2026, and plans to use the proceeds to reduce debt.
powered by IRIS
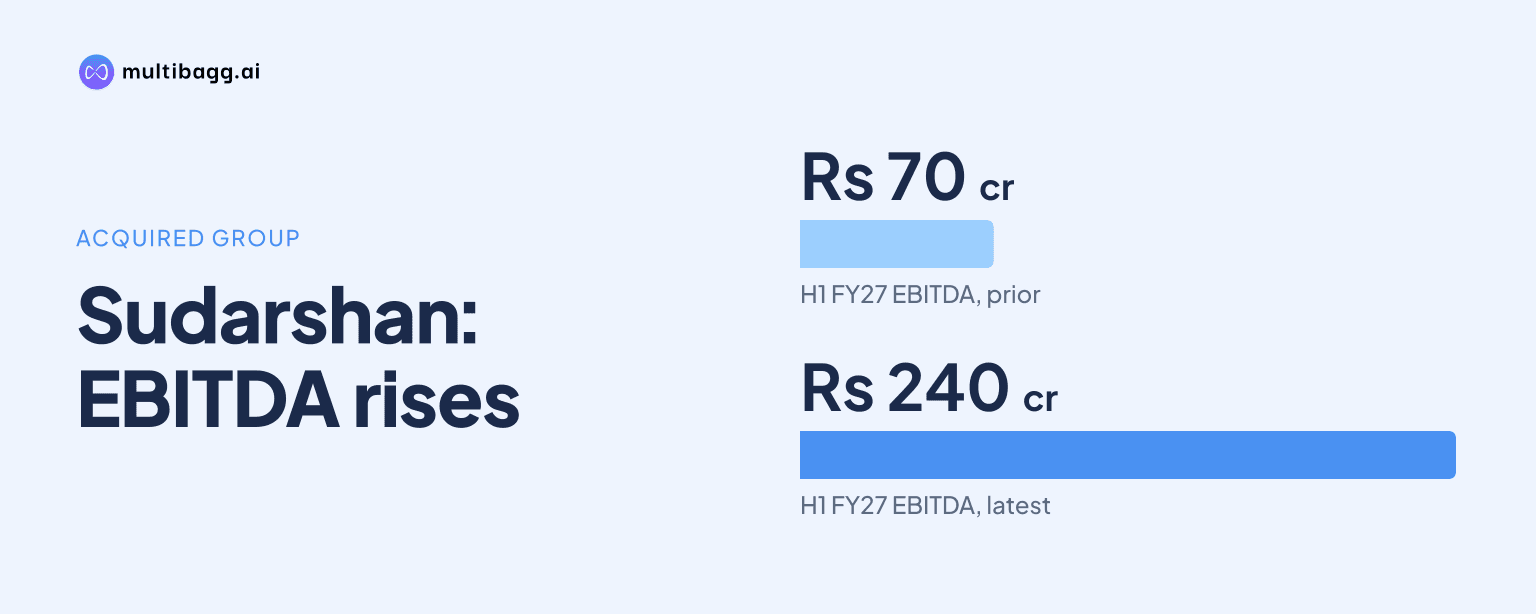
Sudarshan Chemical Industries Limited retained FY27 acquired-group guidance of €700 million revenue and €35 million EBITDA even as some lost pigment business returned, because management still sees weak US housing, European construction and volatile masterbatch demand. The acquired group’s H1 FY27 business EBITDA rose to Rs 240 crore from Rs 70 crore a year earlier.
Know Sudarshan Chemical Industries inside out
Results, valuation, peers and who's buying, in one view.
Why is Sudarshan keeping acquired-group guidance unchanged?
Sudarshan is keeping its €700 million revenue and €35 million earnings before interest, tax, depreciation and amortisation (EBITDA) guidance unchanged because management remains cautious about the market environment in FY27. It cited geopolitical uncertainty, raw-material and logistics-cost increases, weak US housing and European construction, and volatile masterbatch demand linked to oil and polymer-price movements.
Management said it expects signs of demand uptake towards Q4 FY27, rather than immediately. It noted that the European manufacturing index had improved and some raw-material prices had stabilised, but did not treat those indicators as sufficient grounds to raise the acquired-group target.
The retained outlook also includes the effect of the VP4 divestment, according to management. Rajesh Rathi said Q3 of the prior year had been particularly subdued and Sudarshan does not expect the same outcome in Q3 FY27, but described the next two or three quarters as the first normal quarters following the acquisition.
How did Sudarshan’s acquired group perform in H1 FY27?
Sudarshan’s acquired group reported H1 FY27 revenue of Rs 3,935 crore and business EBITDA of Rs 240 crore, compared with Rs 3,565 crore and Rs 70 crore in the prior-year first half. Its business EBITDA margin increased to 6.1% from 2.0%, while management nevertheless retained the €35 million full-year EBITDA target.
In Q2 FY27, the acquired group generated Rs 1,962 crore of revenue and Rs 112 crore of business EBITDA. Reported EBITDA was Rs 134 crore because an Rs 22 crore inventory-overhead effect resulted from increased stock, making the reported measure higher than business EBITDA for the quarter.
The total global pigment business generated Q2 FY27 revenue of Rs 2,695 crore and business EBITDA of Rs 242 crore, versus Rs 2,327 crore and Rs 90 crore in Q2 of the prior year. Legacy Sudarshan pigment revenue was Rs 821 crore and EBITDA was Rs 128 crore in Q2 FY27, producing a stated 15.6% EBITDA margin, compared with the acquired group’s 6.1% H1 margin.
Is Sudarshan already winning back lost pigment business?
Sudarshan said some lost pigment business is already returning, although management said full recovery will take time. It said several global key-account businesses were coming back after Sudarshan rebuilt customer trust, but it did not quantify the recovered revenue, regained market share or expected date for restoring all lost volumes.
The recovery work has focused on global customers whose key contacts are mainly in Europe and the US, although their demand is global. Management said lost business was spread across industries rather than concentrated among one or two suppliers, and identified coatings and digital inks as the principal areas generating returning demand.
Management separated this customer-specific recovery from broader market volume trends in Q2 FY27. For Legacy Sudarshan, it said that after excluding SAP-related timing, growth was approximately split equally between price and volume; some sales that might normally have fallen in October were booked in September before the first-week-of-October SAP go-live.
For the acquired group, management described volume growth as muted, with the balance of revenue improvement coming from price increases. This distinction explains why the return of certain customer accounts has not changed the company’s assessment of external end-market demand or its €700 million acquired-group revenue guidance.
Got a follow-up? Ask IRIS
What is Sudarshan doing to restore customer relationships?
Sudarshan is using innovation and technical customer engagement rather than presenting low prices as its principal route to regain business. Management cited launches and development work in cosmetics, cell-phone applications, digital inks, recycled plastics and heavy-metal-free dyes as evidence that its innovation pipeline has restarted.
The company said cost reduction is intended mainly to improve its own performance, not to position Sudarshan as a cheap supplier. Management said the acquired business carried high fixed costs, and that reducing those costs should support performance alongside innovation-led customer engagement in coatings and digital inks.
Sudarshan recorded an Rs 74 crore employee restructuring expense in Germany, mainly involving support functions rather than direct manufacturing, according to management. It said annual savings should be similar to or slightly higher than the charge, but would emerge gradually over the next 1.5 years as employees leave under an agreement running to the end of the financial year.
Systems integration is another stated part of the recovery plan. Sudarshan is combining four SAP systems and 130 applications into one platform; wave one, covering the Sudarshan legacy and Heubach India legacy, has gone live, while management expects the broader SAP integration to finish by mid-next year.
How does the VP4 sale affect Sudarshan’s financial position?
Sudarshan said the VP4 sale is already incorporated in the unchanged acquired-group guidance. The company closed the transaction on November 2, 2026, for €75.8 million, received the funds, and said it intends to use the proceeds to reduce debt.
Management said the raw material sold through VP4 had captive use of between 5% and 10%, depending on demand, and characterised that use as low and in single digits. The divestment therefore removes an asset that had limited internal consumption while management continues to assess its effect within the existing €35 million EBITDA outlook.
Net debt was Rs 580 crore at September-end, before the November 2, 2026 receipt of VP4 proceeds. The company also reported net debt to equity of 0.2, return on capital employed of 22.6%, and net working capital of 25.3%, while management said improving working-capital efficiency remains a focus for coming quarters.
Conclusion
Sudarshan’s H1 FY27 results show that acquired-group profitability improved, with business EBITDA rising to Rs 240 crore from Rs 70 crore, while some lost customer business has begun to return. Management’s decision to retain €700 million revenue and €35 million EBITDA guidance indicates that it does not equate those customer gains with a broad-based recovery in housing, construction and masterbatch demand.
The next disclosures to watch are whether the expected Q4 FY27 demand uptake produces higher acquired-group volumes, and whether returning coatings and digital-inks business becomes measurable in revenue. Management also expects SAP integration by mid-next year and German restructuring savings to build over the next 1.5 years, while the €75.8 million VP4 proceeds should affect debt after the September-end Rs 580 crore net-debt position.