










Sunrakshakk Q2 PAT rises 130% to Rs 16 crore as revenue grows
Key highlights
- Sunrakshakk reported Q2 FY27 revenue of Rs 265.17 crore, up 119.20% year on year.
- Sunrakshakk’s Q2 FY27 PAT reached Rs 16 crore, up 130.10% from Rs 6.95 crore.
- Sunrakshakk’s Q2 FY27 EBITDA margin was 8.73%, down 92 basis points year on year but up 55 basis points sequentially.
- Sunrakshakk reported installed FMCG and FMCG-intermediates capacity of 20,840 tons per month.
powered by IRIS
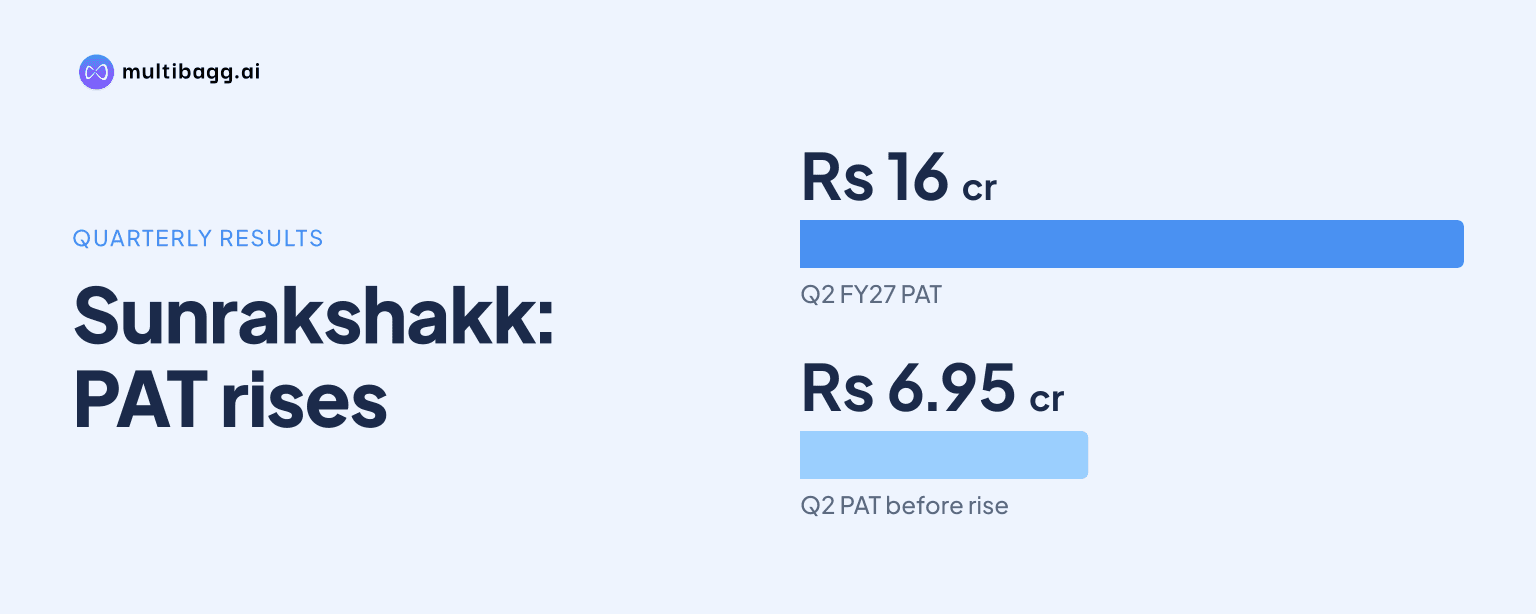
Sunrakshakk reported Q2 FY27 profit after tax of Rs 16 crore, up 130.10% year on year, as revenue from operations rose 119.20% to Rs 265.17 crore. EBITDA increased 98.26% to Rs 23.14 crore, while the EBITDA margin remained below the prior-year quarter despite sequential improvement.
Know Sunrakshakk Industries India inside out
Results, valuation, peers and who's buying, in one view.
How did Sunrakshakk perform in Q2 FY27?
Sunrakshakk delivered Rs 265.17 crore of revenue from operations in Q2 FY27, compared with Rs 120.97 crore in Q2 FY26 and Rs 276.33 crore in Q1 FY27. Revenue therefore increased 119.20% year on year but declined 4.04% sequentially. Management described Q2 FY27 as Sunrakshakk’s most profitable quarter, citing demand across fast-moving consumer goods, FMCG intermediates and edibles.
Profit after tax, or PAT, rose to Rs 16 crore from Rs 6.95 crore a year earlier and Rs 15.04 crore in Q1 FY27. The year-on-year gain was 130.10%, while PAT increased 6.38% from the preceding quarter. Basic earnings per share, or EPS, reached Rs 5.16, compared with Rs 2.24 in Q2 FY26, and profit before tax was Rs 20.38 crore against Rs 8.79 crore.
The quarterly comparison shows that profit expanded even as revenue fell from Q1 FY27. Revenue declined by Rs 11.16 crore sequentially, whereas EBITDA increased by Rs 0.55 crore and PAT by Rs 0.96 crore. Total expenditure fell to Rs 242.03 crore in Q2 FY27 from Rs 253.74 crore in Q1 FY27.
Why was Sunrakshakk’s EBITDA margin below the prior-year level?
Sunrakshakk’s Q2 FY27 EBITDA margin was 8.73%, 92 basis points below 9.65% in Q2 FY26, even though EBITDA nearly doubled to Rs 23.14 crore. Management said higher input costs continued to affect year-on-year margins. Raw-material expenses rose to Rs 197.22 crore from Rs 81.56 crore as revenue increased from Rs 120.97 crore to Rs 265.17 crore.
The margin did improve by 55 basis points from 8.18% in Q1 FY27. Management attributed the sequential change to easing raw-material cost ratios. Other expenses were Rs 38.35 crore in Q2 FY27, slightly below Rs 38.58 crore in Q1 FY27, while employee expenses rose to Rs 6.46 crore from Rs 6.26 crore.
PAT margin moved higher in both comparisons, reaching 6.03% in Q2 FY27 from 5.75% in Q2 FY26 and 5.44% in Q1 FY27. Depreciation fell to Rs 2.08 crore from Rs 3 crore a year earlier, while other income declined to Rs 0.29 crore from Rs 0.92 crore. These items coincided with a 28-basis-point year-on-year and 59-basis-point sequential improvement in PAT margin.
For H1 FY27, EBITDA increased 96.32% to Rs 45.73 crore from Rs 23.30 crore in H1 FY26, but the EBITDA margin declined 101 basis points to 8.45%. H1 PAT rose 130.39% to Rs 31.04 crore and PAT margin increased 26 basis points to 5.73%, from 5.47% a year earlier.
Got a follow-up? Ask IRIS
Which businesses drove Sunrakshakk’s revenue growth?
Sunrakshakk’s FMCG, FMCG intermediates and edibles businesses together contributed 90.85% of consolidated Q2 FY27 revenue, according to management. The presentation shows FMCG revenue of Rs 240.92 crore and textile revenue of Rs 24.25 crore, together equalling total Q2 revenue of Rs 265.17 crore. In Q2 FY26, FMCG revenue was Rs 94.74 crore and textile revenue was Rs 26.23 crore.
The Rs 144.20 crore year-on-year increase in quarterly revenue was concentrated in FMCG. FMCG revenue increased by Rs 146.18 crore between Q2 FY26 and Q2 FY27, while textile revenue declined by Rs 1.98 crore. Management also reported that FMCG segment-result margin expanded to 9.27% from 6.34% in Q2 FY26, attributing the change to operating leverage.
The longer-term mix indicates a substantial change in Sunrakshakk’s business composition. Textile accounted for 100% of revenue in FY24, then 58% in FY25 and 17% in FY26; FMCG accounted for 0%, 42% and 83%, respectively. In H1 FY27, the split was 91% FMCG and 9% textile.
Management’s FY28 estimate is a revenue mix of 90% FMCG and 10% textile, compared with 91% and 9% in H1 FY27. The presentation lists products in household and food categories, including SHINOL, CAVICO, Majedar Bhujia, Chaat Masala, DISHAHAR DAL, BIZZ POWER+ and PIXIE, but does not disclose sales by product or brand.
What capacity expansion and revenue plan has management disclosed?
Sunrakshakk said its Guwahati facility ramp-up and an additional soap production line at Roorkee increased installed FMCG and FMCG-intermediates capacity to 20,840 tons per month. The presentation identifies capacity expansion at Guwahati, Roorkee and Bhilwara as part of the capital deployment supporting the FMCG and edibles platform.
Management said Rs 98.65 crore was raised for the acquisition of Sunrakshak Agro Products Private Limited, effective 27 December 2024. The historical financial statements state that FY25 figures were consolidated with that entity’s financials from 1 January 2025. They also caution that historical ratios are not directly comparable because Sunrakshakk shifted from a textile-focused business to an FMCG-led model.
Management’s earlier aspiration was to reach approximately Rs 1,000 crore of revenue by FY28. H1 FY27 revenue was Rs 541.50 crore, more than half of that figure in six months, and management said the company was ahead of the pace originally envisaged. This is a management aspiration, rather than reported revenue guidance.
The balance sheet reflects additional operating scale at 30 September 2026. Total assets were Rs 361.67 crore, up from Rs 323.95 crore at 31 March 2026; inventories increased to Rs 108.89 crore from Rs 85.17 crore, and property, plant and equipment rose to Rs 109.77 crore from Rs 99.15 crore. Short-term borrowings increased to Rs 18.17 crore from Rs 13.96 crore over the same period.
Conclusion
Sunrakshakk’s Q2 FY27 results combined rapid revenue and profit expansion with a mixed operating-margin outcome. Revenue rose to Rs 265.17 crore and PAT reached Rs 16 crore, supported mainly by FMCG revenue of Rs 240.92 crore. However, the 8.73% EBITDA margin remained below the 9.65% reported in Q2 FY26, as management cited higher input costs.
The next factors to watch are the use of the 20,840-tonne-per-month FMCG and FMCG-intermediates capacity, raw-material cost ratios and progress toward management’s approximately Rs 1,000 crore FY28 revenue aspiration. H1 FY27 revenue was Rs 541.50 crore, while inventories were Rs 108.89 crore and short-term borrowings were Rs 18.17 crore at 30 September 2026.