










Susan Electricals expects LT cable share to fall to 10%-20%
Key highlights
- Susan Electricals expects LT cables to account for 10%-20% of FY27 revenue.
- HT cable and MVCC sales rose from Rs 52 lakh in H1 FY26 to about Rs 39 crore in H1 FY27.
- HT cables and MVCC accounted for Rs 54 crore of Susan Electricals’ Rs 147 crore order book at September 30, 2026.
- Susan Electricals targets cable capacity of 16,000 kilometres with commercial production from March 2027.
powered by IRIS
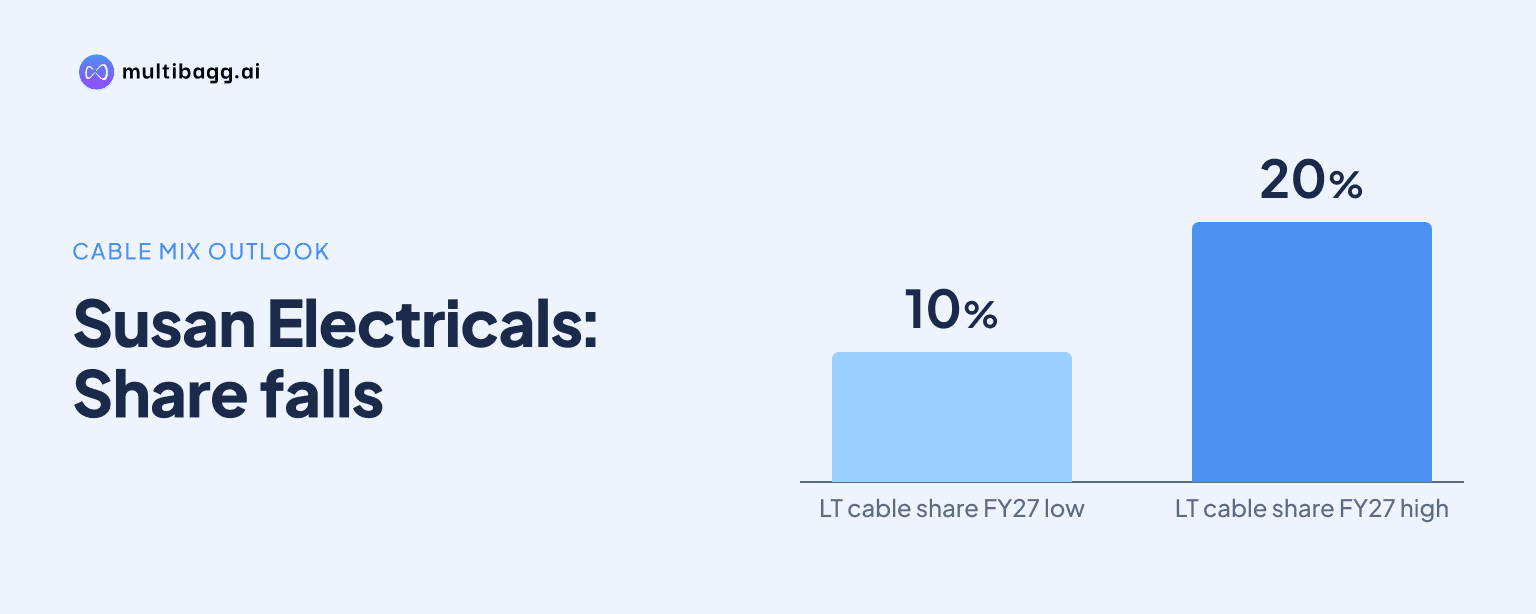
Susan Electricals India Limited expects LT cables to account for 10%-20% of FY27 revenue after HT cables and medium-voltage covered conductors, or MVCC, reached about 30% of Q2 FY27 sales. Management’s expectation is supported by Rs 54 crore of HT and MVCC orders within the Rs 147 crore order book at September 30, 2026.
Know Susan Electricals India inside out
Results, valuation, peers and who's buying, in one view.
How is Susan Electricals changing its product mix?
Susan Electricals is shifting revenue toward HT cables, MVCC and winding wires while reducing LT cables’ relative contribution. Management said Q2 FY27 sales comprised approximately 30% HT and MVCC, 33% winding wires and 31% LT cables. That distribution was close to its earlier objective of an approximately equal one-third contribution from each of the three product groups.
The reported shift is substantial against H1 FY26, when management said HT cables and MVCC represented only 0.75% of revenue, LT cables represented 46%, and winding wires represented 40%. HT cables and MVCC had accounted for 8.57% of revenue in full-year FY26, indicating that their expansion accelerated during FY27.
Management expects HT cables and MVCC to contribute about 40%-50% of FY27 revenue, with winding wires at around 40%. On that basis, LT cables would account for 10%-20% of revenue, or below 20%, for FY27. These are management expectations rather than reported results for the full year.
Why are HT cables, MVCC and winding wires leading the shift?
HT cables and MVCC are leading the change because their sales rose from Rs 52 lakh in H1 FY26 to about Rs 39 crore in H1 FY27. Management identified HT cables, MVCC and winding wires as its priority products and said it would focus more on them because they deliver better margins than LT cables.
Susan Electricals’ order book at September 30, 2026, also had a greater weighting toward these products. Of the Rs 147 crore order book, HT cables and MVCC accounted for Rs 54 crore, winding wires for Rs 69 crore, and LT cables for Rs 24 crore. Winding wires were the largest category, while HT cables and MVCC represented more than one-third of the order book.
Susan Electricals executed about Rs 107 crore of orders in Q2 FY27 and said it won around Rs 111 crore of new orders during the quarter. The company also reported an active pipeline of Rs 200 crore, taking combined order-book and pipeline visibility to Rs 347 crore. The pipeline represents prospective opportunities rather than confirmed orders.
What capacity additions support Susan Electricals’ mix plan?
Susan Electricals has increased cable manufacturing capacity to 11,000 kilometres from 7,500 kilometres and plans to reach 16,000 kilometres, with commercial production targeted from March 2027. Management said the expanded cable capacity would support the scale-up of HT cables and MVCC as their order-book contribution increases.
A continuous catenary vulcanisation, or CCV, line was expected to become operational within days of the November 5, 2026 call. Management said CCV technology is mandatory for most HT cable projects and that the line would allow Susan Electricals to participate in larger and more complex projects. The call did not quantify the line’s production capacity or financial contribution.
Winding-wire capacity has increased to 4,200 tonnes from 3,307 tonnes, with a further increase to 5,500 tonnes planned. Management described the full increase as approximately 66%, while also reporting 109% growth in winding-wire sales in H1 FY27. Winding wires represented Rs 69 crore of the Rs 147 crore September order book.
Got a follow-up? Ask IRIS
What do the new mix and execution plans mean for earnings and cash flow?
Susan Electricals reported revenue from operations of Rs 202 crore in H1 FY27, up 190% from Rs 69 crore in H1 FY26. Profit after tax rose 191% to Rs 13.15 crore from Rs 4.53 crore, while operating profit increased 160% to Rs 23.78 crore. Management attributed the growth to higher execution, operating scale and demand across its portfolio.
The H1 FY27 earnings before interest, tax, depreciation and amortisation, or EBITDA, margin was 11.77%, compared with 13.13% in H1 FY26. Management attributed the 1.4-percentage-point change to one-time gains from metal-price movements in the earlier period and said margins otherwise remained within an 11.5%-12% range. It expects the changing mix to support better margins and EBITDA in future periods.
Management corrected figures published in an earlier Q1 transcript, saying 24.39% for winding wires, 7% for HT cables and 6.5% for LT cables were revenue shares rather than EBITDA margins. The current call did not provide segment-level margins, so the profitability effect of the targeted 40%-50% HT and MVCC revenue share cannot be calculated from the disclosed information.
Susan Electricals said cash flow from operations turned positive in H1 FY27, while receivables stood at Rs 95 crore at September 30, 2026. Of that amount, Rs 25 crore related to sales in the final week of September, and management said it received Rs 44 crore in October. Only 5%, or about Rs 4 crore, of receivables were older than 180 days, with about Rs 3 crore to Rs 3.5 crore of that older balance subsequently collected.
Conclusion
Susan Electricals’ reported Q2 FY27 mix and September order book show a move away from LT cables toward HT cables, MVCC and winding wires. HT and MVCC increased from 0.75% of H1 FY26 revenue to about 30% of Q2 FY27 sales, while the company expects LT cables to decline from a 31% Q2 share to 10%-20% for FY27. The Rs 54 crore HT and MVCC order book and Rs 69 crore winding-wire order book provide disclosed support for that direction.
The next disclosed milestones are commissioning of the CCV line, commercial production from 16,000 kilometres of cable capacity in March 2027, and continued collection of the Rs 95 crore September receivables balance. Management’s FY28 mix target also remains unresolved: it referred first to a 33%-33%-33% split among the three product groups, then said HT and MVCC and winding wires could each reach around 45%, with LT cables at 5%-10%.