










Tasty Dairy Specialities Limited Reports FY26 Loss of ₹4.97 Crore
Key highlights
- Tasty Dairy reported a FY26 net loss of ₹4.97 crore, compared with a ₹9.93 crore loss in FY25.
- FY26 revenue from operations fell 48.46% to ₹3.32 crore from ₹6.44 crore in FY25.
- Tasty Dairy reported zero operational revenue and a ₹0.33 crore net loss in the June 2026 quarter.
- The company has been under CIRP since October 2025, with 11 resolution plans under evaluation.
powered by IRIS
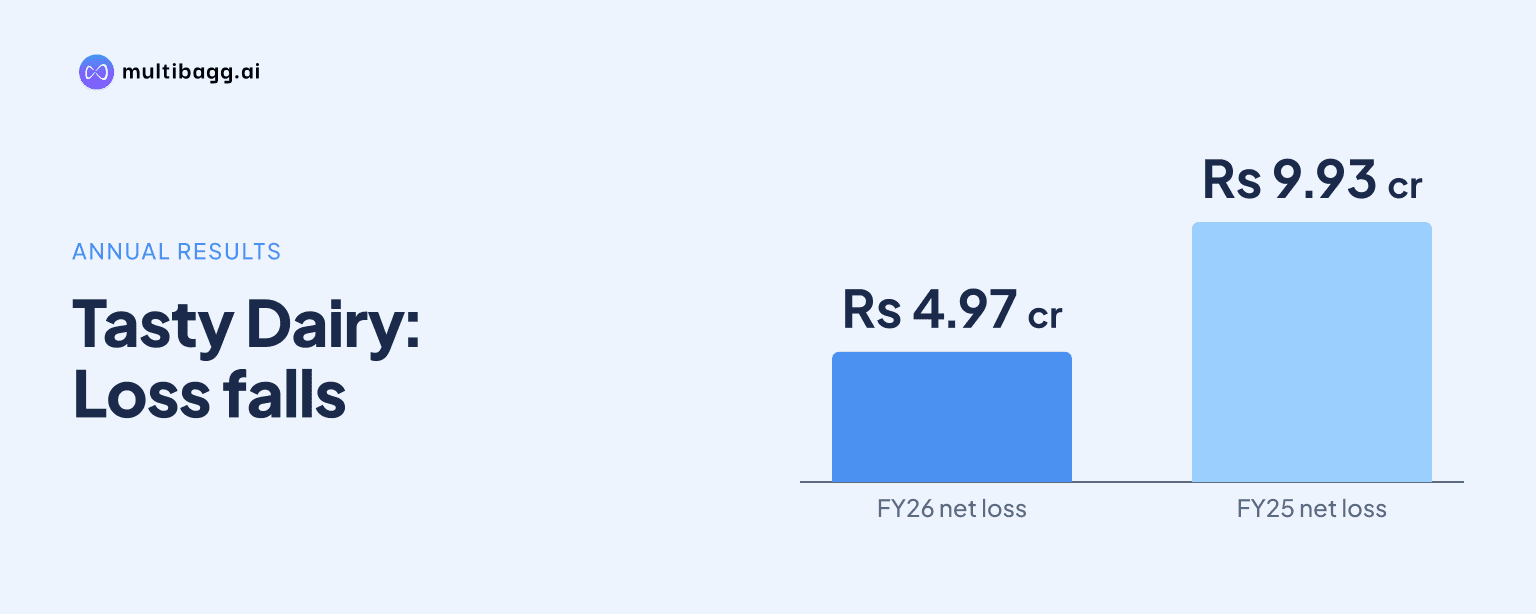
Tasty Dairy Specialities Limited reported a net loss of ₹4.97 crore for FY26, while revenue from operations declined 48.46% year-on-year to ₹3.32 crore. The results underline the company’s sharply reduced operating activity as it remains in the corporate insolvency resolution process, or CIRP.
Know Tasty Dairy Specialities inside out
Results, valuation, peers and who's buying, in one view.
What did Tasty Dairy report for FY26?
Tasty Dairy reported total income of ₹3.92 crore for the year ended March 31, 2026, compared with ₹6.47 crore in FY25. Revenue from operations was ₹3.32 crore, down from ₹6.44 crore a year earlier. The reported decline reflects a further contraction in the company’s operating scale.
The company recorded a net loss of ₹4.97 crore in FY26, compared with a loss of ₹9.93 crore in FY25. While the annual loss narrowed by nearly half, this was alongside a substantial fall in revenue. The available financial disclosures also show that no revenue from operations was recorded in the March 2026 quarter.
Tasty Dairy’s FY26 results were published in Financial Express and Lokbharti on May 14, 2026, in compliance with Regulation 47 of the SEBI Listing Obligations and Disclosure Requirements Regulations. The published extract reported total income of ₹3.92 crore and the full-year loss of ₹4.97 crore.
Why is Tasty Dairy under the insolvency process?
Tasty Dairy has been under CIRP since October 2025 following action initiated by Punjab National Bank. Under this process, the company’s affairs are managed through the insolvency framework and resolution proposals are considered by the Committee of Creditors.
The company has stated that 11 resolution plans were under evaluation by the Committee of Creditors. This makes the resolution process central to the company’s immediate corporate position, since the disclosed operating figures show limited business activity during FY26 and no revenue from operations in the March 2026 quarter.
The financial disclosures also referred to fully eroded net worth and qualified audit conclusions linked to uncertainty over asset valuation. These qualifications are material for shareholders and creditors because asset values can affect assessments of recoveries and the terms of any eventual resolution plan.
What happened in the June 2026 quarter?
Tasty Dairy reported a net loss of ₹0.33 crore for the quarter ended June 30, 2026, with zero operational revenue. The Q1 FY27 loss was ₹32.68 lakh, compared with a loss of ₹10.68 lakh in the preceding March quarter.
Expenses for the June quarter totalled ₹46.38 lakh. The disclosures attributed the expense base to items including depreciation and insolvency-related costs. Quarterly operating income was reported at a loss of ₹46.4 lakh, while EBITDA was reported at a loss of ₹16.9 lakh.
The company’s unaudited Q1 FY27 standalone results were approved by the Resolution Professional on August 11, 2026. The update also noted a qualified review report, continuing the disclosures around the company’s financial position and asset-valuation uncertainty.
Got a follow-up? Ask IRIS
How do the results affect investors and operations?
The FY26 figures show that the reduction in annual loss occurred during a period of materially lower revenue rather than an expansion in operations. Revenue from operations fell from ₹6.44 crore in FY25 to ₹3.32 crore in FY26, and the company subsequently reported zero operational revenue in both the March and June 2026 quarters.
For investors, the key disclosed issues are the ongoing CIRP, fully eroded net worth, qualified audit or review conclusions, and the evaluation of 11 resolution plans. These factors place greater importance on formal insolvency-process developments than on short-term revenue comparisons alone.
For customers, suppliers and employees, the reported absence of operational revenue in the latest disclosed quarters indicates that normal business activity was limited. The financial statements do not provide a confirmed timetable for restoration of operations, and no outcome from the resolution-plan evaluation has been disclosed.
What is the broader financial context for Tasty Dairy?
Tasty Dairy’s reported revenues have fallen sharply over several years. Total revenue was ₹1,099.17 crore in FY23, ₹397.03 crore in FY24, ₹64.43 crore in FY25 and ₹33.20 crore in FY26, based on the financial-statement data provided. This sequence shows that FY26 followed a prolonged decline in reported scale.
The company’s FY26 total income of ₹3.92 crore was slightly higher than its revenue from operations of ₹3.32 crore, indicating the presence of other income in the reported total. However, the disclosed information does not provide enough detail to treat non-operating income as evidence of a recovery in underlying dairy operations.
The latest results therefore need to be assessed in the context of the insolvency process and continuing financial-report qualifications. The disclosed total assets of ₹57.81 crore in June 2026 provide a reported balance-sheet figure, but the stated asset-valuation uncertainty remains relevant to the eventual resolution process.
Conclusion
Tasty Dairy’s FY26 loss narrowed to ₹4.97 crore from ₹9.93 crore, but its revenue from operations declined 48.46% to ₹3.32 crore and operating revenue was zero in the March and June 2026 quarters. The figures point to a company with sharply constrained operations rather than a confirmed improvement in operating momentum.
Investors will watch the Committee of Creditors’ assessment of the 11 resolution plans, along with any disclosed outcome under CIRP. Future financial filings will also be relevant for updates on operating revenue, asset valuation matters and the qualified audit or review conclusions.