










Taurian MPS Limited Has ₹94.23 Crore Orders Due Within Five Months
Key highlights
- Taurian MPS has ₹94.23 crore of advance-backed orders to execute in the next four to five months.
- Domestic orders total ₹71.91 crore, or 76%, while export orders total ₹22.32 crore, or 24%.
- The Roorkee facility has capacity for 155 plants per annum and reported 65% capacity utilisation.
- H1FY27 revenue was ₹56.01 crore, compared with ₹32.29 crore in H1FY26.
powered by IRIS
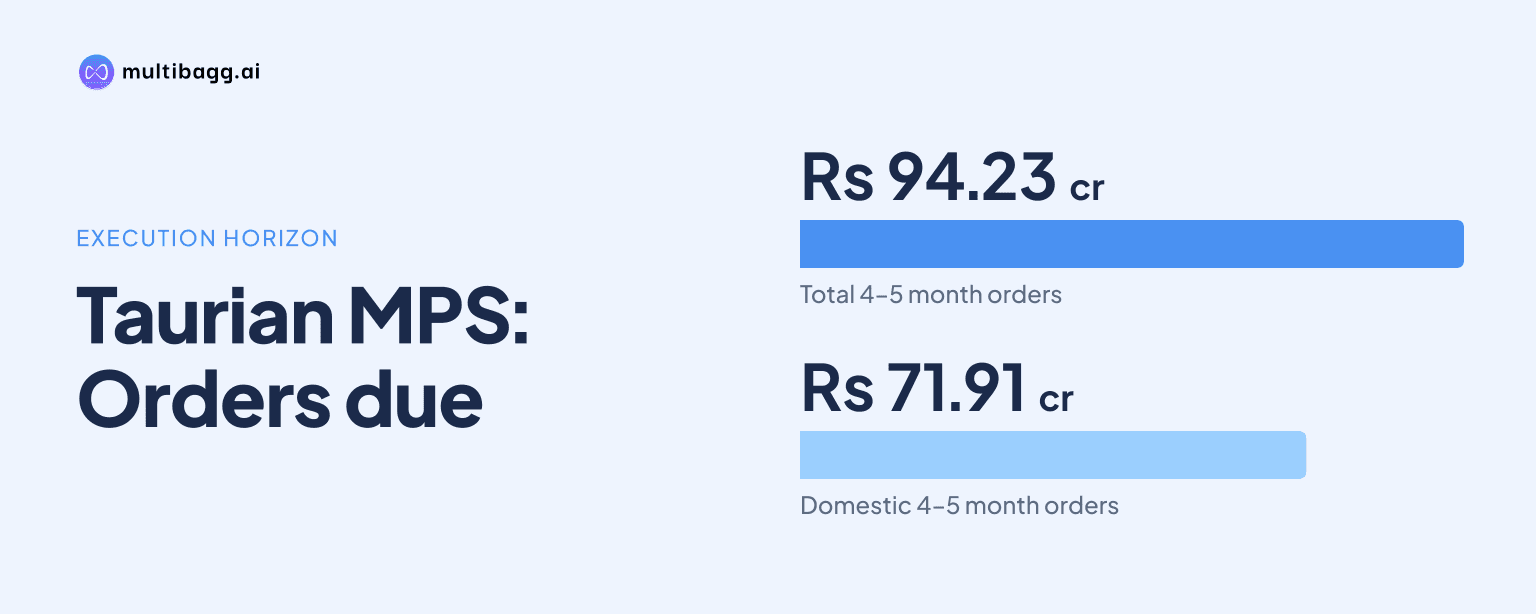
Taurian MPS Limited has ₹94.23 crore of advance-backed orders to execute over the next four to five months, alongside 65% utilisation at its Roorkee facility, which has capacity for 155 plants annually; ₹71.91 crore, or 76%, is domestic. This makes delivery against the stated window the immediate disclosed operating test.
Know Taurian MPS inside out
Results, valuation, peers and who's buying, in one view.
What orders must Taurian MPS execute within five months?
Taurian MPS must execute ₹94.23 crore of orders for which it has received advances within the next four to five months. The presentation describes this amount as the total order book at hand, rather than a pipeline or sales target. It does not disclose the number of customers, individual contracts, equipment units or delivery milestones behind the ₹94.23 crore figure.
Domestic orders account for ₹71.91 crore, or 76%, of the total, while export orders account for ₹22.32 crore, or 24%. Domestic business exceeds export business by ₹49.59 crore in the disclosed book. The export share is nearly one-quarter of the order value, but Taurian MPS does not identify the export markets, products or shipment dates.
The four-to-five-month execution window is shorter than a financial year and should not be read as annual revenue guidance. Taurian MPS does not state the date on which the ₹94.23 crore order book was measured, the amount already in production or whether orders have cancellation provisions. Those omissions prevent a calculation of order inflow, monthly production requirements or conversion into reported revenue.
How much manufacturing capacity does Taurian MPS have?
Taurian MPS reports annual manufacturing capacity of 155 plants at its Roorkee, Uttarakhand facility, where reported capacity utilisation is 65%. The site covers 1,10,000 square feet. The presentation therefore shows that the facility is not operating at its stated full annual capacity, although it does not translate the 65% figure into a number of plants produced.
The Roorkee plant manufactures primary, secondary, tertiary and washing plants. That product span matters because the ₹94.23 crore order book may contain systems with different component needs, manufacturing cycles and installation requirements. Taurian MPS does not disclose the product mix of either the ₹71.91 crore domestic book or the ₹22.32 crore export book, so order value cannot be directly matched to the 155-plants-per-annum capacity measure.
The disclosed utilisation rate is a baseline for monitoring delivery rather than confirmation that every order will be completed in four to five months. Management says it plans to expand manufacturing capacity at the existing facility, but gives no capacity addition, commissioning date or spending split for that expansion. The stated 65% utilisation also does not specify whether the measure is based on units, machine hours, production value or another method.
Got a follow-up? Ask IRIS
How does the order book compare with Taurian MPS's H1FY27 results?
The ₹94.23 crore order book is larger than Taurian MPS's reported H1FY27 revenue of ₹56.01 crore, but the two measures cover different periods. H1FY27 is a half-year reporting period, while the order book is scheduled for execution over four to five months. The table defines earnings before interest, tax, depreciation and amortisation as EBITDA and compares the three disclosed half-year periods.
Revenue increased by ₹23.72 crore between H1FY26 and H1FY27, after rising by ₹2.08 crore between H1FY25 and H1FY26. EBITDA rose from ₹6.76 crore in H1FY26 to ₹12.34 crore in H1FY27, while profit after tax increased from ₹3.67 crore to ₹7.65 crore. The presentation reports compound annual growth rates of 36.16% for revenue, 41.30% for EBITDA and 43.21% for profit after tax across H1FY25 to H1FY27.
The financial comparison shows a larger revenue and earnings increase in H1FY27 than in the preceding half-year comparison. However, Taurian MPS does not disclose the expected revenue-recognition schedule, gross margin, working-capital cycle or product mix for the ₹94.23 crore order book. Delivery and installation can therefore precede the recognition of all related revenue in a particular reporting period.
How is Taurian MPS funding intended to support execution?
Taurian MPS raised ₹59.97 crore through preferential and warrant-related funding, allocating ₹42.00 crore to working-capital requirements, ₹10.22 crore to capital expenditure and ₹7.75 crore to general corporate purposes. Promoter participation was ₹20.94 crore and non-promoter participation was ₹39.03 crore. Working capital is the largest stated allocation, exceeding capital expenditure by ₹31.78 crore.
Management says the ₹59.97 crore fund-raise addressed a working-capital constraint that had limited execution scale. According to the managing director, the capital is intended to accelerate inventory and component procurement, shorten execution timelines and enable a larger volume of orders. These are management expectations, not reported outcomes for the current ₹94.23 crore order book.
Separately, the presentation describes a planned ₹10.00 crore capital expenditure programme to internalise key manufacturing activities, with expected annual savings of more than ₹2.10 crore. It does not state whether that ₹10.00 crore programme is the same as, additional to or partly funded through the ₹10.22 crore capital-expenditure allocation. Management also targets topline growth of 45% to 50% compound annually over the coming years and an export contribution of 35%, compared with 18% in FY26.
Conclusion
Taurian MPS has a stated ₹94.23 crore advance-backed order book concentrated in domestic business, with ₹71.91 crore of orders, while its single Roorkee facility reports 155 plants of annual capacity and 65% utilisation. The comparison with H1FY27 revenue of ₹56.01 crore shows that the disclosed execution requirement is substantial relative to the latest half-year sales figure, though the reporting periods differ.
The next disclosures to watch are progress against the four-to-five-month delivery window, any change in the 65% utilisation rate and details of planned capacity additions. Management's 45% to 50% topline growth target, 35% export-contribution target and planned ₹10.00 crore internalisation programme will depend on execution, but the presentation does not provide a delivery schedule or capacity-expansion completion date.